
What Woori Financial Group Doubters Overlooked
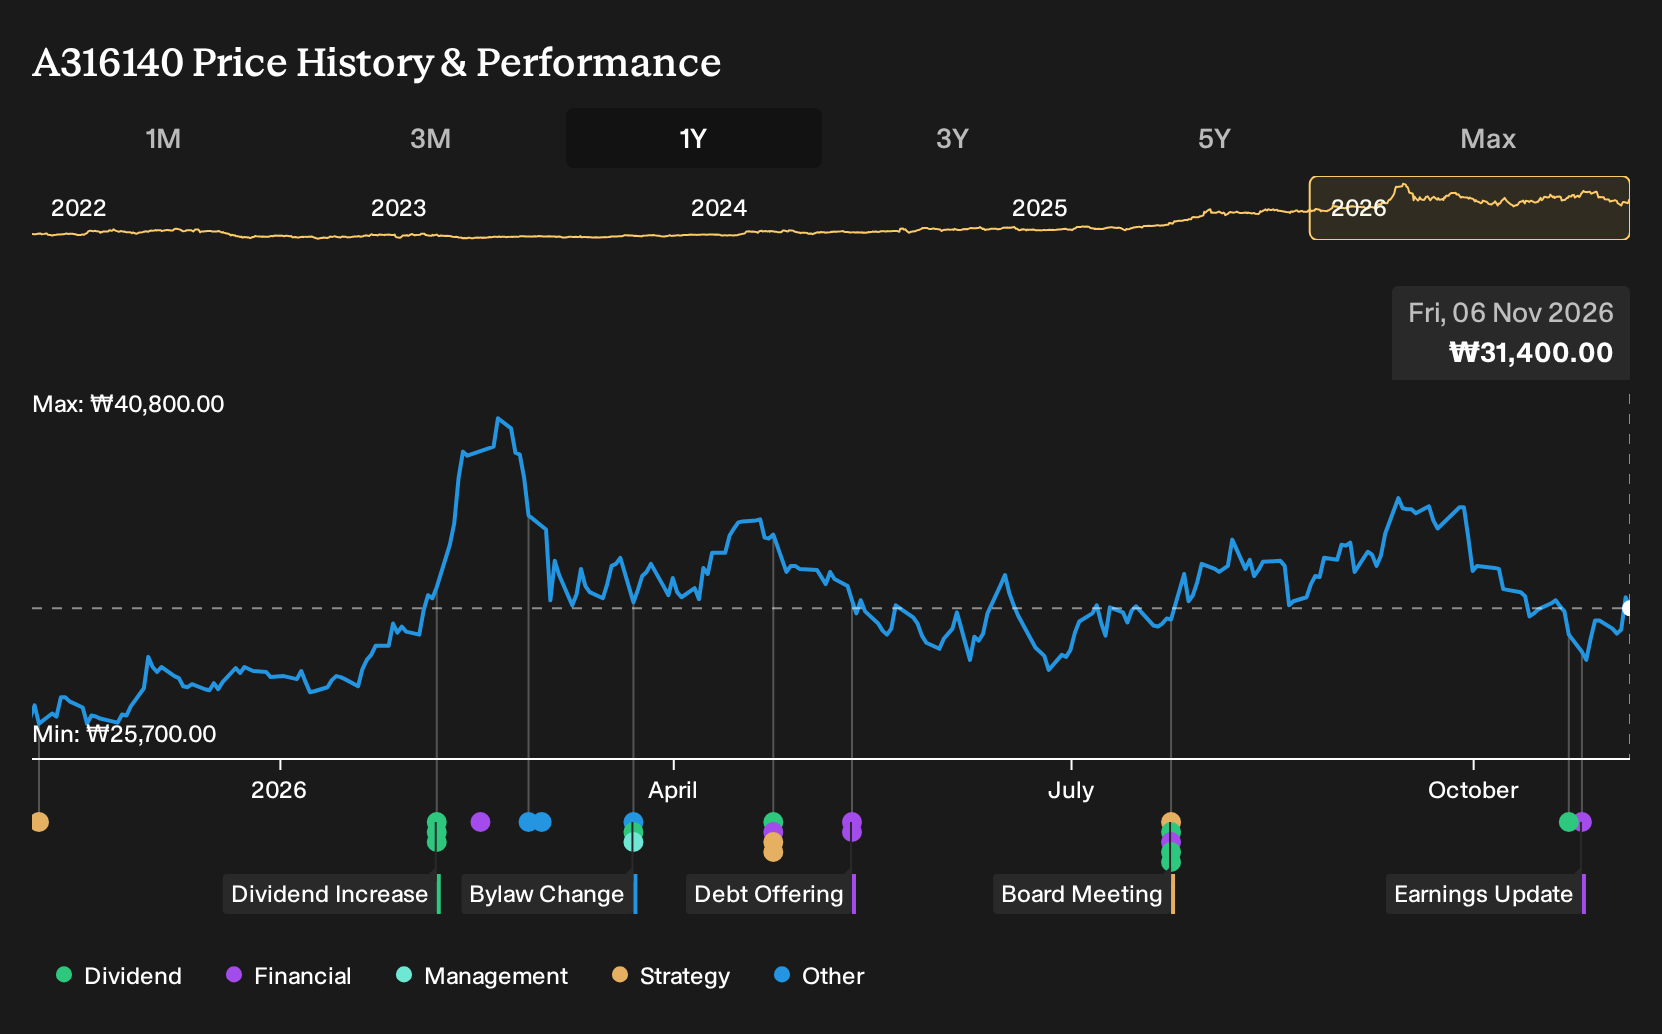
Revenue up, profit down. That was the puzzle in Woori Financial Group’s latest annual snapshot, with net margin slipping even as the top line reached higher. For Woori Financial Group shareholders, the return over the past year was 26.3%, including dividends. If you had bought on 6 November 2025, knowing analysts were split between upside from buybacks and pressure on lending and credit costs, what did this outcome really say about the original risk you were weighing?
If the move has made Woori Financial Group harder to judge, start where the gap is still open and scan 223 high quality undervalued stocks.
The Two Stories Investors Were Weighing On Woori Financial Group
The shares cost ₩26,650 at the start of the period, and anyone looking at Woori Financial Group had to choose which future seemed more plausible.
On the optimistic side, the bullish view put Fair Value at ₩29,095, a notional target based on its own rulebook of assumptions. That story leaned on treasury stock acquisition completion, diversification into insurance and securities, and a 4.6% revenue growth assumption with profit margin reaching 31.4% on a 7.0x future P/E.
The cautious camp worked off a Fair Value of ₩18,000, again an implied price built from a different set of expectations. This narrative stressed South Korea’s aging population, heavy domestic exposure, and a 2.5% revenue growth assumption paired with margin rising to 31.1% and a lower 5.3x future P/E.
What The Results Changed For Woori Financial Group
The clearest fact was the earnings line. Woori Financial Group reported Q3 2026 revenue of ₩2,643,000m versus ₩2,469,605m a year earlier, while net income fell from ₩1,206,724m to ₩1,049,000m and net margin slipped from 48.9% to 39.7%. That combination of higher sales and weaker profitability has implications for both optimistic and cautious perspectives on the business.
The key lesson is simple. When a thesis relies on margin expansion, it is important to track net margin first, not just revenue or EPS, and to test that claim against each earnings release for any bank you study.
What Woori Financial Group's Price Now Assumes
Woori Financial Group trades at ₩31,400 today, after a 26.3% gain over the past year from ₩26,650. The selected Narrative’s Fair Value currently sits above the market price and is based on a case centered on capital returns, credit discipline, and a different profit mix.
In practical terms, that Narrative states that today’s price still does not fully reflect sustained non bank earnings growth and AI driven cost efficiency, assuming credit costs remain within management’s guided ranges.
"The main thing that has to go right is that Woori Financial Group successfully executes its shift toward productive finance and AI driven efficiency while keeping credit costs and asset quality within the guided ranges. The current numbers and capital return plan imply a share price that does not fully reflect Woori Financial Group’s higher CET1 ratio, record net operating revenue, and increased cash and non taxable shareholder distributions."
The price and this Narrative do not agree. → Uncover what this Narrative says Woori Financial Group is actually worth
Looking Beyond Woori Financial Group
Woori Financial Group is leaning hard into AI driven efficiency and productivity. You could look one step sideways.
Large banks everywhere are wrestling with the same question. How do you turn big deposit bases and long standing relationships into richer fee streams?
One global lender is using digital and AI spending to push that shift. Its tools aim to deepen engagement, trim support needs, and tighten risk checks.
The same institution is also expanding outside its home market to chase more corporate activity. That mix of technology spending and broader reach creates a different profit story.
It is still unresolved and evolving, and offers another financial transformation to study next.
One Narrative has already put a figure on it. → Uncover the company trading 22% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com