
Property Buybacks Might Change The Case For Investing In Terreno Realty Stock (TRNO)
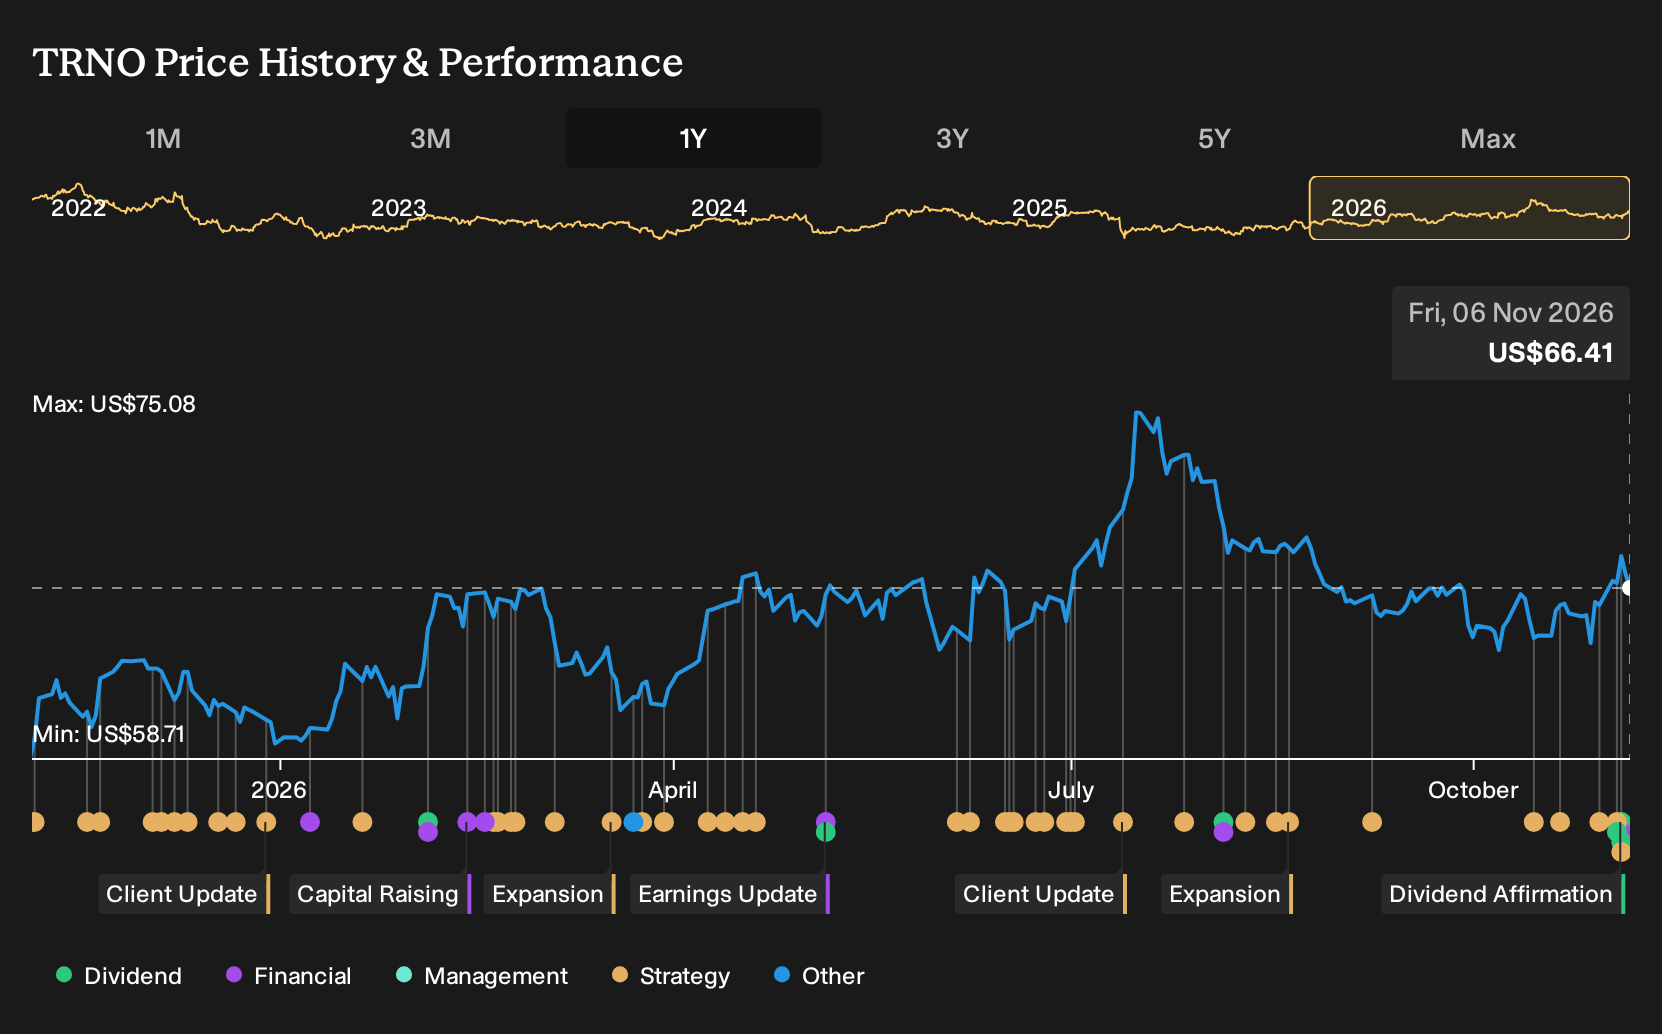
- Terreno Realty Corporation reported third quarter 2026 revenue of US$132.23 million and net income of US$68.11 million, declared a US$0.57 quarterly dividend, acquired industrial assets in California and New Jersey, secured a new logistics lease in New Jersey, and received approval for a share repurchase program of up to 3,000,000 shares through 2028.
- Together, the fresh capital deployment into industrial properties, the long dated Avenel logistics lease, and the new buyback authority highlight Terreno Realty’s focus on occupied coastal warehouses and direct cash returns, while third quarter earnings per share and net income tracked below the prior year period.
- Attention now turns to how Terreno Realty's investment narrative absorbs this new share repurchase authorization and what it signals about capital priorities.
What Is Terreno Realty's Investment Narrative?
To own Terreno Realty, you need to be comfortable with a straightforward pitch. This is a coastal industrial landlord that depends on how well it keeps warehouses full at sensible rents while recycling capital into properties with attractive stabilized cap rates. The latest quarter showed higher revenue but lower net income and earnings per share, so execution around lease terms, operating costs, and any one off items is front and center. The Avenel logistics lease and fully occupied acquisitions in New Jersey and Maryland support that operating story rather than changing it.
In the short term, the key levers are still occupancy, rent on rollovers, and how efficiently Terreno Realty deploys capital into places like San Carlos at a 5.7% estimated stabilized cap rate. The affirmed US$0.57 dividend and fresh buyback capacity indicate that management is comfortable sharing cash while it invests, which may matter if earnings forecasts pointing to declines put pressure on the P/E of 20.8x. The risk side remains present, with earnings growth slowing from the past five year pace and leverage entirely from higher risk funding sources, but the recent news largely refines rather than rewrites the broader thesis.
That said, before assuming this mix of coastal warehouses, dividends, and buybacks is a straightforward hold, there is a catch if ...
There's only one way to know the right time to buy, sell or hold Terreno Realty. Head to Simply Wall St's company report for the latest analysis of Terreno Realty's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community includes 2 retail investors with fair value estimates for Terreno Realty that cluster between about US$67.61 and US$73.53 per share. Those views were formed before the latest dividend affirmation, buyback authorization, and coastal acquisitions, so you are seeing opinions that have not yet absorbed these recent capital allocation signals. You should expect wide disagreement and explore several of these viewpoints before deciding how the new data fits your own Terreno Realty thesis.
Explore another Terreno Realty fair value estimate, including one that suggests up to 11% upside from the current price.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and relying on your independent judgment.
- A great starting point for your Terreno Realty research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Terreno Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Terreno Realty's overall financial health at a glance.
Looking For More Ideas Beyond Terreno Realty?
If you want to cross check Terreno Realty against other opportunities, the Simply Wall St Screener can help you line up businesses with different strengths and see what really fits your approach.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without relying heavily on extra funding.
- If value is your priority, compare Terreno Realty with a 38 high quality undervalued stocks based on strong fundamentals and reasonable pricing.
- Income focused readers can scan a 7 dividend fortresses that combines higher yields with an emphasis on sustainability and balance sheet support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com