
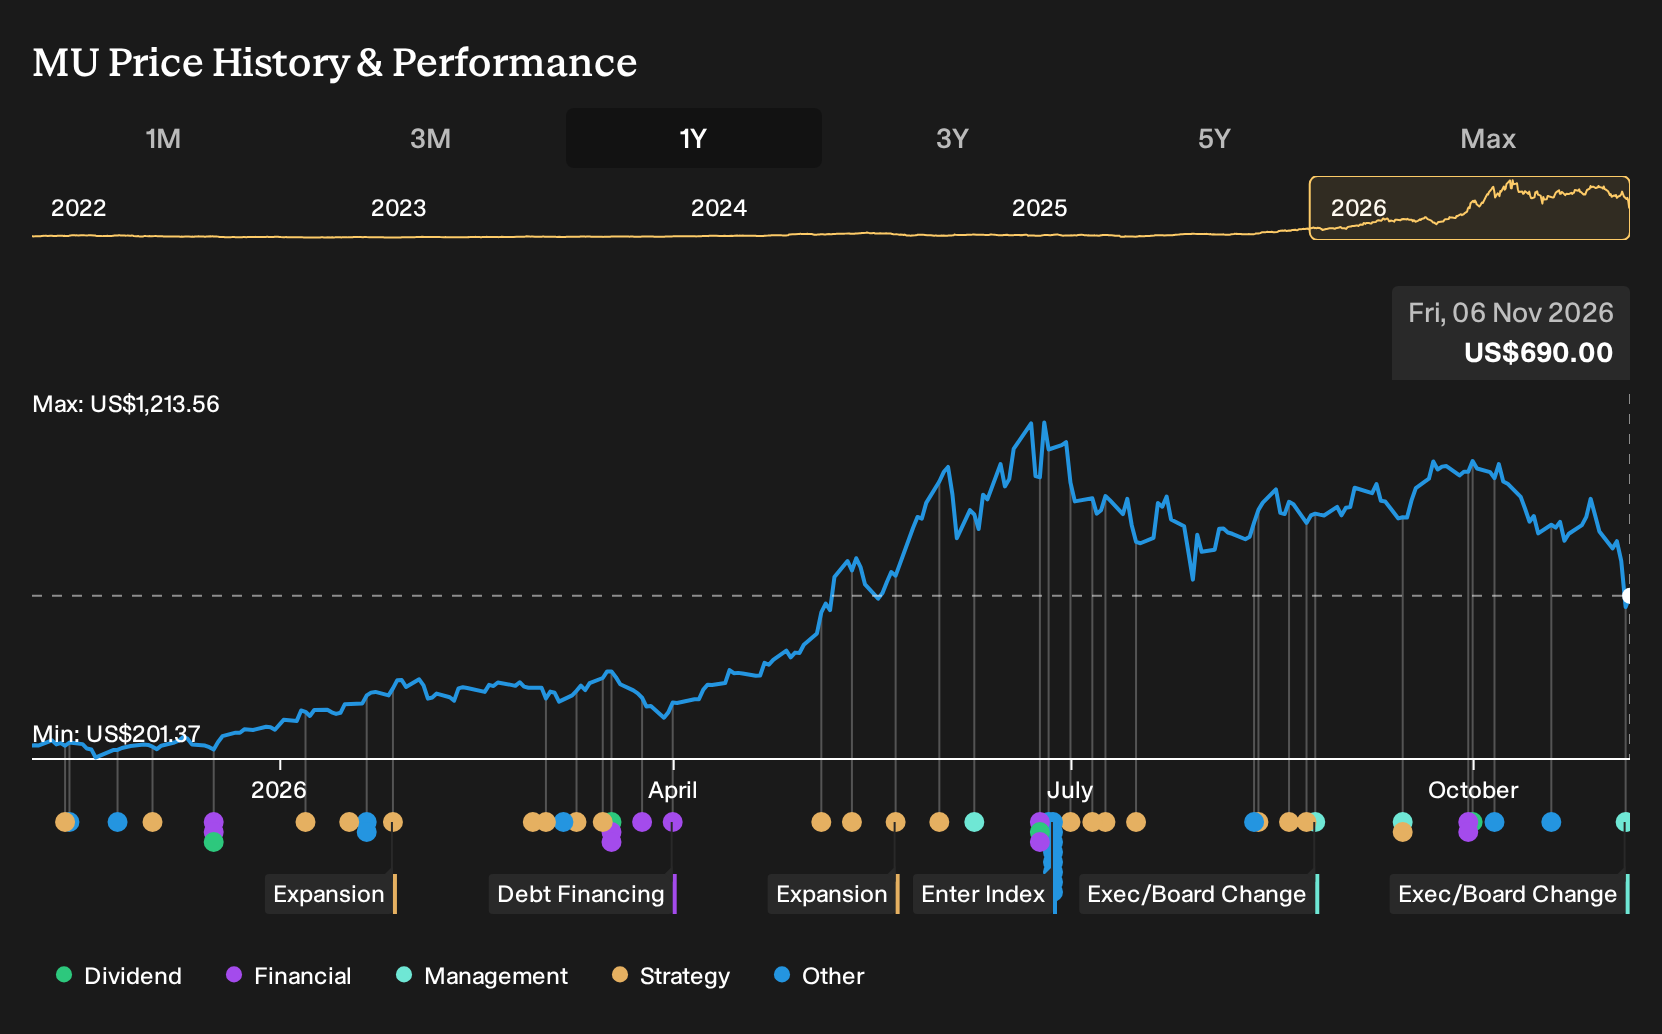
Micron Stock Has The Bull Case Changed After Taiwan Fab Halt?
- Micron Technology is dealing with tighter scrutiny of AI data center buildouts after recent U.S. elections and a halted Taiwan fab project caused by a profit sharing dispute with local workers.
- The same headlines that raised questions about Micron Technology's regulatory and labor exposure also highlighted how dependent its memory business is on large scale AI data center demand.
- We will look at how Micron Technology's investment narrative around AI driven memory demand is challenged by the Taiwan labor dispute.
Scan how the AI memory story is playing out beyond Micron Technology by comparing it with a curated group of 53 AI infrastructure stocks that are also exposed to data center buildouts and regulatory risk.
Micron Technology Investment Narrative Recap
To stay comfortable owning Micron Technology, you need to believe its AI driven demand for DRAM, HBM and data center SSDs can support strong cash generation even as margins normalise from very high levels. The key near term swing factor is whether tight supply and committed data center orders offset any pause in large AI buildouts after the recent political reset.
The biggest risk right now is simple. Very high capital spending of roughly US$27b in fiscal 2026, plus further heavy outlays in 2027, meets any slowdown in orders or pricing. The Taiwan fab dispute and data center scrutiny increase execution risk, but they do not yet fundamentally change that core AI memory thesis.
Among the recent developments, the halt of Micron Technology’s planned Fab 11E in Taoyuan, Taiwan, looks most relevant to the current news flow. Taiwan accounts for a large portion of Micron’s DRAM output, so any prolonged disruption to new capacity intersects directly with the AI data center story that has driven the business.
The union’s profit sharing push, and Micron’s decision to pause a US$3b to US$4.5b facility, feed into the same near term catalyst investors are watching. Tight DRAM and NAND conditions support pricing, while high fixed costs and political scrutiny of data center expansion raise the risk of overshoot. How quickly Micron resolves the Taiwan labor dispute and realigns its buildout plans will be important for execution and future flexibility.
Micron Technology's current analyst storyline points to US$320.4b in revenue and US$217.9b in earnings by 2029. That profile rests on forecast revenue growth of 34.0% a year and an earnings increase of about US$132.9b from US$85.0b today.
Discover how Micron Technology's fair value indicates a 126% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic Micron Technology analysts focus on the Taiwan labor dispute as a potential catalyst rather than just a headache. They previously pencilled in revenue of about US$394.4b and earnings near US$241.9b by 2029, a far more upbeat script that might change once the board retirement news and fab halt fully feed into their models.
Explore 29 other Micron Technology fair value estimates, including one that suggests as much as 237% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Micron Technology research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Micron Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Micron Technology's overall financial health at a glance.
Looking for more Micron Technology sized ideas?
If this Micron Technology story has sharpened your thinking, use the same lens across a wider watchlist. The Simply Wall St Screener can help you quickly sort through opportunities that fit different priorities, from resilience to yield to undervaluation.
- For investors who want potential upside backed by fundamentals, scan a curated 38 high quality undervalued stocks that combine quality businesses with prices that may not fully reflect their underlying strength.
- If capital preservation matters just as much as returns, narrow your search to a 31 resilient stocks with low risk scores that have more resilient profiles and lower risk scores.
- When balance sheet strength is non negotiable, focus your research on a list of solid balance sheet and fundamentals (25 results) that pair healthier leverage and liquidity with solid underlying operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com