
AptarGroup (ATR) Just Gave Investors Something To Think About
Why AptarGroup’s latest earnings, dividend move and buyback matter
AptarGroup (ATR) just combined softer profitability with shareholder payouts. Third quarter revenue rose to US$1,019.12 million, while net income dropped to US$32.6 million. At the same time, management raised its dividend and completed a buyback tranche.
These announcements landed after a strong run in AptarGroup’s shares, with a 30 day share price return of 18.38% and a year to date gain of 16.29%. The 1 year total shareholder return of 24.01% points to momentum that has been building rather than fading.
Seize this chance to compare AptarGroup’s mix of rising revenue, softer earnings and capital returns with a curated list of 31 resilient stocks with low risk scores.For AptarGroup, a softer profit line alongside a higher dividend and recent buybacks raises a simple tension. Is the sharp share price move pointing to a stronger business, or is it just a swing in sentiment that the valuation now has to justify?
Most Popular Narrative: 12% Undervalued
AptarGroup’s most followed narrative pegs fair value at $162.00 compared with a last close of $142.50, which puts the recent earnings, dividend change and buyback into a context of underappreciated long term cash generation.
The rapid expansion of AptarGroup''s proprietary drug delivery systems in areas such as injectables for biologics and central nervous system therapies remains a live driver. This is supported by a Pharma segment that has delivered a 9% top-line CAGR over nine years and maintains a 32% to 36% EBITDA margin range, which can support future earnings power.
See why 7 investors see AptarGroup as 12% undervalued.
Using a 7.24% discount rate, that most popular storyline suggests AptarGroup’s mix of pharma centric growth projects and capital returns supports a fair value that is meaningfully above the current share price, even after the recent rally. Analysts in that framework are effectively arguing that the market price does not fully reflect the earnings potential of the higher margin Pharma segment or the impact of ongoing buybacks on per share outcomes.
Result: Fair Value of $162.00 (UNDERVALUED)
Still, the emergency medicine destocking that is expected to cut about US$65 million from 2026 Pharma sales and the ongoing legal costs could unsettle that underappreciated earnings story.
Find out about the key risks to this AptarGroup narrative.
Another View: AptarGroup looks expensive on earnings multiples
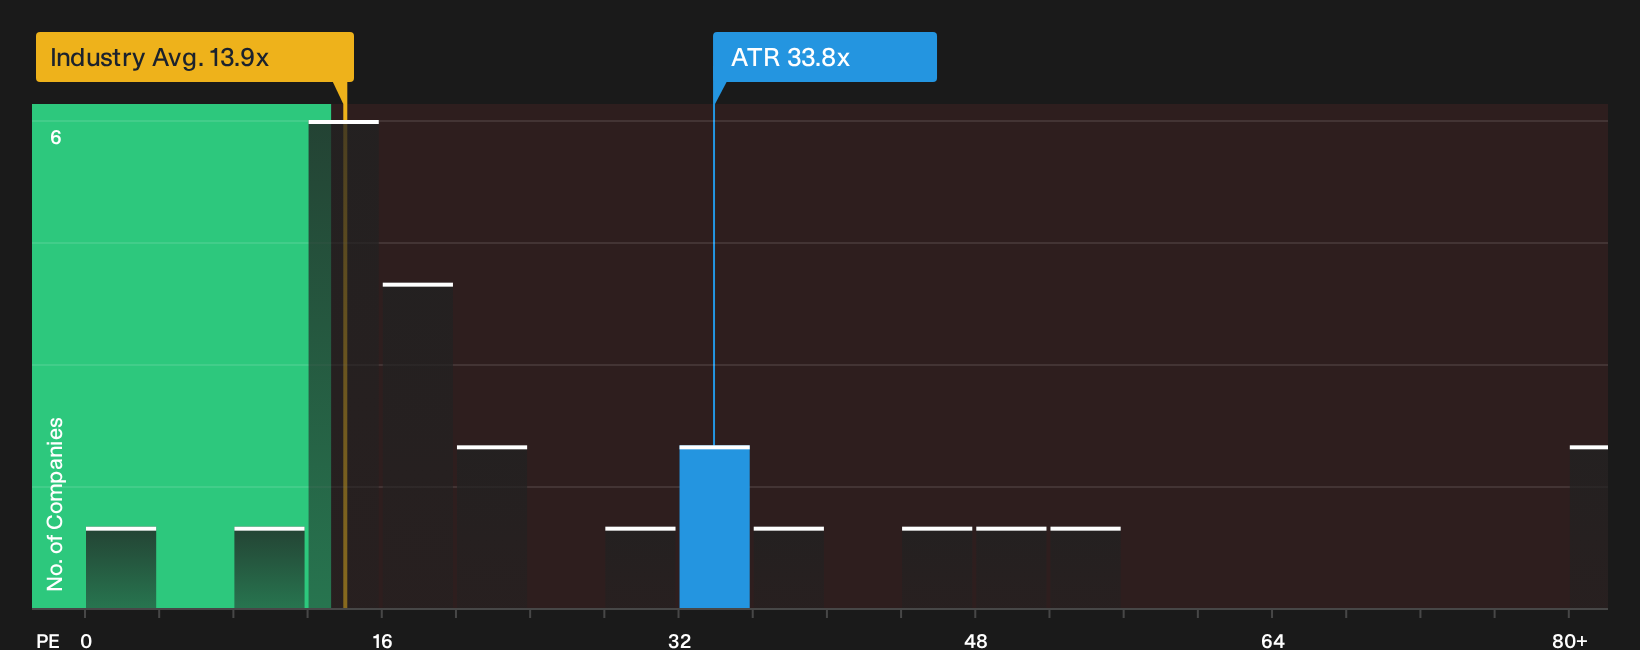
The DCF story paints AptarGroup as undervalued, yet the simple P/E check tells a different story. At 33.8x earnings versus 13.8x for the global Packaging industry and 20.3x for peers, and above a fair ratio of 20.6x, investors are paying a rich premium. How comfortable are you with that mismatch?
To see how this earnings based view stacks up against the full valuation breakdown, including the fair ratio and peer comparisons, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on AptarGroup so far, with rich multiples sitting alongside that underappreciated cash flow story, make this a moment to move quickly and test the numbers yourself. To weigh those cross currents properly, go straight to the 3 key rewards and 3 important warning signs.
Looking for more AptarGroup style investment ideas?
If AptarGroup has sharpened your focus, do not stop here. Use Simply Wall Street's tools to quickly compare different opportunities and pressure test your next move.
- Target stability first and scan companies with resilient balance sheets and consistent fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for value by checking the 19 high quality undiscovered gems that pair strong financial quality with limited market attention.
- Prioritize downside protection and review the 31 resilient stocks with low risk scores that score well on risk while still aiming for meaningful upside potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com