
How Record Earnings Will Impact Horace Mann Educators Stock (HMN)
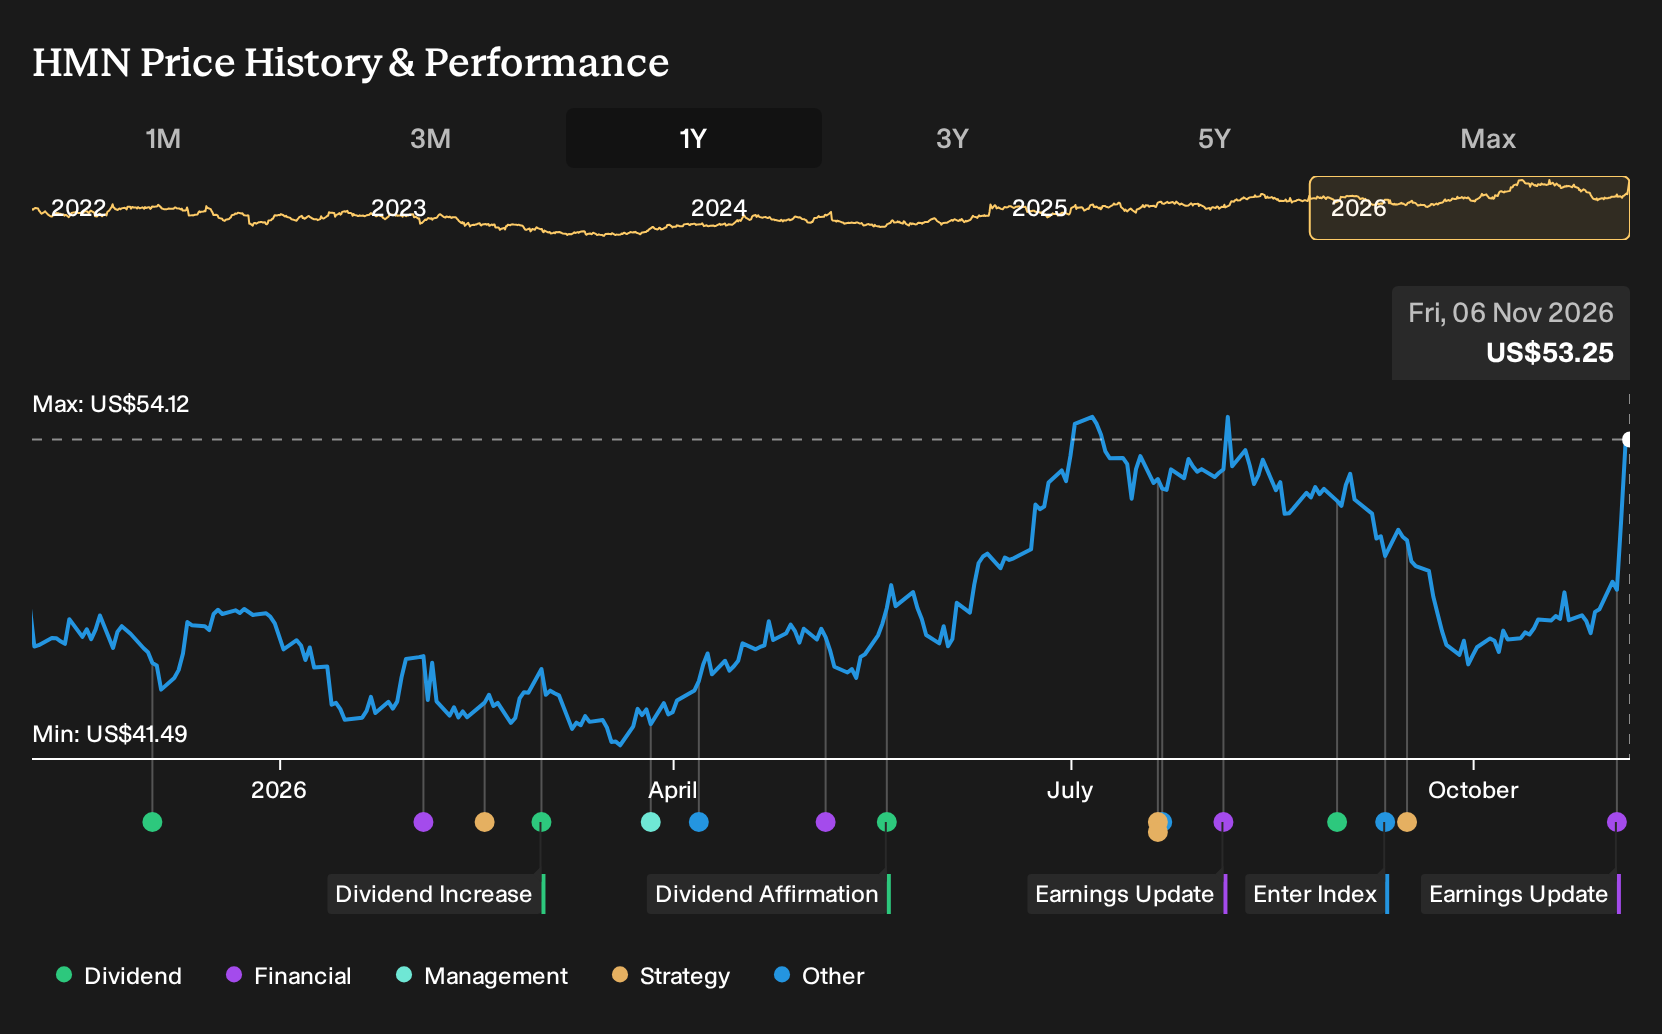
- Horace Mann Educators reported third quarter 2026 revenue of US$439.2 million and net income of US$58.5 million, with both basic and diluted earnings per share from continuing operations slightly above the prior year. The company also reported higher nine month figures compared with the same period in 2025.
- The company highlighted record quarterly earnings, raised its full year 2026 outlook and completed the Employee Services acquisition, adding nearly 1 million covered lives that management links to stronger underlying core earnings capacity.
- We will explore how Horace Mann Educators’ investment narrative evolves as record earnings and a higher outlook reshape expectations for core earnings.
Horace Mann Educators Investment Narrative Recap
To own Horace Mann Educators, you need to be comfortable with a focused bet on the educator market and a business model built around insurance, retirement and supplemental benefits for that group. The latest quarter showed record earnings and a higher full year 2026 outlook, which supports that thesis but does not remove concentration in K 12, an aging customer base or investment income pressure as key issues.
For now, the main short term swing factor is how consistently Horace Mann Educators can translate underwriting and investment results into repeatable core earnings while integrating new benefits platforms. The biggest risk still sits with education sector demand and any reset in alternative investment returns, and this earnings update does not materially change that balance.
The most relevant piece of news around this print is management’s raised full year 2026 outlook, which is tied to favorable underwriting and investment results plus the completed Employee Services acquisition. That acquisition brings nearly 1 million additional covered lives and expands relationships with employers. This directly links to the existing catalyst of building scale in supplemental and group benefits.
Investors now have a clearer operational test. Horace Mann Educators needs to show it can absorb Employee Services while keeping retention high, cross selling effectively and managing claim and benefit costs so that normalized core earnings stay close to the range management outlined. Any stumble in integrating new covered lives or weaker than expected investment income would quickly show up against that higher bar.
Horace Mann Educators’ current analyst narrative points to revenues of US$2.3b and earnings of US$226.1 million by 2029, based on an assumed 9.9% yearly revenue growth rate and a move in earnings from US$177.3 million today to that 2029 consensus. This represents an increase of about US$48.8 million over the period.
Uncover why Horace Mann Educators' fair value indicates a 6% potential upside to its current price that could narrow quickly.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Horace Mann Educators research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Horace Mann Educators. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Horace Mann Educators' overall financial health at a glance.
Looking For More Ideas Beyond Horace Mann Educators?
Horace Mann Educators may fit a specific brief for your portfolio, but your best edge often comes from comparing it with a wider set of opportunities using the Simply Wall St Screener.
- If you care most about resilient business models and steadier risk profiles, scan a curated 31 resilient stocks with low risk scores that can help you focus on companies with fewer obvious red flags.
- If income is a priority, check a hand picked 7 dividend fortresses that filters for higher yielding stocks where the payout is supported by underlying fundamentals.
- If balance sheet strength matters most to you, start with a list of solid balance sheet and fundamentals (25 results) to see which companies pair financial flexibility with solid operating profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com