
We're Not Very Worried About Greenlane Renewables' (TSE:GRN) Cash Burn Rate
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
So should Greenlane Renewables (TSE:GRN) shareholders be worried about its cash burn? In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
How Long Is Greenlane Renewables' Cash Runway?
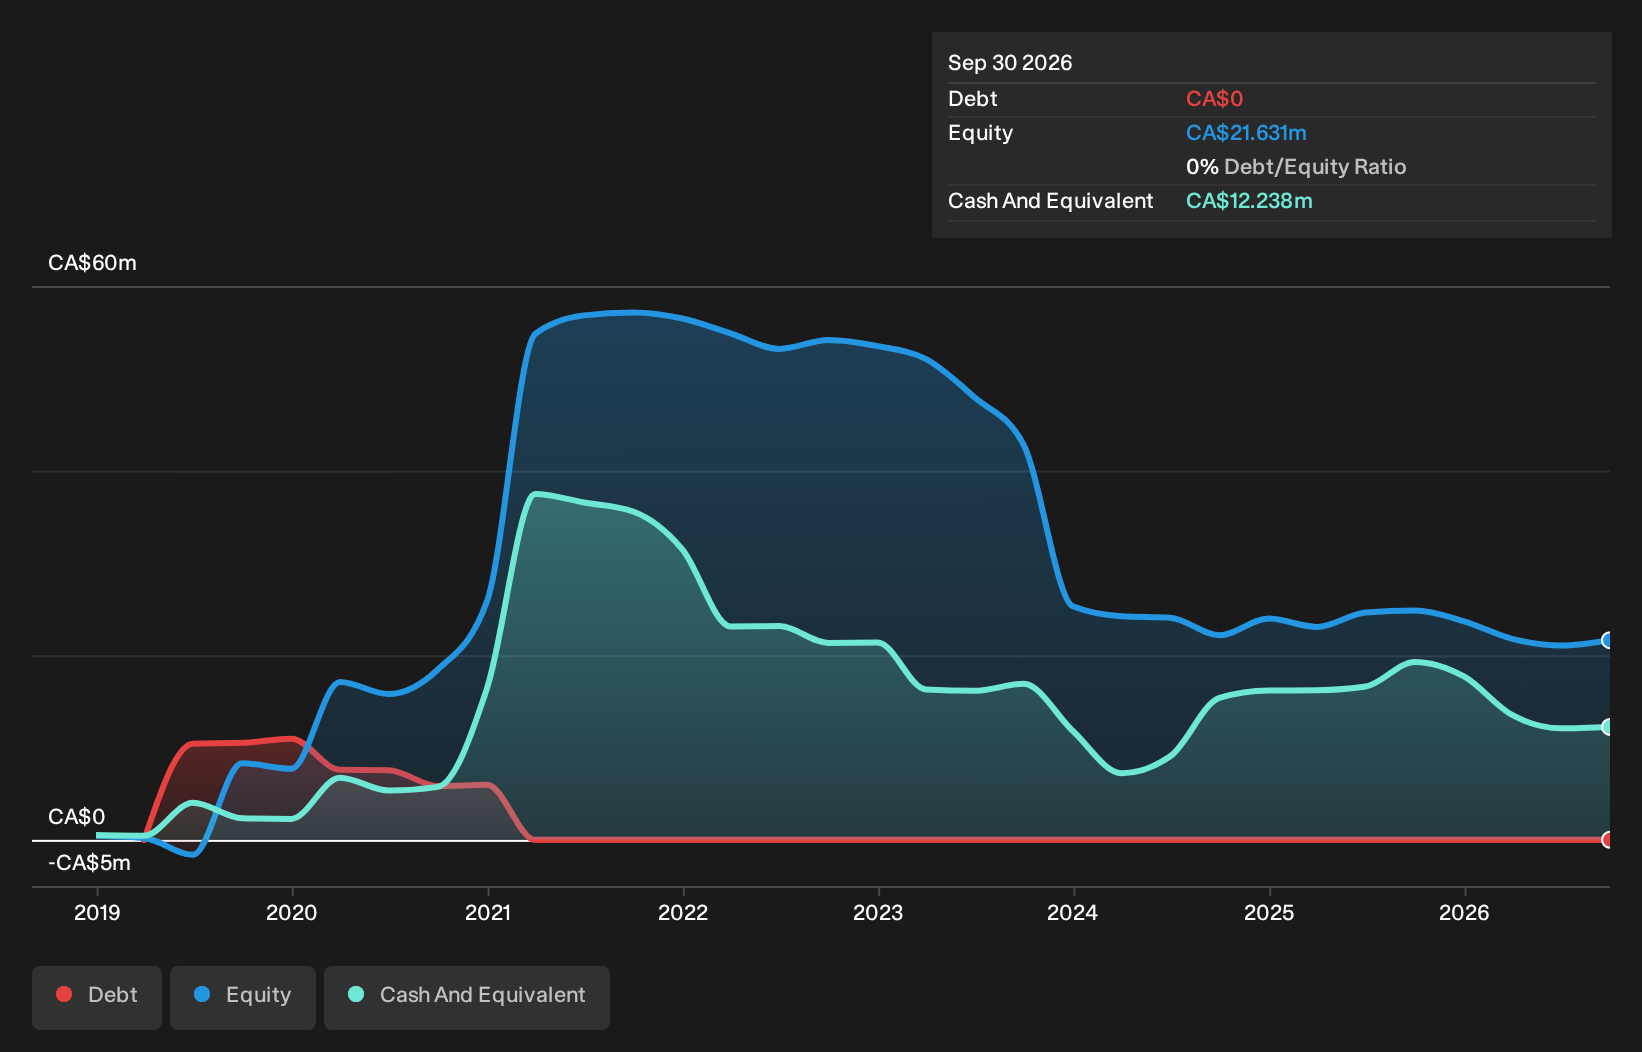
A company's cash runway is calculated by dividing its cash hoard by its cash burn. When Greenlane Renewables last reported its September 2026 balance sheet in November 2026, it had zero debt and cash worth CA$12m. Looking at the last year, the company burnt through CA$5.2m. So it had a cash runway of about 2.3 years from September 2026. Arguably, that's a prudent and sensible length of runway to have. The image below shows how its cash balance has been changing over the last few years.
Check out our latest analysis for Greenlane Renewables
Is Greenlane Renewables' Revenue Growing?
Given that Greenlane Renewables actually had positive free cash flow last year, before burning cash this year, we'll focus on its operating revenue to get a measure of the business trajectory. While it's not that amazing, we still think that the 4.4% increase in revenue from operations was a positive. Of course, we've only taken a quick look at the stock's growth metrics, here. This graph of historic earnings and revenue shows how Greenlane Renewables is building its business over time.
Can Greenlane Renewables Raise More Cash Easily?
Notwithstanding Greenlane Renewables' revenue growth, it is still important to consider how it could raise more money, if it needs to. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Since it has a market capitalisation of CA$32m, Greenlane Renewables' CA$5.2m in cash burn equates to about 16% of its market value. As a result, we'd venture that the company could raise more cash for growth without much trouble, albeit at the cost of some dilution.
Is Greenlane Renewables' Cash Burn A Worry?
Greenlane Renewables appears to be in pretty good health when it comes to its cash burn situation. Not only was its cash burn relative to its market cap quite good, but its cash runway was a real positive. Based on the factors mentioned in this article, we think its cash burn situation warrants some attention from shareholders, but we don't think they should be worried. Taking an in-depth view of risks, we've identified 1 warning sign for Greenlane Renewables that you should be aware of before investing.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.