
What McDonald's Stock Earnings Beat Means For Shareholders
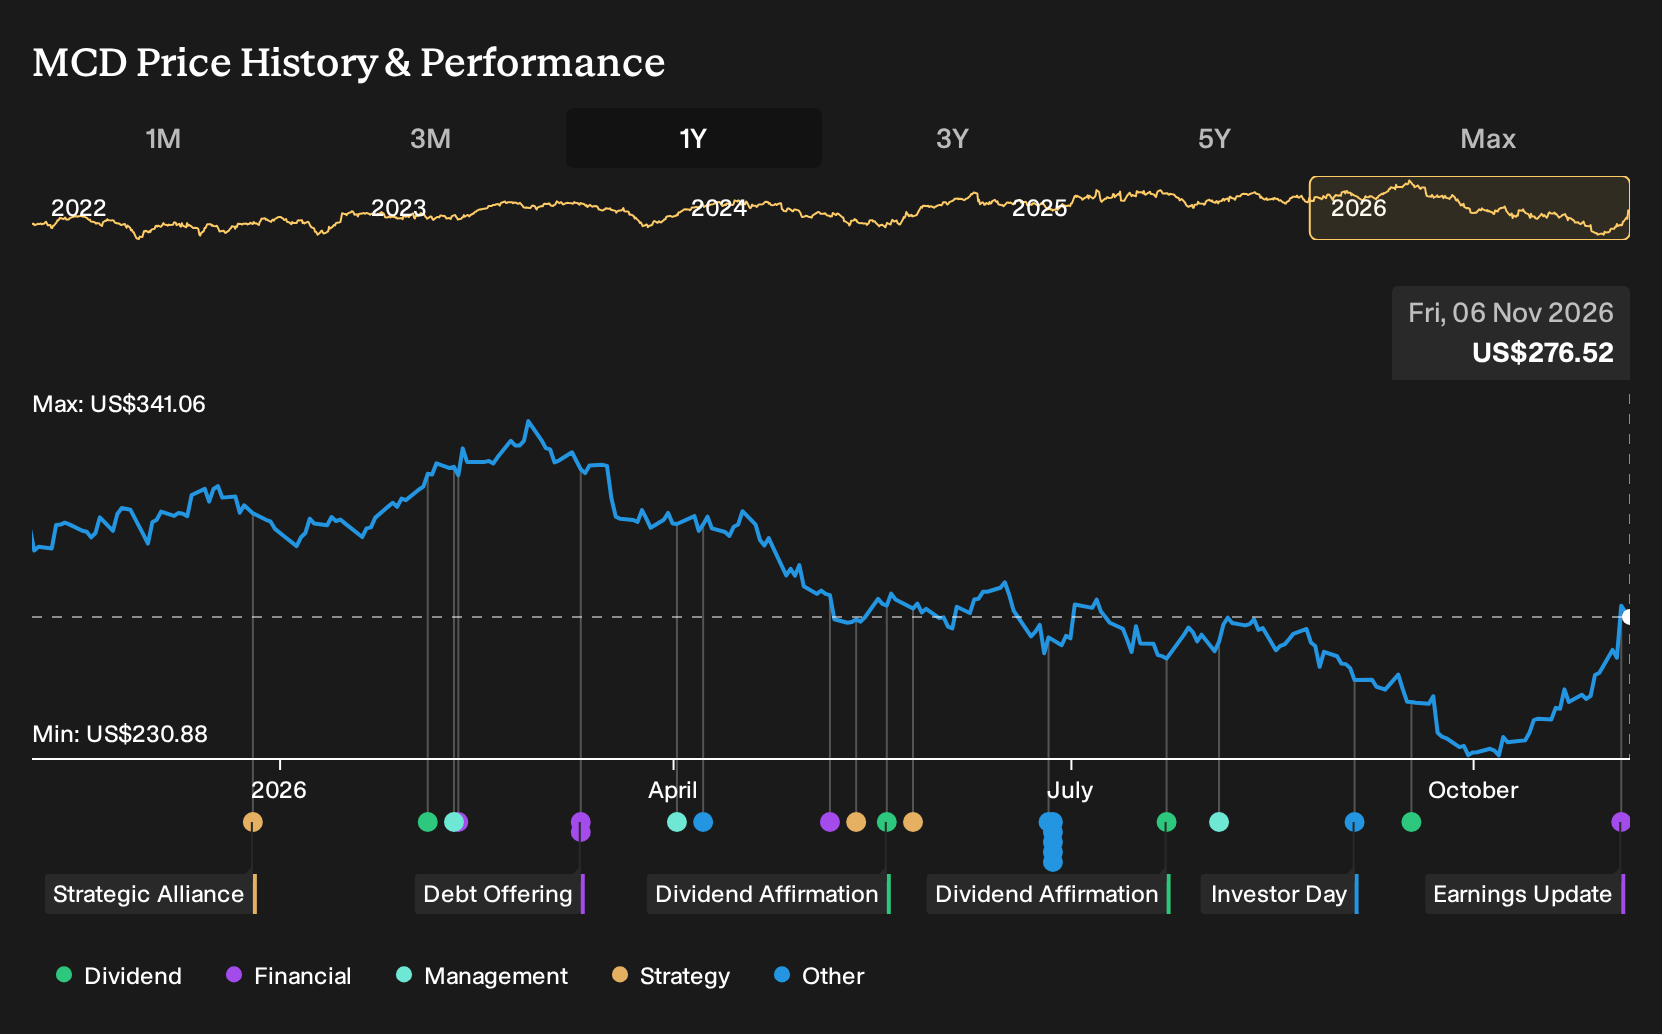
- McDonald's reported third quarter 2026 revenue of US$7,157 million and net income of US$2,486 million, with diluted EPS from continuing operations of US$3.51, and outlined value menu tests plus a planned national value platform launch in early 2027.
- Management is leaning on low priced bundles and broader digital offers to address slight U.S. comparable sales softness, while still funding restaurant expansion and AI driven efficiency projects.
- We will look at how McDonald's investment narrative evolves as strong earnings intersect with renewed focus on value driven U.S. traffic.
McDonald's Investment Narrative Recap
To own McDonald's today, you need to believe the global franchise and digital ecosystem can keep supporting steady earnings while U.S. traffic and value perception are worked through. The latest quarter backs that up at a high level, with revenue of US$7,157 million and net income of US$2,486 million despite softer U.S. comparable sales.
The near term swing factor is whether the value reset in the U.S. stabilises guest counts without putting too much pressure on franchisee economics. The biggest operational risk is that low income traffic remains weak and value execution stays patchy, which could keep U.S. same store sales and restaurant margins under strain.
The most relevant fresh data point is the eight week test of low priced bundles and revised value menus at about 1,900 U.S. restaurants, with a national value platform planned for early 2027. This is where McDonald's is trying to reconnect with price sensitive customers after a 0.2% decline in U.S. comparable sales in Q3.
For you as a shareholder, this experiment is the clearest operational catalyst to watch. If the bundles prove workable for franchisees and support traffic, that would support the broader digital and loyalty strategy. If execution misfires, it could amplify existing risks around U.S. value positioning, input cost pressure, and franchise cash flow.
What Analysts Are Building Into The McDonald's Story
Analysts are effectively treating McDonald's as a relatively steady top line vehicle. They expect revenue to stay broadly flat over the next three years while profit margins gradually lift from 31.7% today to 35.8% as cost initiatives, refranchising and digital scale feed through.
The consensus view centers on earnings climbing from US$8.8b today to US$10.2b by 2029, with some outliers looking for as much as US$11.5b. That move from US$8.8b to US$10.2b implies roughly a 16% increase in profit dollars over the period, even without much help from headline sales growth.
This earnings trajectory sits behind the current analyst playbook on capital returns. Forecasts assume modest share count reduction of about 0.63% per year for the next three years, which can quietly lift earnings per share, while the business keeps funding restaurant growth, remodels and digital upgrades from its existing cash generation.
Valuation expectations build on the same spine. To line up with the consensus price target, you would need to assume McDonald's can reach about US$28.5b in revenue and US$10.2b in earnings by 2029, and that investors are willing to value those profits at roughly 26.3x P/E, compared with 18.7x today and 18.9x for the wider U.S. hospitality peer group.
Put simply, the story analysts have sketched relies less on rapid sales expansion and more on a thicker margin profile, a slightly leaner share count and a higher earnings multiple, layered on top of the value menu and digital engagement plans already in motion.
McDonald's narrative projects US$28.5b revenue and US$10.2b earnings by 2029. This assumes fairly flat yearly revenue growth and an earnings increase of about US$1.4b from current earnings of US$8.8b.
Uncover why McDonald's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle to watch is the AI pricing and data risk. The most bearish analysts were pencilling in 2029 revenue of about US$24.2b and earnings of US$9.1b for McDonald's before this latest quarter, even as they still assumed higher margins. You are effectively weighing a solid Q3 print against concerns that regulatory or legal pushback on AI tools could reshape those forecasts. Views differ sharply, so it can be useful to explore several scenarios and then decide how this new information fits your own thesis.
Explore 5 other McDonald's fair value estimates, including one that suggests there may be as much as 18% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your McDonald's research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for McDonald's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McDonald's overall financial health at a glance.
Looking For More Investment Ideas Beyond McDonald's?
If the McDonald's story has you thinking about what else might fit your portfolio, it can help to scan for other businesses with the specific traits you care about, then compare their fundamentals side by side.
- For investors who want yield backed by staying power rather than hope, start with a curated 7 dividend fortresses that already clears a 5%+ yield hurdle.
- If capital preservation ranks high on your list, narrow the field to a 31 resilient stocks with low risk scores that screens for resilience instead of speculation.
- When you want quality companies that the market may not be paying full attention to yet, turn to a 19 high quality undiscovered gems and see which overlooked candidates meet your standards.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com