
RB Global (RBA) Could Be 27% Undervalued On Strong Earnings And Higher Guidance
RB Global (RBA) is back on investors’ radar after reporting a 31% rise in second quarter 2026 net income and raising its full year gross transaction value growth guidance to a range of 9% to 11%.
At a share price of US$93.52, RB Global has seen a 7 day share price return of 4.27% and a 30 day share price gain of 8.95%. However, year to date the share price is still down 9.46%, while the 3 year total shareholder return of 61.75% and 5 year total shareholder return of 44.79% point to stronger long run momentum than the recent 1 year total shareholder return decline of 5.66% might suggest.
Scan RB Global’s peers riding similar transaction and marketplace themes by reviewing the hand picked 19 high quality undiscovered gems that may be flying under most investors’ radar.
After a sharp rebound on strong Q2 guidance, RB Global now sits closer to recent highs than lows. Is it wiser to step in at US$93.52, or to wait for a cheaper entry before beginning the valuation work?
Most Popular Narrative: 27% Undervalued
RB Global’s most followed valuation story points to a fair value of $128.64 against the latest close at $93.52, so the gap between price and narrative value is wide enough that it becomes the central question for anyone running the numbers.
Expansion from heavy equipment into sector specific marketplaces such as automotive salvage, government surplus and now agriculture through BigIron increases the range of assets on RB Global platforms and can support higher GTV and service revenue over time as these verticals scale.
Global footprint expansion through contracts in markets such as Australia, the UK and Central America, together with a growing agriculture presence from BigIron, broadens the buyer and seller base and can support higher international GTV contribution and operating leverage.
See why 4 investors see RB Global as 27% undervalued.
Result: Fair Value of $128.64 (UNDERVALUED)
Still, the RB Global story can be shaken if service fee take rates keep slipping, or if heavier capex spending drags on free cash flow and buybacks.
Find out about the key risks to this RB Global narrative.
Another View: RB Global Looks Expensive On Earnings
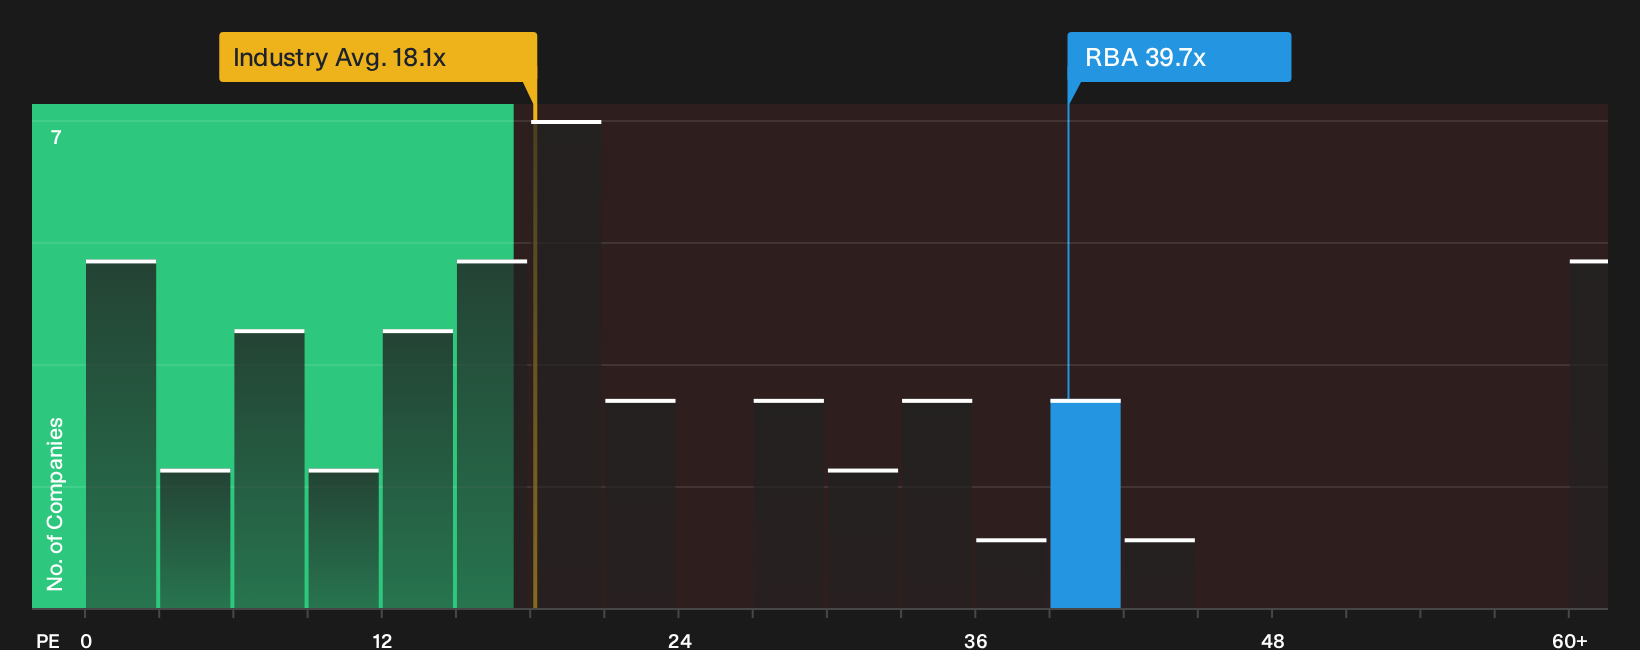
While the main RB Global story leans on a fair value of $128.64, the current P/E of 39.7x tells a very different story. That multiple is far above the US Commercial Services industry at 18.4x, the peer average at 29.4x, and even the fair ratio of 29.1x that the market could move toward. If sentiment cools, would valuation pressure bite before the growth narrative has time to play out?
To see what the numbers say about this price in more detail, review the See what the numbers say about this price — find out in our valuation breakdown..
For a visual sense of how that P/E stacks up against the sector, take a look at the latest chart,
Next Steps
Mixed messages in RB Global’s story so far. Act while the data is still fresh and weigh both sides of the ledger with the 5 key rewards and 1 important warning sign.
Looking for more RB Global style investment ideas?
If RB Global has sharpened your focus on quality, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh opportunities that fit your style.
- Target quality at a discount by reviewing the hand picked 38 high quality undervalued stocks that match strong fundamentals with appealing prices.
- Dial down portfolio stress by hunting through the 31 resilient stocks with low risk scores that aim for resilient balance sheets and steadier return profiles.
- Fortify your income stream by scanning the yield focused 7 dividend fortresses that pair regular payouts with business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com