
Markel Group (MKL) Earnings Weakened, Does The Stock Look Fairly Valued?
Why Markel Group’s latest earnings are drawing attention
Markel Group (MKL) just posted third quarter results that point to weaker profitability, with net income dropping to US$259.26 million and diluted earnings per share falling to US$18.15 compared with the same period last year.
Despite the weaker earnings, Markel Group’s recent trading tells a mixed story. The share price is up 10.13% over the past month and 5.38% over 90 days, yet the year to date share price return is down 8.98% and the 1 year total shareholder return is down 4.82%. The 3 and 5 year total shareholder returns of 44.73% and 50.34% hint at stronger long run performance than the latest quarter suggests.
Compare how other insurers and diversified financial groups are reacting to similar profitability pressures by reviewing our hand picked 31 resilient stocks with low risk scores together with Markel Group’s latest quarter.
Markel Group’s share price has bounced even as earnings softened, which leaves a simple tension. Are investors reassessing the underlying business, or just swinging with sentiment as the valuation case gets picked apart next?
Most Popular Narrative: 1% Undervalued
Markel Group’s most followed narrative puts fair value at $1,956.33, just above the last close of $1,939.04, which frames the recent share price move against only a small implied discount.
The continued expansion of Markel’s non insurance operations, including Industrial, Financial and Consumer and Other segments that generated a combined US$1.8b of adjusted operating income in 2025 and are still deploying capital into bolt on deals and ownership increases, provides additional cash flow streams that can smooth consolidated earnings and support future growth in group level operating income.
See why 21 investors see Markel Group as 1% undervalued.
Result: Fair Value of $1,956.33 (UNDERVALUED)
Still, Markel Group’s story can be knocked off course if legacy reserve issues deepen or the broad reorganization fails to deliver tighter underwriting control.
Find out about the key risks to this Markel Group narrative.
Another View: What Markel Group’s P/E Is Telling You
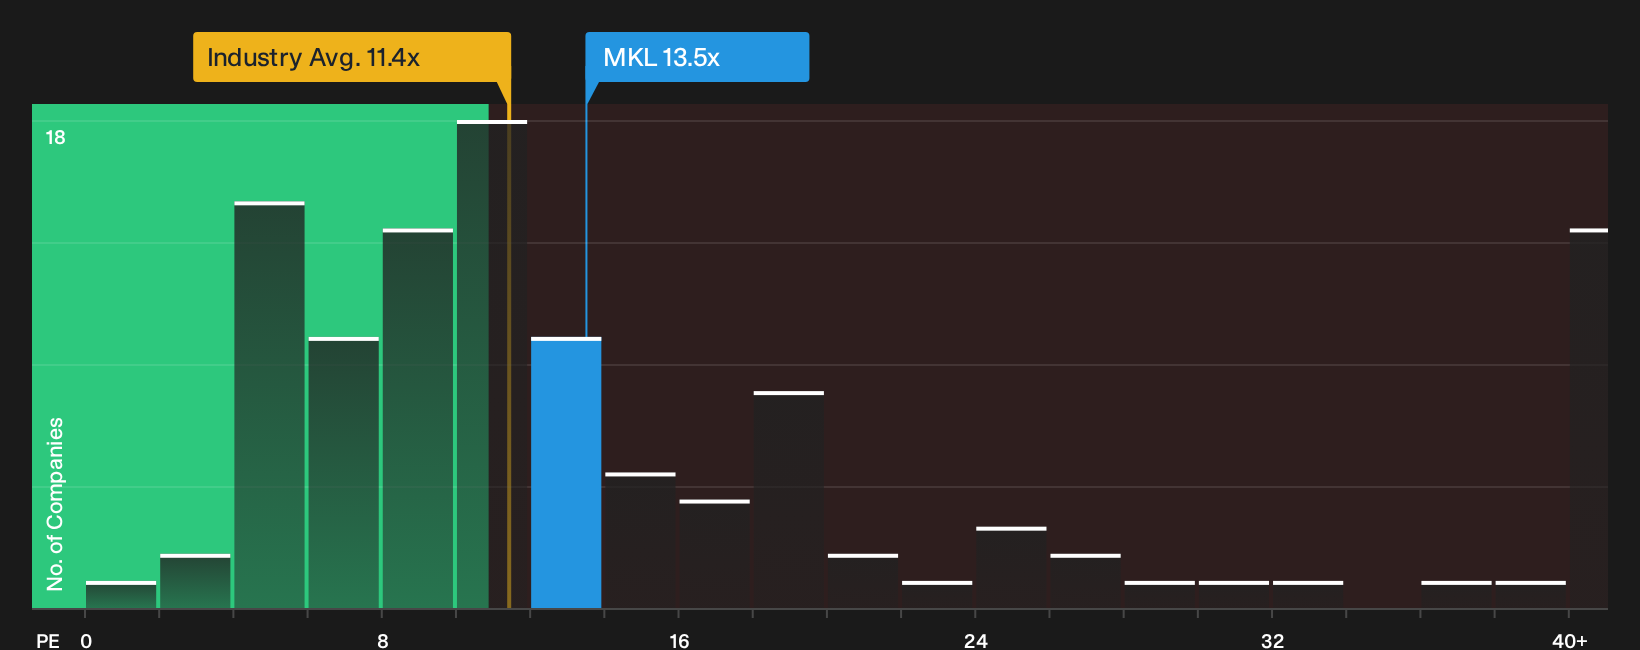
On analyst fair value, Markel Group looks only slightly undervalued. On simple earnings multiples, the picture is less forgiving. The current P/E of 13.5x sits above the US Insurance industry at 11.4x, peers at 12.4x, and an estimated fair ratio of 11.3x, which points to valuation risk if sentiment cools.
That kind of premium can sometimes reflect confidence in Markel Group’s earnings quality and diversified engines. However, it also leaves less room for error if profitability disappoints again. The key question for investors is whether that extra multiple is really being earned by future execution.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around Markel Group leaves you undecided, consider taking prompt action to compare the numbers with your own expectations. For a clearer view of the factors driving current optimism, review the 1 key reward.
Looking for more Markel Group sized investment ideas?
If you stop with Markel Group, you risk missing other opportunities that fit your style, so give yourself options and line up a broader watchlist now.
- Target resilient balance sheets and steady fundamentals through a curated list of solid balance sheet and fundamentals (25 results) that helps you focus on financially robust businesses instead of guessing where risk might be hiding.
- Hunt for potential value opportunities by scanning the 38 high quality undervalued stocks and quickly see which stocks line up with strong quality checks as well as attractive prices.
- Prioritize income and staying power by reviewing the 7 dividend fortresses so you do not overlook companies combining higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com