
Innovex International (INVX) After Q3 Growth And Fresh Guidance Is It A Buying Opportunity
Innovex International (INVX) is back in focus after reporting Q3 2026 revenue of US$265.05 million, 10% higher year over year, along with fresh Q4 guidance of US$260 million to US$270 million.
The latest guidance and contract wins land in a mixed price backdrop for Innovex International. The share price return is up 10.32% year to date at US$25.13, yet recent momentum has cooled, with the 30 day share price return down 10.44% and the 1 year total shareholder return at 25.46%, signalling longer term gains despite shorter term weakness.
Scan how Innovex International stacks up against other oilfield equipment stocks by zeroing in on our hand picked 33 best rare earth metal stocks for potential next reads.
Recent weakness in Innovex International despite higher Q3 revenue and fresh contract wins leaves a simple puzzle. Are investors reassessing the business itself, or has sentiment just swung too far and set up a value gap to test?
Most Popular Narrative: 7% Undervalued
On the most followed narrative, Innovex International screens slightly cheap, with a Fair Value of $27.00 against the last close at $25.13. This puts execution on margins and offshore timing under the microscope.
Although Innovex International is broadening its Subsea presence through recent project awards in Asia and an alliance driven wellhead order in Southeast Asia, the business still depends on project timing in longer cycle offshore markets. This can restrict the pace at which Subsea revenue translates into steadier earnings.
See why 2 investors see Innovex International as 7% undervalued.
Result: Fair Value of $27.00 (UNDERVALUED)
Still, that offshore and Subsea exposure leaves Innovex International vulnerable to project delays, while the US$49 million legal accrual underlines legal and cash flow risk that could challenge this underpriced thesis.
Find out about the key risks to this Innovex International narrative.
Another View: What P/E Says About Innovex International
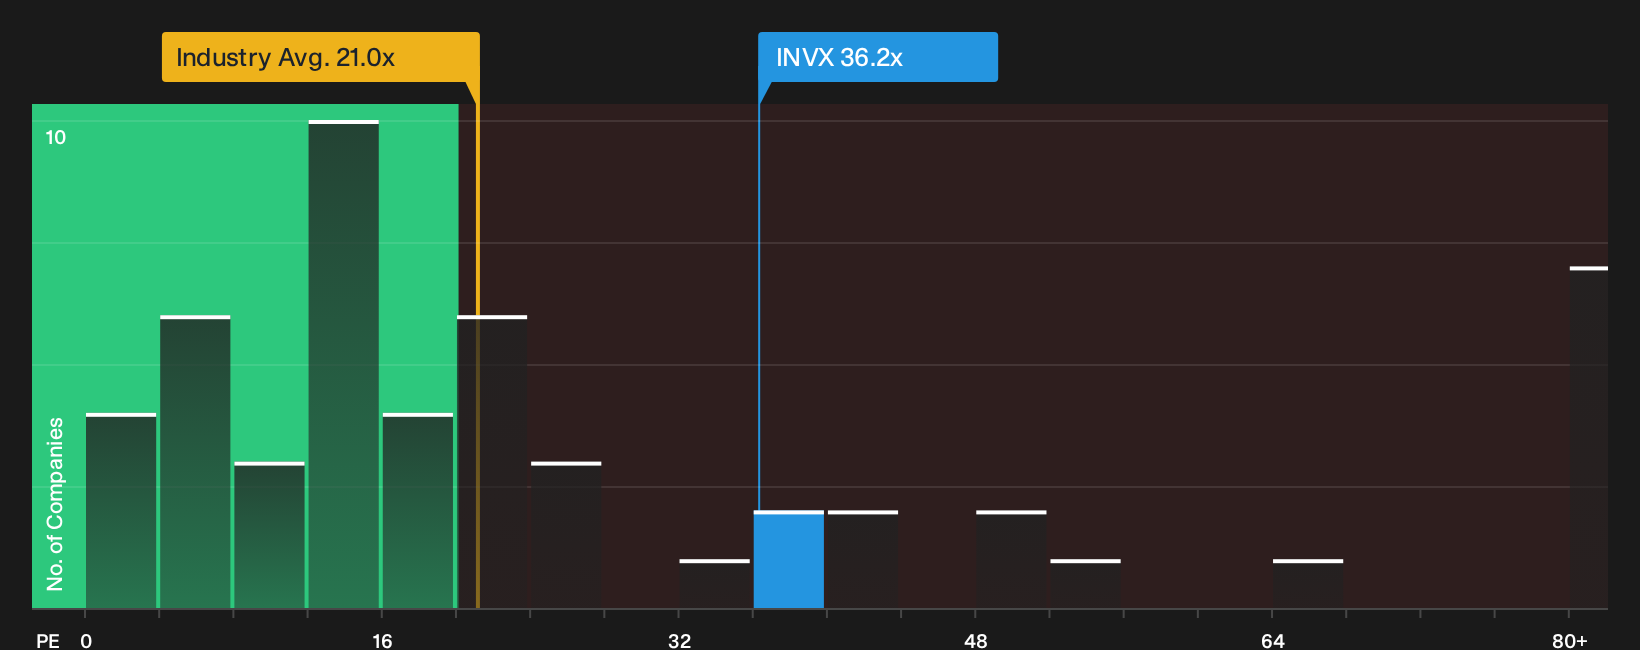
The first fair value story for Innovex International leans on discounted future cash flows and suggests the stock is trading at a steep 63.8% discount to that model. The picture changes once you look at the current P/E of 36.2x.
Against the US Energy Services industry average of 21x and an estimated fair ratio of 29.9x, that 36.2x earnings multiple looks rich. It points to a scenario where the share price already bakes in a lot of optimism, which could leave less room for error if margins or growth fall short. Is this a valuation gap worth embracing, or a risk premium investors should treat with caution?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Innovex International so far, or a clear signal waiting to be tested. Act while the data is fresh, compare the upside and the downside, then weigh up the 3 key rewards and 2 important warning signs.
Looking for more Innovex International investment ideas?
If Innovex International has your attention, do not stop here. Broaden your watchlist with structured ideas that help you compare quality, value, and resilience across the market.
- Chase potential mispricing by scanning our hand picked 38 high quality undervalued stocks that combine solid fundamentals with price tags that may not fully reflect their profiles.
- Strengthen your income layer by reviewing the 7 dividend fortresses that focus on companies offering higher yields with an emphasis on consistency.
- Tighten your risk profile by filtering for the 31 resilient stocks with low risk scores so you can balance opportunity with a focus on steadier balance sheets and earnings patterns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com