
Is 10x Genomics (TXG) Cheap As It Lifts Full Year Guidance?
10x Genomics (TXG) reported a modest third quarter revenue increase to US$150.67 million alongside a narrower net loss, and raised its full-year 2026 sales guidance to a range of US$625 million to US$635 million.
The latest guidance increase and ongoing Atera rollout come after a sharp run, with 10x Genomics posting a year to date share price return of 256.68% and a 1 year total shareholder return of 288.72%. However, the 30 day share price return of 26.50% and 7 day share price return of 15.45% indicate that recent momentum has cooled.
Scan how 10x Genomics compares with other high-growth stories by reviewing our curated list of 19 high quality undiscovered gems in similar cutting edge fields.
After a surge like 10x Genomics has seen, a 15% pullback in a week and a share price below analyst targets creates a clear tension. Is that a reasonable safety buffer, or is it a warning sign the market is respecting?
Most Popular Narrative: 24% Undervalued
Based on the most followed narrative, 10x Genomics has an implied fair value of about $77.50 compared with the last close at $59.28, which frames recent share price volatility against a longer term return-on-investment thesis built on genomics and AI use cases.
Recent and upcoming product launches, including Flex v2 (targeting higher throughput, lower costs, and AI integration), Visium HD extensions, and Xenium RNA plus protein, are expanding the range of applications and reinforcing 10x's leadership in advanced genomics tools, expected to drive both top-line growth and sustain premium pricing over time.
See why 30 investors see 10x Genomics as 24% undervalued.
Result: Fair Value of $77.50 (UNDERVALUED)
Still, shrinking pricing power, ongoing losses, and pressure on research budgets could quickly challenge the 10x Genomics upside story that investors are leaning on.
Find out about the key risks to this 10x Genomics narrative.
Another View: What Multiples Say About 10x Genomics
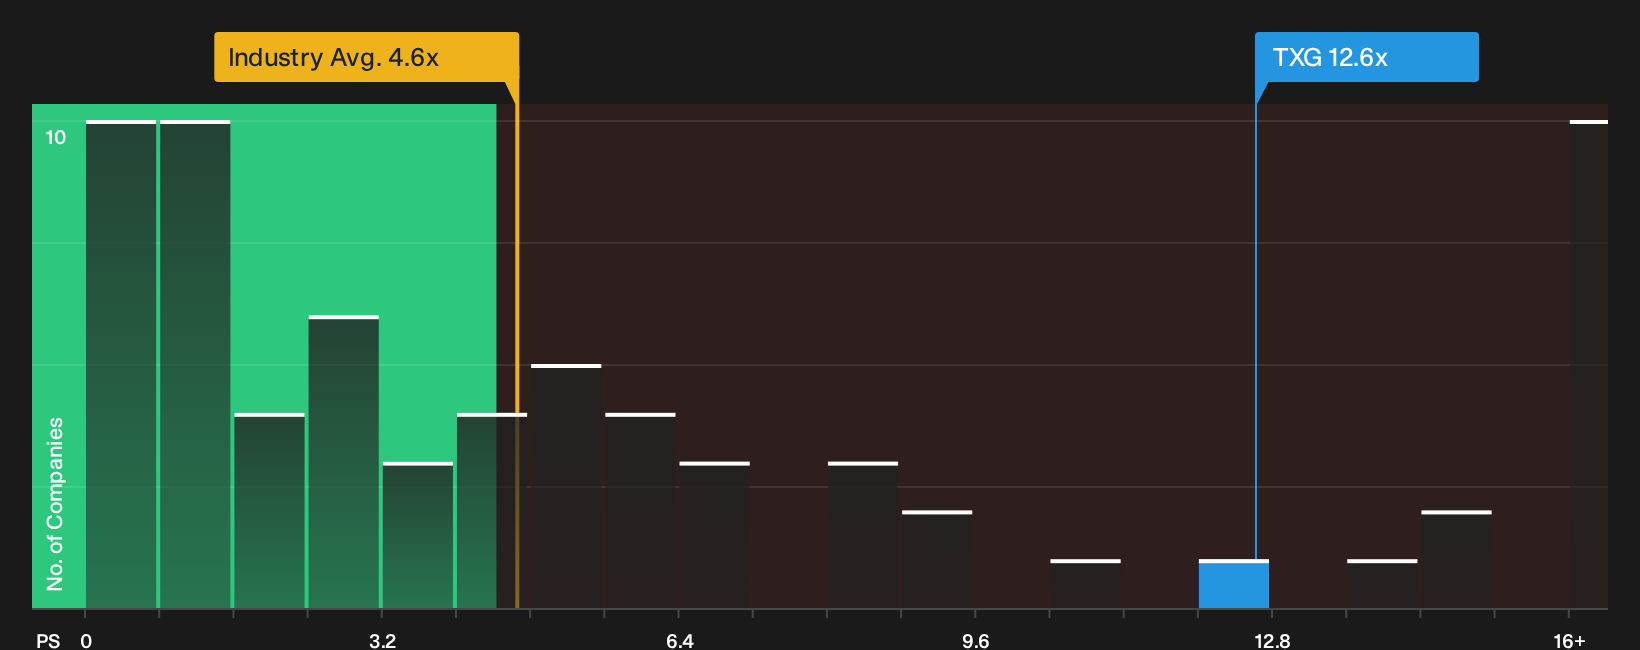
The SWS fair value narrative presents 10x Genomics as 24% undervalued at $59.28. The P/S multiple tells a very different story. TXG trades at 12.6x sales, while the US Life Sciences industry is around 4.6x and peers near 3.3x, with a fair ratio of 6.6x suggesting valuation risk rather than a clear bargain.
If the stock already reflects a much richer sales multiple than both sector and peer averages, the key question is how comfortable an investor is with paying that premium for a future growth story in practice.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around 10x Genomics can be confusing. Move quickly, review the underlying data, and weigh both sides of the story using 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond 10x Genomics?
Do not stop with 10x Genomics. The next opportunity often sits where fewer investors are looking, and that is where careful research can really pay off.
- Target stronger quality at lower prices by reviewing the 38 high quality undervalued stocks that combine solid fundamentals with depressed market expectations.
- Prioritise resilience by scanning the 31 resilient stocks with low risk scores that pair steadier business profiles with more measured volatility.
- Strengthen your core holdings by checking the list of solid balance sheet and fundamentals (25 results) that focus on companies with more robust financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com