
AtriCure (ATRC) Stock Looks Fully Valued On Its 83% Run
AtriCure has delivered a sharp share price climb over the past year, which puts fresh attention on a simple question for you as an investor: Is the current valuation, at around US$58 per share, adequately grounded in what the business is generating in sales?
- The stock has gained 82.7% over the past year, which raises the stakes on whether that move is fully supported by the company’s revenue base.
- Recent financial updates point to higher revenue and improved profitability, yet a softer outlook for future sales growth can influence how much investors are willing to pay for each dollar of turnover.
- The analysts covering AtriCure have run their own numbers. See what analysts think AtriCure's shares could be worth.
The issue now is whether AtriCure’s current share price can be justified by its sales when measured against the Fair Ratio benchmark.
If you want to test the same sales based valuation question beyond AtriCure, it helps to compare it with a wider group using the 38 high quality undervalued stocks
Has AtriCure Run Too Far on Sales?
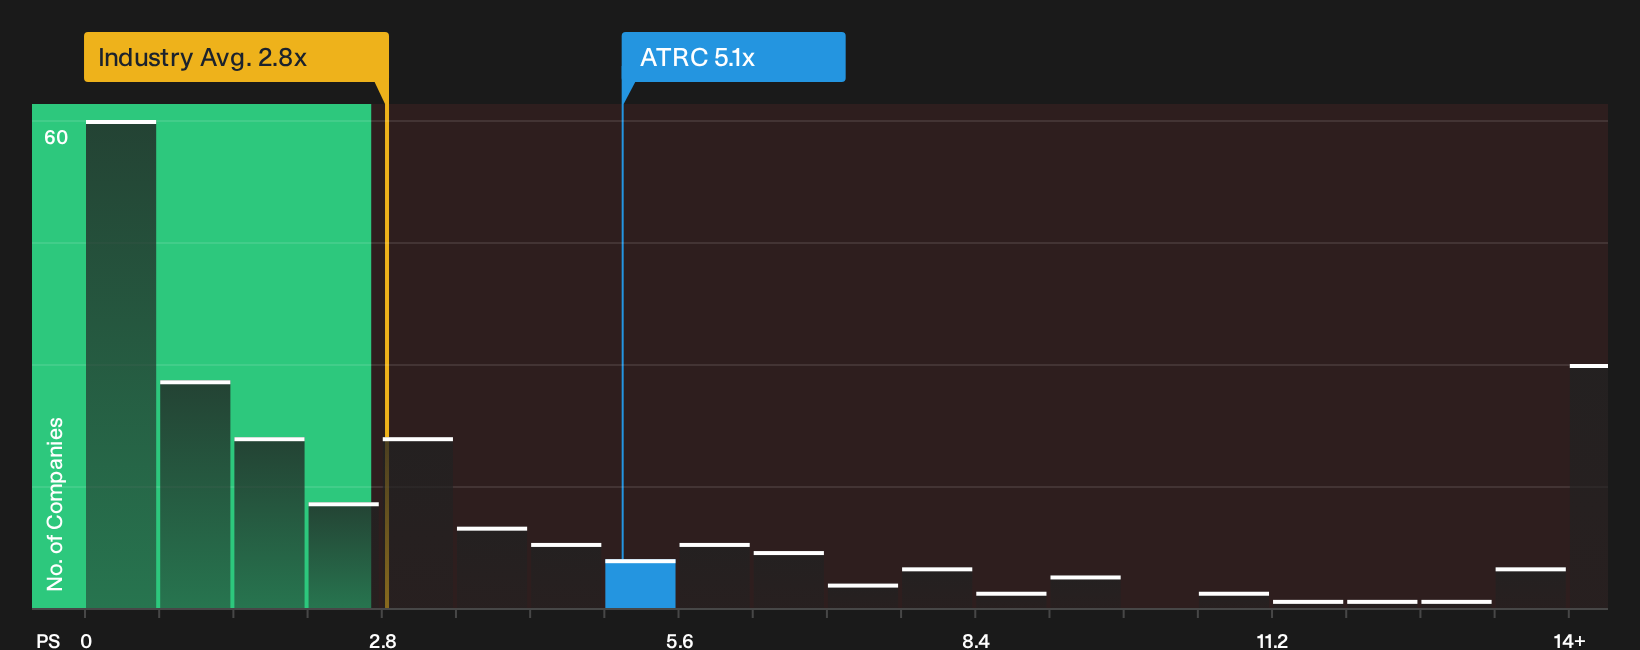
AtriCure is best viewed through its P/S ratio because the business is still building its earnings base while revenue remains the cleaner anchor. At around 5.1x P/S, the stock trades above the Medical Equipment group on roughly 2.8x and also above the peer pack near 4.6x. The Fair Ratio model, which blends in AtriCure’s growth profile, margins, size and risk, points to a lower multiple than where the shares change hands today. As a result, the current tag leans toward an overvalued reading on this lens.
Despite the mixed 2026 guidance, with revenue expectations pulled down after a strong third quarter, the market is still paying a richer price for each dollar of AtriCure’s sales than both the sector and similar companies. That sets a higher bar for future execution and for how investors view any further shifts in the revenue outlook. Explore the numbers behind AtriCure's P/S valuation.
The AtriCure Narrative: What Would Justify Today's Price?
AtriCure’s Simply Wall St Narratives take the valuation puzzle a step further by setting out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s level, and they sit on the Community page. Where a P/S ratio or Fair Ratio model gives one output, these scenarios unpack the future that number rests on so you can track whether it still stacks up over time.
Community views on AtriCure are split between those who see more upside in the pipeline and margins and those who think expectations already look full.
Bull case: 14% undervalued
"Faster than initially planned enrollment in the 960 patient BoxX-NoAF trial, together with the large LeAAPS dataset, can give AtriCure a differentiated evidence package that supports procedure volume growth and potentially a higher mix of premium products..."
Discover why this Narrative puts AtriCure at 14% undervalued.
Bear case: roughly fairly valued
"The current valuation suggests that the share price already reflects continued double-digit revenue growth, further margin expansion toward higher medtech levels, and successful execution of the long-term Vision 2030..."
Explore why this Narrative puts AtriCure at roughly fairly valued.
For AtriCure, price is just the starting point
Before treating AtriCure’s share price as the full story, it helps to know that Simply Wall St’s broader checks have flagged specific risk signals that deserve a closer look beside the valuation. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com