
GeneDx Holdings (WGS) Shares Dropped, So What Is Driving Attention Now?
What the Mirum partnership means for GeneDx investors
GeneDx Holdings (WGS) has moved to deepen its rare disease footprint through a new collaboration with Mirum Pharmaceuticals that offers fully sponsored exome testing across three targeted patient programs.
The initiative focuses on cholestasis, early onset cataracts, and peroxisomal biogenesis disorder Zellweger spectrum disorders, aiming to reduce financial barriers for patients while potentially broadening adoption of GeneDx ExomeDx testing among clinicians.
In contrast to this Mirum agreement, GeneDx Holdings has come under pressure, with the share price down 19.9% over the past 90 days and the year-to-date share price return declining 52.9%. The three-year total shareholder return is extremely high despite a 55.4% total shareholder loss over the past year.
Scan beyond GeneDx Holdings and line up other rare disease and healthcare AI plays with the curated 35 healthcare AI stocks that are already catching attention.
After a steep year-to-date slide in GeneDx Holdings despite a very strong three-year return, the market has already repriced a lot. The key issue now is whether most of the upside is spent or still ahead at today’s valuation.
Most Popular Narrative: 33% Undervalued
Against the last close of $62.37, the most followed narrative for GeneDx Holdings points to a fair value of $93.50 that leans heavily on payer coverage, rare disease data and long read genome plans.
Growing payer reimbursement support, highlighted by commercial genome coverage moving from about 47% to approximately 87% of commercial lives and exome coverage of about 98%, leaves a wide gap to GeneDx’s 70% collection rate goal. This creates room for higher realized reimbursement and improved net margins if outpatient collection rates rise from current levels near 32%.
See why 25 investors see GeneDx Holdings as 33% undervalued.
Result: Fair Value of $93.50 (UNDERVALUED)
Still, the GeneDx Holdings story depends heavily on converting payer coverage into higher collection rates and on managing the fallout from the Fabric Genomics impairment and related class actions.
Find out about the key risks to this GeneDx Holdings narrative.
Another View on GeneDx Holdings Valuation
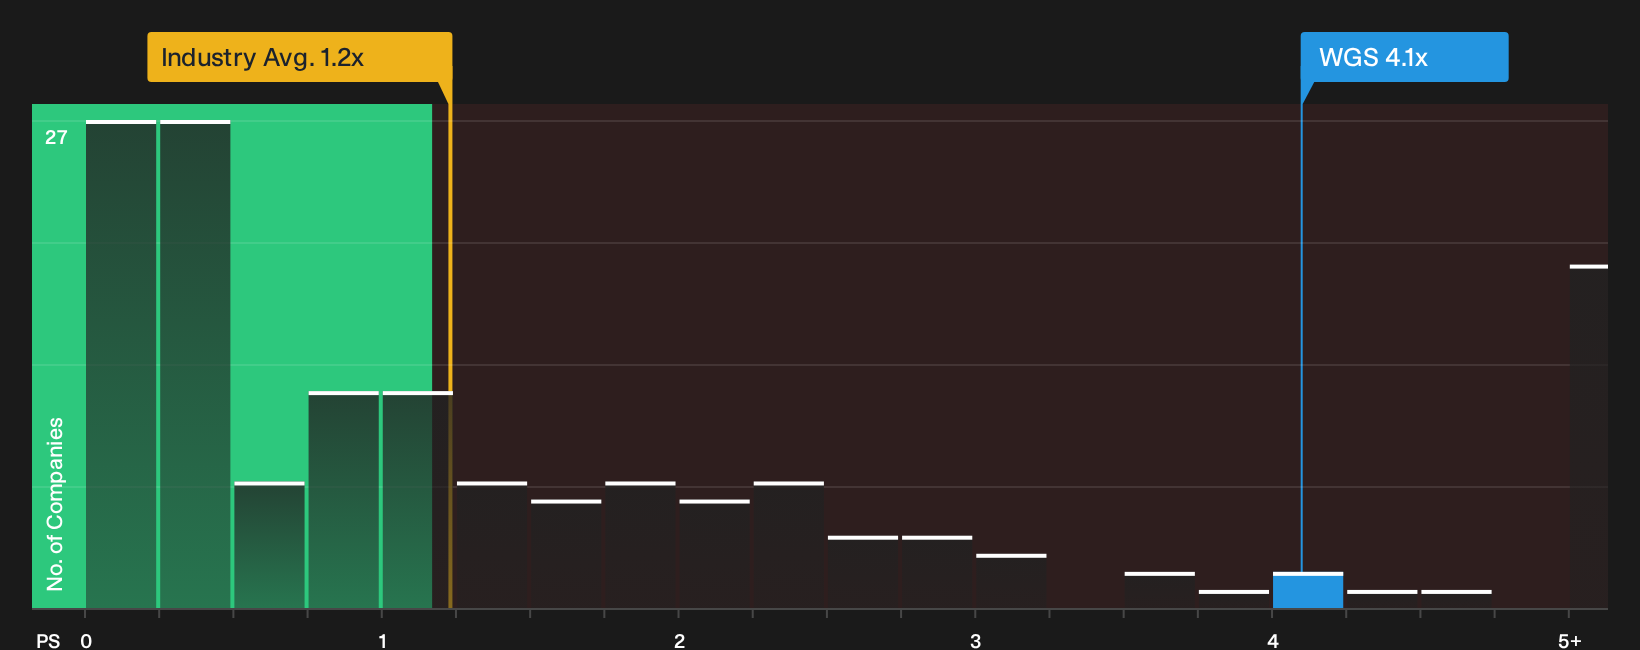
Analysts lean on future earnings and price targets for GeneDx Holdings, yet the current P/S of 4.1x tells a different story. It is higher than the US Healthcare industry at 1.2x, above peers at 0.8x, and slightly above a fair ratio of 3.9x, which points to valuation risk if sentiment cools.
For a closer look at how this compares with other approaches, and what the numbers imply if the market drifts toward that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around GeneDx Holdings can feel confusing. Move fast, look through the full risk and reward breakdown, and weigh it against your own thesis with 3 key rewards and 1 important warning sign
Looking for more GeneDx investment ideas?
If GeneDx Holdings has sharpened your thinking, broaden your opportunity set now. Fresh ideas often appear where fewer investors are already looking.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (25 results) and see which businesses pair sturdy finances with room for a stronger market story.
- Hunt for potential mispricings by running through a curated 38 high quality undervalued stocks that filters for quality alongside attractive pricing signals.
- Prioritise resilience and sleep-better-at-night positions by zeroing in on a 31 resilient stocks with low risk scores that screens for durable fundamentals with fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com