
Shell Heads These 3 British Undervalued Stocks To Watch
Rising mentions of inflation on S&P 500 earnings calls have pulled investors back to basics. Cash generation and sensible pricing power suddenly matter a lot more than exciting stories. That is where undervalued UK companies with solid projected cash flows come in, especially when share prices sit below independently assessed fair value. This article highlights three stocks that screen well on cash flow value grounds and explains what sets each apart.
The three stocks that follow are just a snapshot of the idea, with the wider screen surfacing 20 more UK listed businesses with similar cash flow profiles and valuation gaps that are not covered here. To see the full universe and move from curiosity to your own short list, head straight to the Undervalued Stocks Based On Cash Flows screener to identify, filter and analyze candidates that fit your highest conviction criteria.
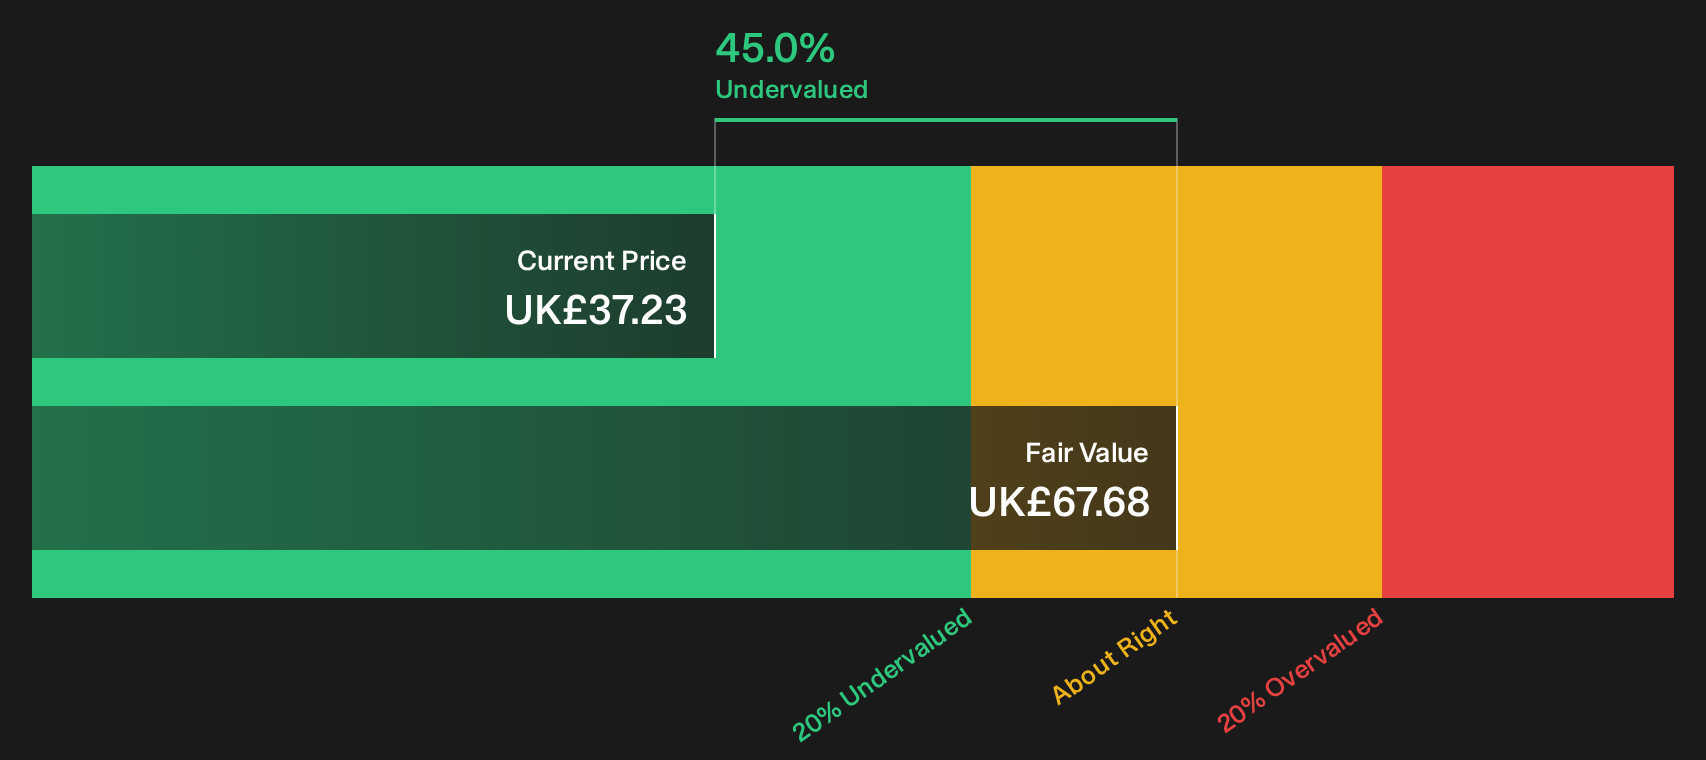
Shell (LSE:SHEL)
Overview: Shell is a global energy group that produces and trades oil, gas, chemicals and low carbon solutions, including LNG, biofuels and power.
Operations: Shell generates most of its revenue from Marketing at US$146.2b and Chemicals and Products at US$142.9b, with Renewables and Energy Solutions contributing US$45.5b.
Market Cap: £212b
For the cash flow focused theme of this screener, Shell matters because its LNG engine and low carbon contracts can turn energy volatility into contracted cash coming in the door.
"With an LNG portfolio exceeding 60 million tons and unparalleled trading capabilities, Shell is the company that benefits most from the volatility in the global gas market."
What happens to Shell’s valuation gap if a single unseen pressure reshapes how much of that cash actually drops through to margins?
If that unseen pressure matters to you, read the full narrative for Shell to see how Shell’s cash engine, contracts and capital choices could be quietly reshaping investor expectations.
BAE Systems (LSE:BA.)
Overview: BAE Systems provides defense, aerospace and security equipment and services, with a key cash-flow link in high-margin electronics and munitions.
Operations: The group generates most revenue from Electronic Systems at £7.8b, Air at £7.7b and Maritime at £6.7b across primarily US and UK customers.
Market Cap: £52.2b
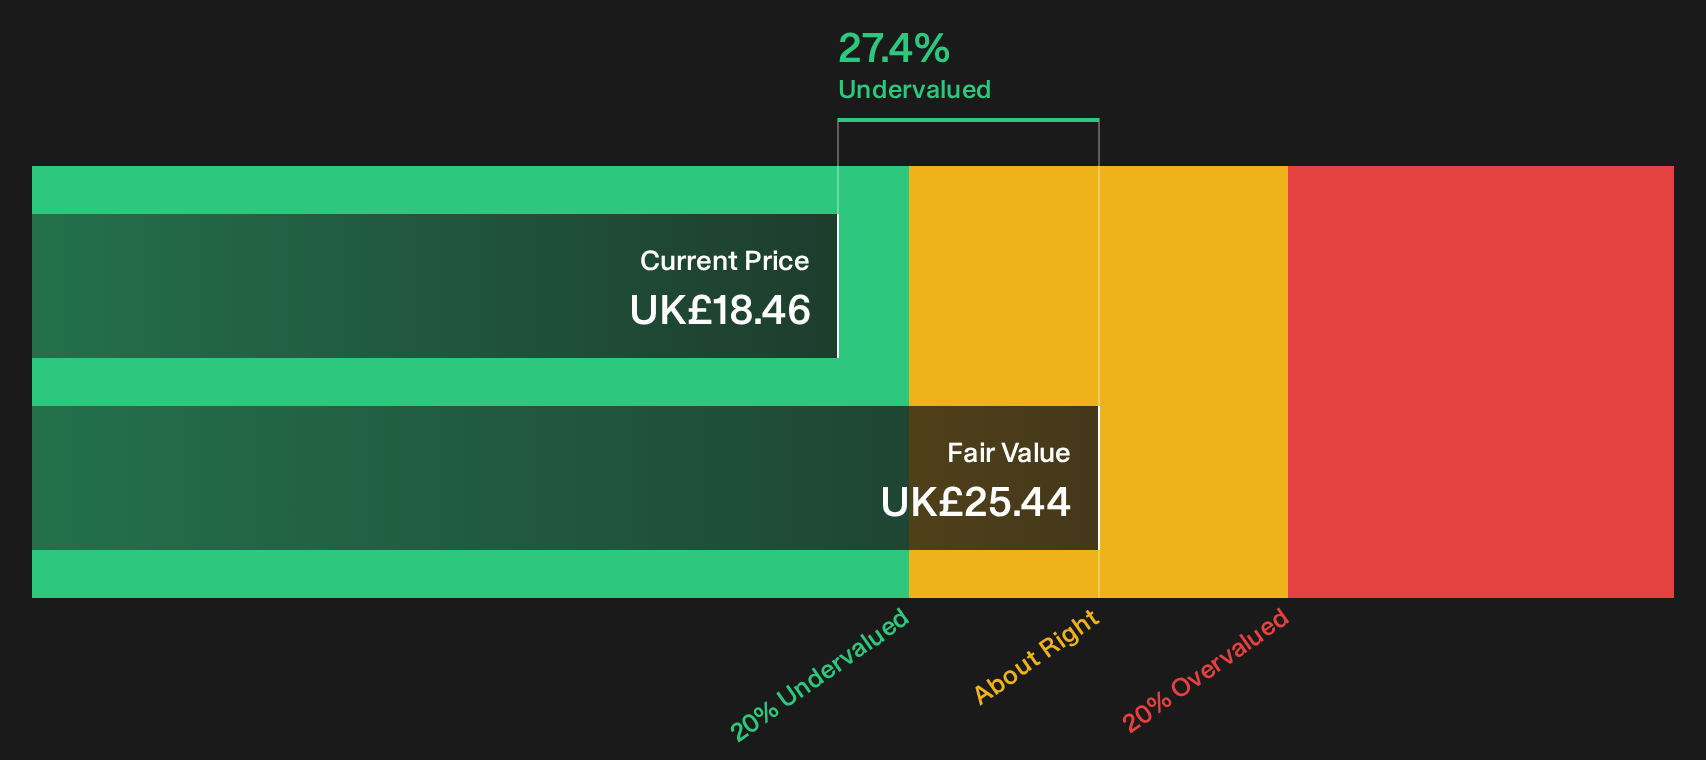
BAE Systems matters for a cash-flow focused screen because its precision weapons, avionics and electronic warfare franchises often sit on long, contractual programs that can keep money coming in long after the initial kit is delivered.
"The company's order backlog reached £84b with total backlog plus incumbent program positions of around £260b, which equals about 8x annual sales and indicates multi year support for revenue and earnings."
The real test for investors will be how one quiet shift in product mix and capacity eventually feeds through into margins and free cash generation.
That quiet shift is the real story, and the full narrative for BAE Systems shows how BAE Systems’ backlog, mix and cash generation could be decoupling from headline contract wins.
Smith & Nephew (LSE:SN.)
Overview: Smith & Nephew develops medical devices for joint replacement, sports injuries and advanced wound care products that support recurring treatment needs.
Operations: Smith & Nephew generates about US$2.5b from Orthopaedics, US$2.0b from Sports Medicine & ENT and US$1.8b from Advanced Wound Management.
Market Cap: £9.7b
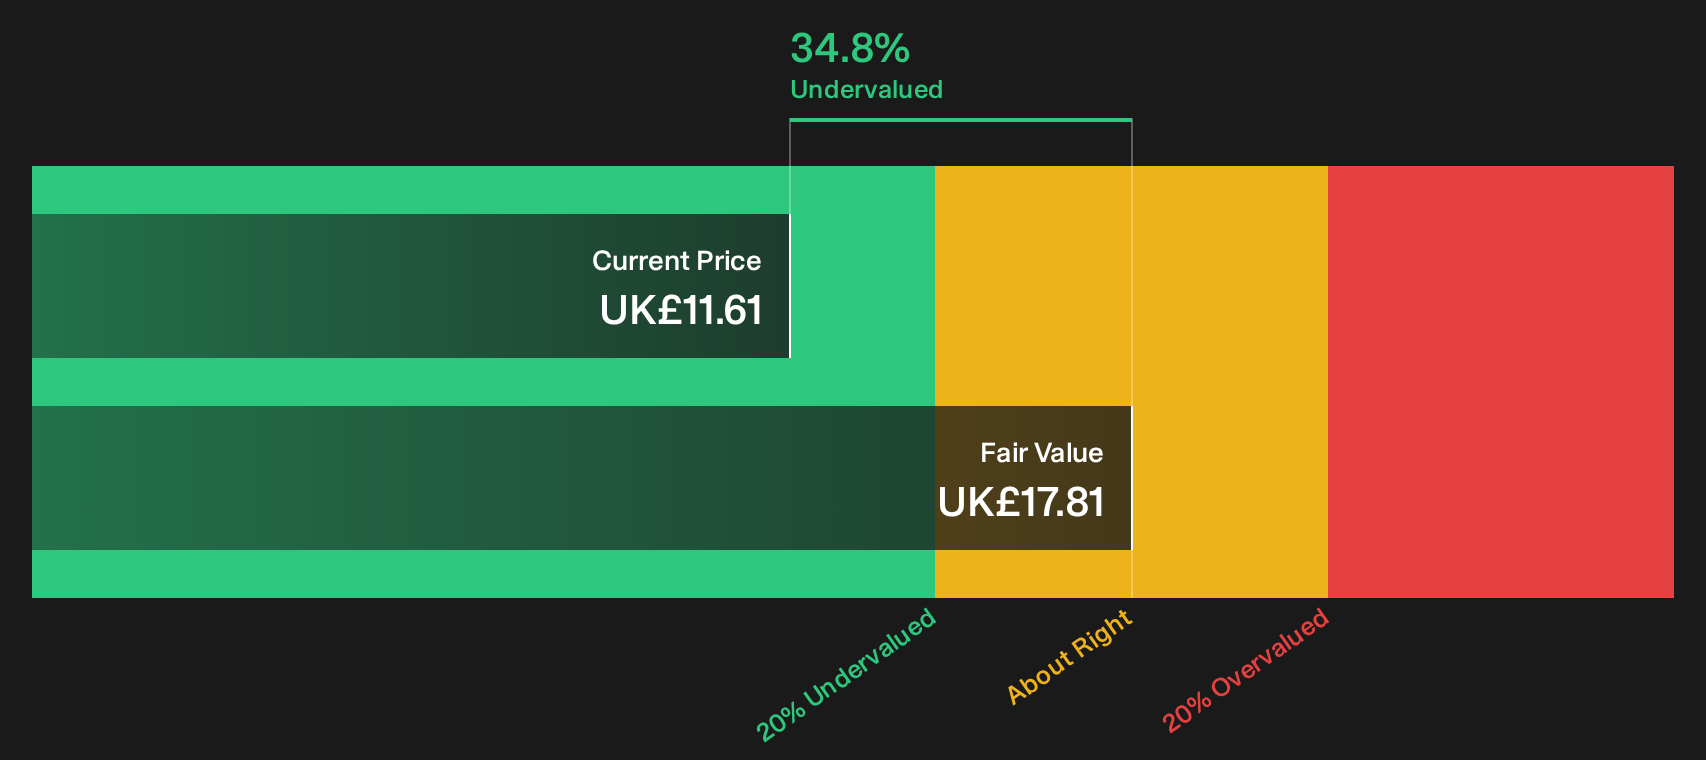
Smith & Nephew matters for this cash-flow screen because its Advanced Wound Management products feed repeat procedures and therapies that are well suited to DCF style valuation.
"Growing penetration of CORI handheld robotics, with double digit growth in placements, higher utilization and greater ASC adoption, positions Smith & Nephew to earn more recurring software, service and implant revenue per site as robotics and enabling technologies become a larger share of global joint replacement and shoulder surgery."
What happens to Smith & Nephew’s valuation gap if one quiet shift in procedure mix meaningfully changes how much free cash actually shows up?
That inflection point is exactly what the full narrative for Smith & Nephew unpacks, showing where recurring robotics and wound care cash flows might be accelerating or quietly stalling next.
Seeking Alternatives Before Others Catch On
Fresh ideas move first. By the time momentum shows up on charts, early opportunities can be flying or already caught. Scan these curated stock sets while it matters and consider acting early.
- Scan curated high yield candidates in the 4 dividend fortresses to spot potential income opportunities before payout momentum attracts wider attention.
- Track early movers in AI infrastructure and chip demand cycles through the hand picked universe inside the 53 AI infrastructure stocks while they are still under the radar.
- Focus on under followed automation leaders by running the 90 robotics and automation stocks before robotics adoption becomes a dominant theme in market coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com