
What Saipem Doubters Got Wrong Before A 100% Rally
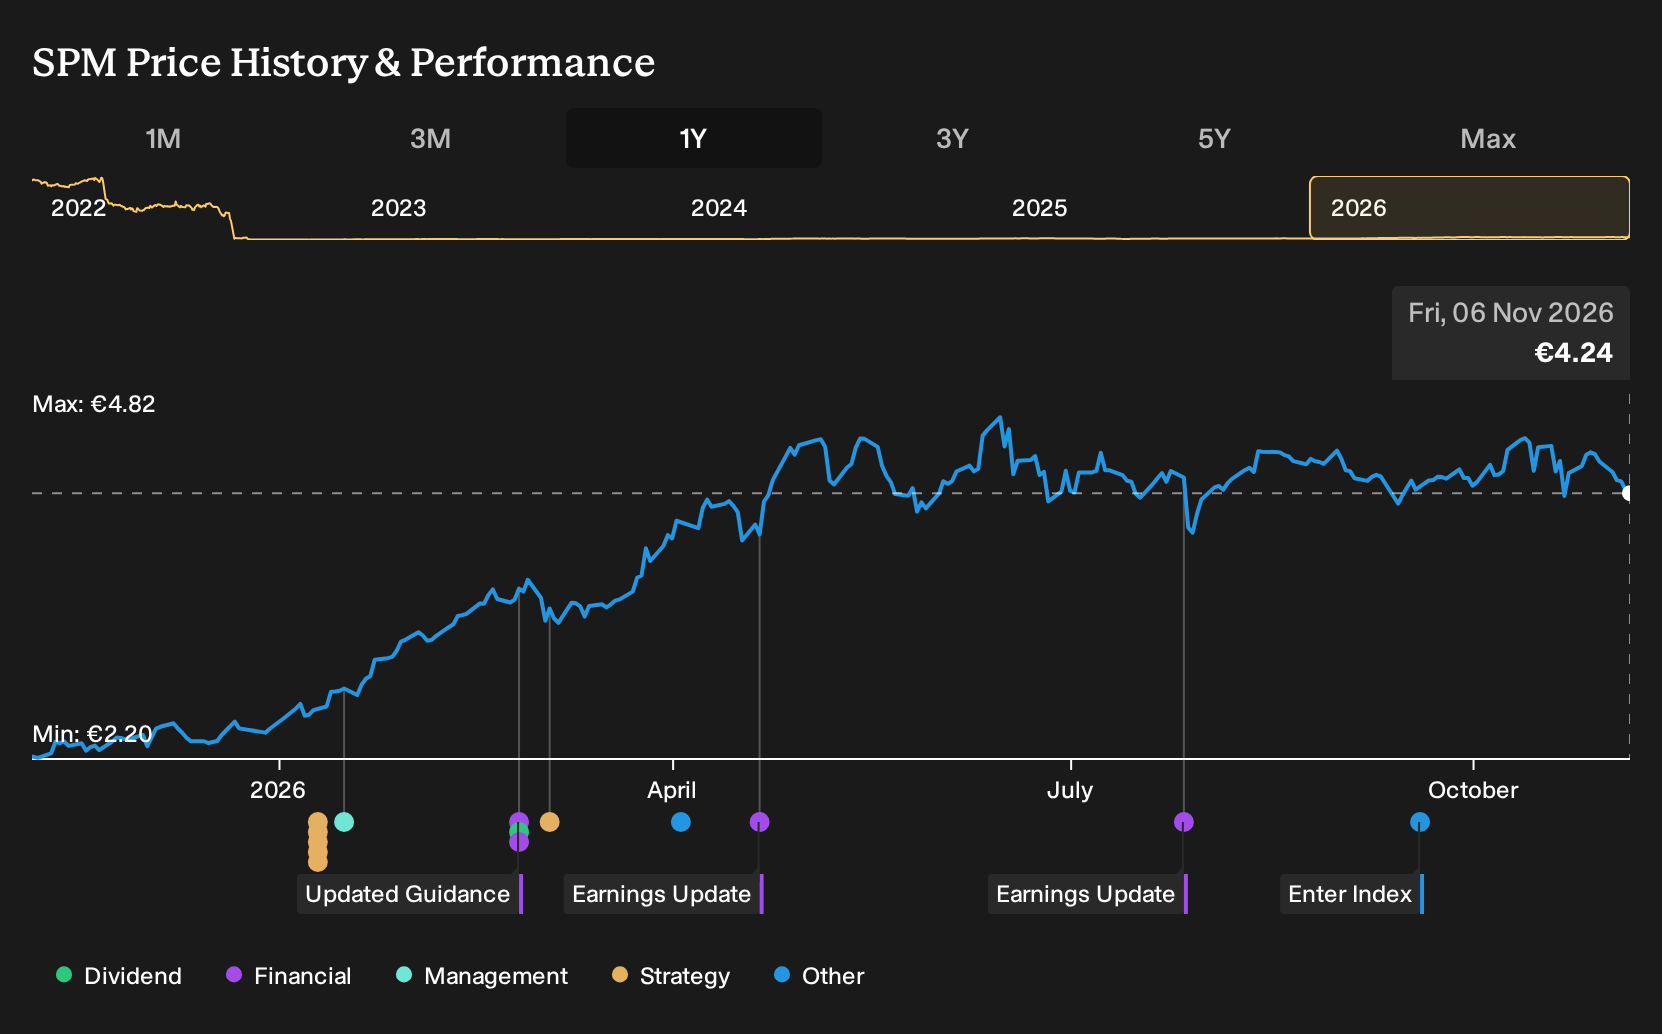
If you had bought Saipem on 6 November 2025, you would probably be replaying that decision now. For Saipem shareholders, the return over the past year was 99.8%, including dividends. At the time, analysts were split between a bullish LNG and energy transition story on one side and a more cautious read on fossil demand and execution risk on the other. With that in mind, what exactly were early buyers weighing when they stepped in?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Saipem harder to judge, start where the gap is still open and scan 222 high quality undervalued stocks.
The Two Saipem Stories Investors Had To Compare
The shares cost €2.21 at the start of the period, and Saipem sat between two very different stories that both sounded reasonable at the time.
On the bullish side, the Fair Value was €3.54, or 60% above the start price. This was built on expectations of rising fleet bookings, multi year LNG contract wins, and an energy transition portfolio that could support higher margins.
The bearish narrative pointed to a Fair Value of €2, or 9% below the start price. It focused on declining fossil fuel demand, ESG pressure, and the risk that competition and legacy project issues would keep earnings volatile.
What The Saipem Evidence Actually Tested
The clearest signal came from Saipem’s contract flow. Multi hundred million dollar awards in Saudi Arabia, Angola, Guyana and Ivory Coast, plus work on Neptun Deep and biorefining, supported the bullish argument that the order book could stay busy. Reported results told a different story. Revenue moved from €3,697m to €3,826m while net income dropped from €63m to €18m and net margin slipped to 0.5%. The evidence cut both ways.
The hinge assumption here was simple. Bulls and bears were really arguing over whether strong order intake would translate into cleaner, more profitable projects. When you look at another contractor, test that claim directly against future margins, not just the size of the backlog or headlines about new work.
What Saipem’s Price Now Asks You To Believe
Saipem now trades at €4.24, roughly double the €2.21 starting point, and the selected Narrative’s Fair Value sits below that market price.
The Narrative argues the key issue is whether current project profitability can hold up against cost inflation and segment softness. A buyer today is effectively backing sustained higher margins, so the question is how that assumption holds against the risk of offshore cost overruns and drilling weakness.
"Although Saipem points to high utilization and a strong commercial pipeline in offshore and deepwater services, the cut to 2026 adjusted EBITDA guidance to €1.75b after extra Middle East conflict costs suggests that further unplanned cost inflation on long duration offshore projects could erode the higher margin profile that is now priced in, which would weigh on earnings quality."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 33% below our estimate - manages renewable focused real assets while seeking tax efficient fundraising inflows.
- Company 2 - 17% below our estimate - sells automated cooking systems as customers upgrade kitchens for efficiency gains.
- Company 3 - 40% below our estimate - recovers from a supply disruption while gaming and collaboration products sustain demand.
That is three of the list. See every one of the 192 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com