
United Fire Group (UFCS) Reports Fresh Results, Is The Stock Still A Bargain?
United Fire Group (UFCS) just released its third quarter and nine month 2026 results, giving investors fresh numbers on profitability, earnings per share, and how the insurance writer is tracking through the year.
Recent trading tells a mixed story for United Fire Group. The share price is up 34.15% year to date and the 1 year total shareholder return is 37.53%, yet the 7 day share price return is down 16.01% and the 30 day share price return is down 13.44%. This suggests that shorter term momentum has faded, while multi year total shareholder returns of 160.50% over 3 years and 147.66% over 5 years indicate a much stronger long run experience for investors.
Scan beyond United Fire Group and compare it with a hand picked list of solid balance sheet and fundamentals (25 results) to see how other insurers and financial stocks stack up on resilience and fundamentals.
United Fire Group has surged over the past few years, then dropped hard in recent weeks after its latest quarterly update. Does that pullback offer a reasonable entry now? Or does patience make more sense until valuations reset further?
Most Popular Narrative: 18% Undervalued
United Fire Group closed at $47.73, while the most followed narrative puts fair value at $58.50. The recent pullback still sits against a valuation gap built on specific assumptions about earnings resilience and catastrophe risk.
The ongoing increase in the frequency and severity of climate related events continues to raise the likelihood of higher future catastrophe losses for United Fire Group. This could push loss ratios closer to or above the company’s estimated full year catastrophe load and introduce more volatility into net earnings.
See why 3 investors see United Fire Group as 18% undervalued.
Result: Fair Value of $58.50 (UNDERVALUED)
Still, United Fire Group’s story can change quickly if catastrophe losses move higher again, or if pricing pressure in property and casualty lines squeezes margins harder than expected.
Find out about the key risks to this United Fire Group narrative.
Another View: Cash Flows Paint a Tougher Picture for United Fire Group
While the leading narrative pegs United Fire Group’s fair value around $58.50 based on earnings and multiples, the Simply Wall St DCF model lands closer to $39.90 per share. That points to United Fire Group trading above this cash flow based estimate and leaves you asking which set of assumptions deserves more weight.
To unpack how sensitive that result is to growth, margins and discount rates, take a closer look at how the SWS DCF model treats United Fire Group’s future cash flows: Look into how the SWS DCF model arrives at its fair value.
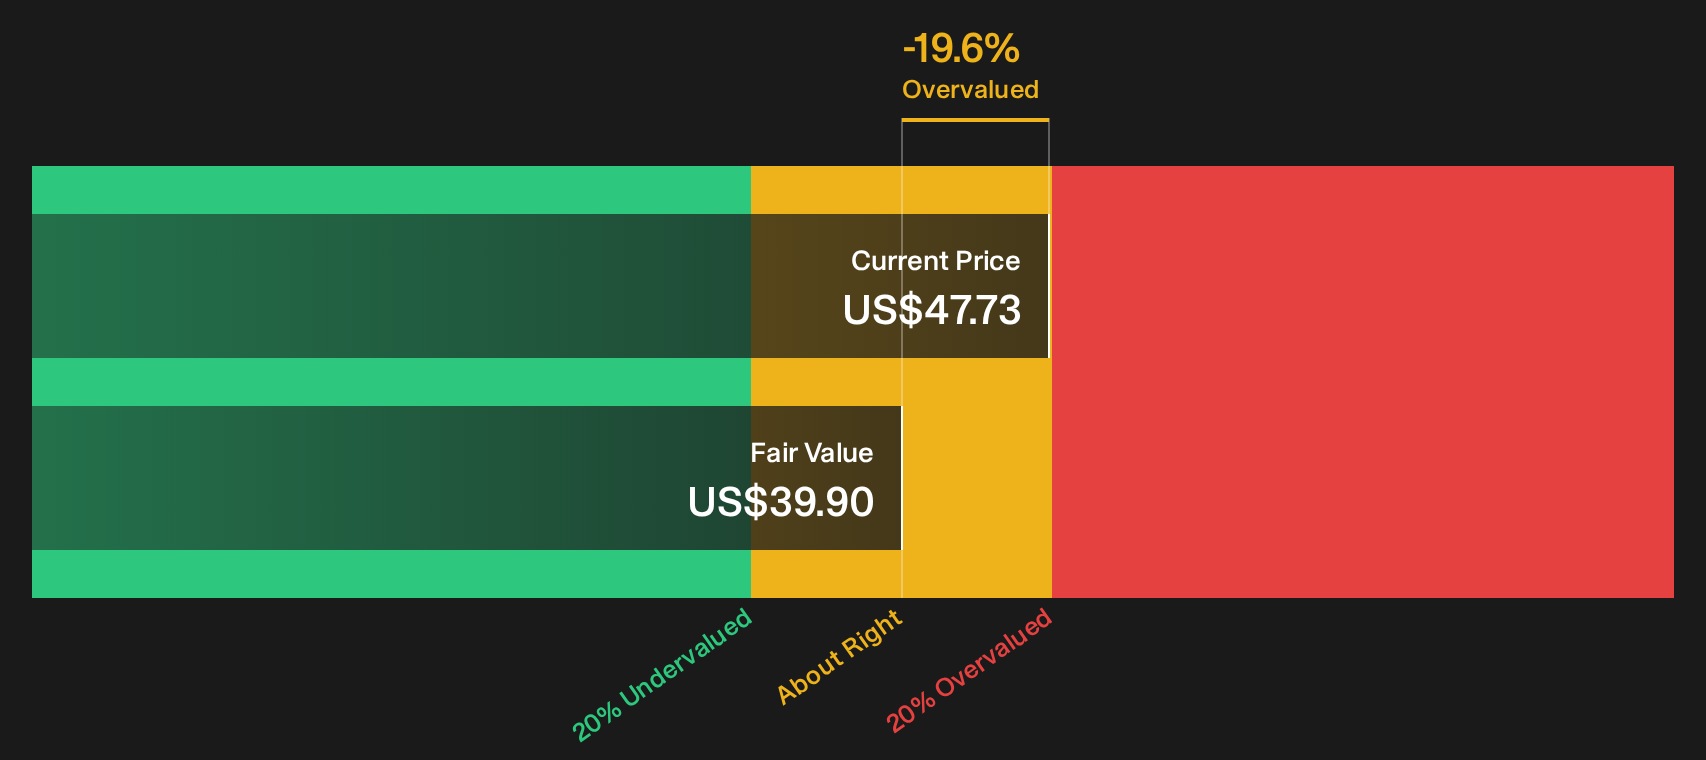
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out United Fire Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in United Fire Group’s story pulls in opposite directions, so act quickly, review the underlying data and pressure test the trade off between upside and downside. To frame that decision with a clear snapshot of both sides, start with 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond United Fire Group?
If United Fire Group is on your radar, broaden your opportunity set with other ideas that match different risk levels, return profiles, and income goals.
- Target potential upside in beaten down opportunities by scanning a curated pool of 38 high quality undervalued stocks that combine quality with attractive pricing signals.
- Strengthen your portfolio foundation with companies screened for robust finances through a focused list of solid balance sheet and fundamentals (25 results) that filters for resilience first.
- Hunt for future leaders early by using a refined 19 high quality undiscovered gems to surface lesser known businesses with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com