
3 AI Stocks Trading Under 30x P E
Electricity has become the new bottleneck for AI. With governments debating whether to restrict new data centers instead of adding more power supply, the scramble for efficient computing hardware is front and center. That is where the companies powering chips, foundries and equipment come in, providing the engines of AI. This article highlights three stocks from our screener that capture this hardware build out.
The three semiconductor supply chain stocks covered below are only a small sample, as the full screen surfaced 62 more hardware players with equally compelling AI power and equipment narratives that are not discussed in this article. To size up that broader opportunity set directly, head into the Semiconductor Supply Chain screener to analyze, filter and identify the highest conviction semiconductor supply chain ideas for your watchlist.
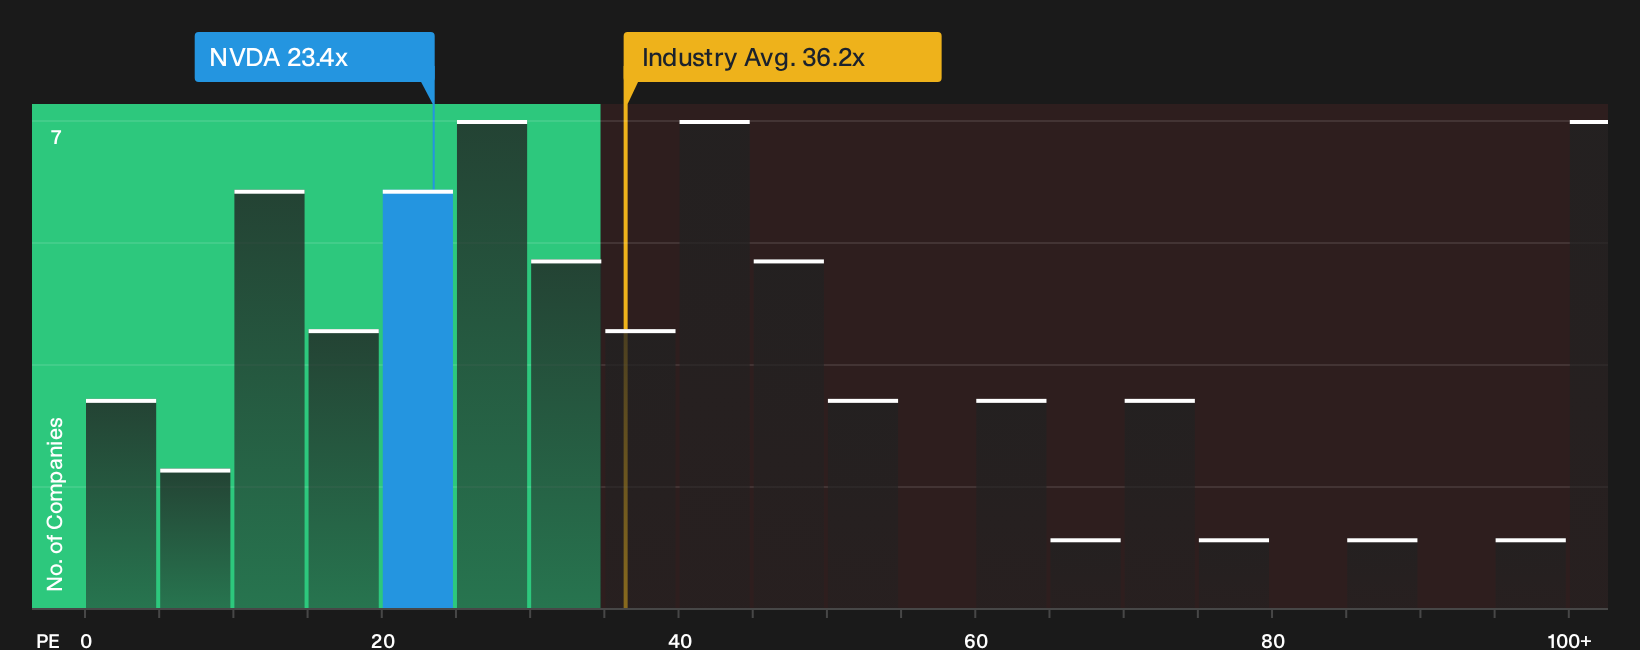
NVIDIA (NVDA)
Overview: NVIDIA is a global chip designer focused on data center AI GPUs and platforms, alongside graphics processors for gaming, visualization and automotive.
Operations: NVIDIA generates about US$275.4b from Compute & Networking and US$27.6b from Graphics across customers in the United States, Taiwan, China and other regions.
Market Cap: US$4,507b
NVIDIA matters for this Semiconductor Supply Chain screener because its data-center GPUs and AI platforms have become the preferred compute engine for many large-scale AI projects worldwide.
"Uptake of an open-source, cheaper, or better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products."
For investors, a single untested assumption about long-term AI customer spending breaking down could reshape NVIDIA’s pricing power and earnings quality.
That fragility cuts both ways, and the full narrative for NVIDIA shows how CUDA reliance, AI demand and potential platform shifts could be accelerating strengths rather than simply amplifying risk.
Applied Materials (AMAT)
Overview: Applied Materials supplies chipmakers with materials engineering tools and services that enable advanced semiconductor fabrication, including AI focused wafer production.
Operations: Applied Materials generates about US$22.4b from Semiconductor Systems and US$7.2b from Applied Global Services across major Asian, US and European chip hubs.
Market Cap: US$264.0b
Applied Materials matters for this Semiconductor Supply Chain screener because its fabrication tools sit directly in the production flow for cutting edge AI chips, giving the business a central role in how much advanced capacity actually gets built.
"The mix shift toward leading edge foundry logic, DRAM including high bandwidth memory, and advanced packaging is expected to account for most wafer fab equipment growth in 2026 and 2027, and Applied Materials is forecasting more than 70% growth in advanced packaging revenue and more than 50% growth in process diagnostics and control in 2026."
What happens to Applied Materials’ earnings power depends on how one quiet shift in its higher value offerings plays out against those projects.
That quiet shift is where the real story starts, and the full narrative for Applied Materials explains how Applied Materials’ higher value engines could be accelerating far beyond headline tool orders.

Lam Research (LRCX)
Overview: Lam Research supplies wafer fabrication equipment for etch, deposition and cleaning that chipmakers rely on to build AI focused logic and memory devices.
Operations: Lam Research generates about US$26.1b from manufacturing and servicing wafer processing equipment across China, Taiwan, Korea, Japan, Southeast Asia, Europe and the United States.
Market Cap: US$250.4b
Lam Research matters for this Semiconductor Supply Chain screener because its etch and deposition tools are the workhorses enabling AI centric fabs to pattern, wire and stack ever more complex chips.
"The June quarter's doubling is the first real evidence the upgrade cycle has started. If that spending stays front-loaded through calendar 2027 as management expects, FY2027 and FY2028 revenue estimates are too low."
What happens if one quiet shift in how memory makers fund this buildout changes the durability of Lam Research’s current profitability profile?
That funding shift is the real tension point, and the full narrative for Lam Research shows whether Lam Research’s upgrade cycle is quietly accelerating or masking future volatility.

Seeking Fresh Alternatives Before They Fly
New themes are breaking out, momentum is building, and quieter stories are getting caught before the crowd even looks. Scan these fresh ideas while it matters and consider them early.
- Target resilient cash generators with steady footing by running the list of solid balance sheet and fundamentals (25 results) and spot businesses that may hold up when weaker peers start dropping.
- Look for potential AI infrastructure leaders using the curated 53 AI infrastructure stocks and track companies building the rails that keep data and models running.
- Identify notable cash return stories through the hand picked 7 dividend fortresses and review income engines that may stand out if yields change quickly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com