
Carlyle Group (CG) Faces A Valuation Test After Record Earnings Met A Net Loss
Carlyle Group (CG) just reported record fee related earnings and US$479b in assets under management, yet the latest quarter showed a net loss and lower nine month revenue, prompting investors to rethink near term profit expectations.
The latest earnings release, dividend affirmation and ongoing SEC application arrived against a tougher share price backdrop, with Carlyle Group trading at US$39.70 after a 30 day share price gain of 3.33%. This has not offset a year to date decline of 34.77% and a 1 year total shareholder return that is down 22.16%, even though the 3 year total shareholder return remains up 43.99%. This suggests shorter term momentum has faded while longer term holders are still in positive territory.
Compare Carlyle Group's recent reset in expectations with other potential value ideas by scanning our hand picked list of 38 high quality undervalued stocks across global markets.
Carlyle Group now combines record fee related earnings with a weak recent share chart and a reported loss. The question for investors is whether that mix still skews the risk reward toward buyers when you look at the valuation next.
Most Popular Narrative: 24% Undervalued
Carlyle Group is framed as undervalued in the most followed narrative, with a fair value of $52.50 set against the recent $39.70 close. This framing puts the focus squarely on execution and durability of earnings.
The valuation opportunity depends on Carlyle converting its operational improvements into more consistent earnings. Its weaknesses explain part of the discount.
See why 1 investors see Carlyle Group as 24% undervalued.
Result: Fair Value of $52.50 (UNDERVALUED)
Still, the Carlyle Group story can break if fundraising disappoints again or fee profitability stalls, which would quickly challenge the current view that the stock is undervalued.
Find out about the key risks to this Carlyle Group narrative.
Another View: Carlyle Group Looks Expensive On Earnings
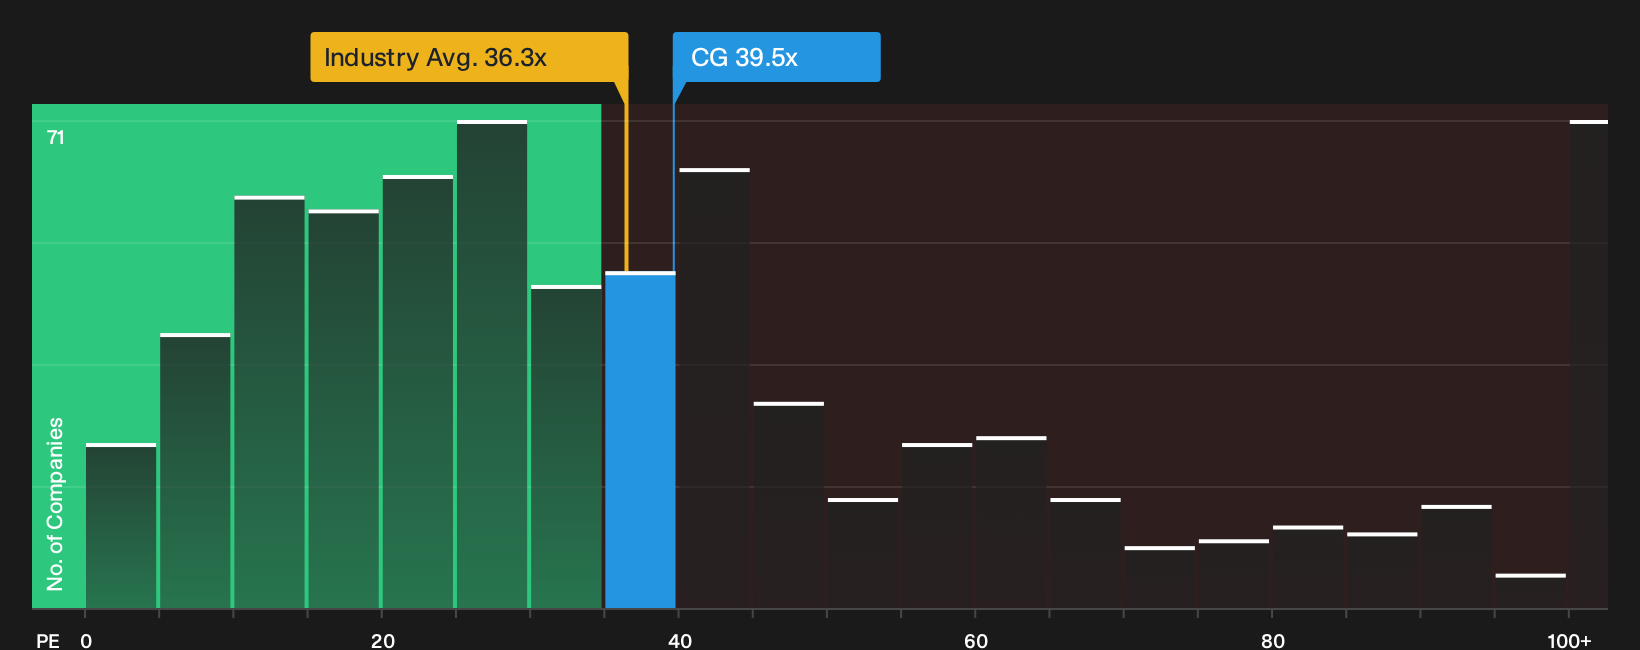
Carlyle Group screens as undervalued on future cash flows, yet the simple earnings multiple tells a different story. The current P/E of 39.5x sits above both the US Capital Markets industry on 36.3x and the peer average of 29.1x, while the fair ratio is 18.2x.
That gap implies investors today are paying a rich price against current earnings for a business with weaker recent profit margins and forecast improvement already embedded in the multiple. The question is how comfortable you are relying on that outlook when the share price is already pricing in a lot of progress.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Carlyle Group's valuation can feel messy, so consider acting promptly, review the data independently, and weigh both the potential upside and the red flags by reviewing the 2 key rewards and 4 important warning signs.
Looking for more Carlyle Group sized opportunities?
If you are reassessing Carlyle Group today, use this moment to scan other ideas on Simply Wall St before the next set of numbers reshapes the opportunity set.
- Target potential value gaps by comparing Carlyle Group with a 38 high quality undervalued stocks that pair solid fundamentals with prices that lag underlying performance.
- Prioritise resilience in tougher markets by focusing on a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks than highly leveraged peers.
- Get ahead of the crowd by reviewing a 19 high quality undiscovered gems that have quality metrics most investors are not watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com