
Top 3 Australian Penny Stocks With Revenue Growth Over 5%
Australia’s latest hot CPI reading has strengthened expectations for higher interest rates, which keeps pressure on highly priced blue chips and credit-heavy sectors. That backdrop is shifting more attention toward lower priced, financially sound Australian penny stocks that do not rely as heavily on cheap money to tell their story. This article walks through three such opportunities from our screener that combine modest share prices with an emphasis on balance sheet health.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses with a focus on financial strength. However, if you want the absolute best, these 21 elite penny stocks are the cream of the crop.
DroneShield (ASX:DRO)
Overview: DroneShield develops and sells counter-drone hardware and software that detect, track, and disrupt hostile drones for defence and critical infrastructure customers.
Operations: The group reports A$270 million from Aerospace & Defense activities, with A$37 million from the USA and A$243 million from Australia and the rest of the world.
Market Cap: A$1.18b
DroneShield fits the Financially Fit Penny Stocks theme through its focus on counter-drone systems that aim to secure sensitive sites while keeping a close eye on balance sheet strength and funding needs as the business scales.
"If management continues converting its growing pipeline into multi-year contracts while expanding margins through scale manufacturing, we could see a valuation re-rating over the next 12 to 24 months."
What happens when one unresolved pressure on future margins and cash generation finally meets the scale DroneShield is working toward.
When that pressure finally bites, the full narrative for DroneShield shows how DroneShield’s contract momentum, funding options and execution risks could interact to accelerate or stall a rerating.
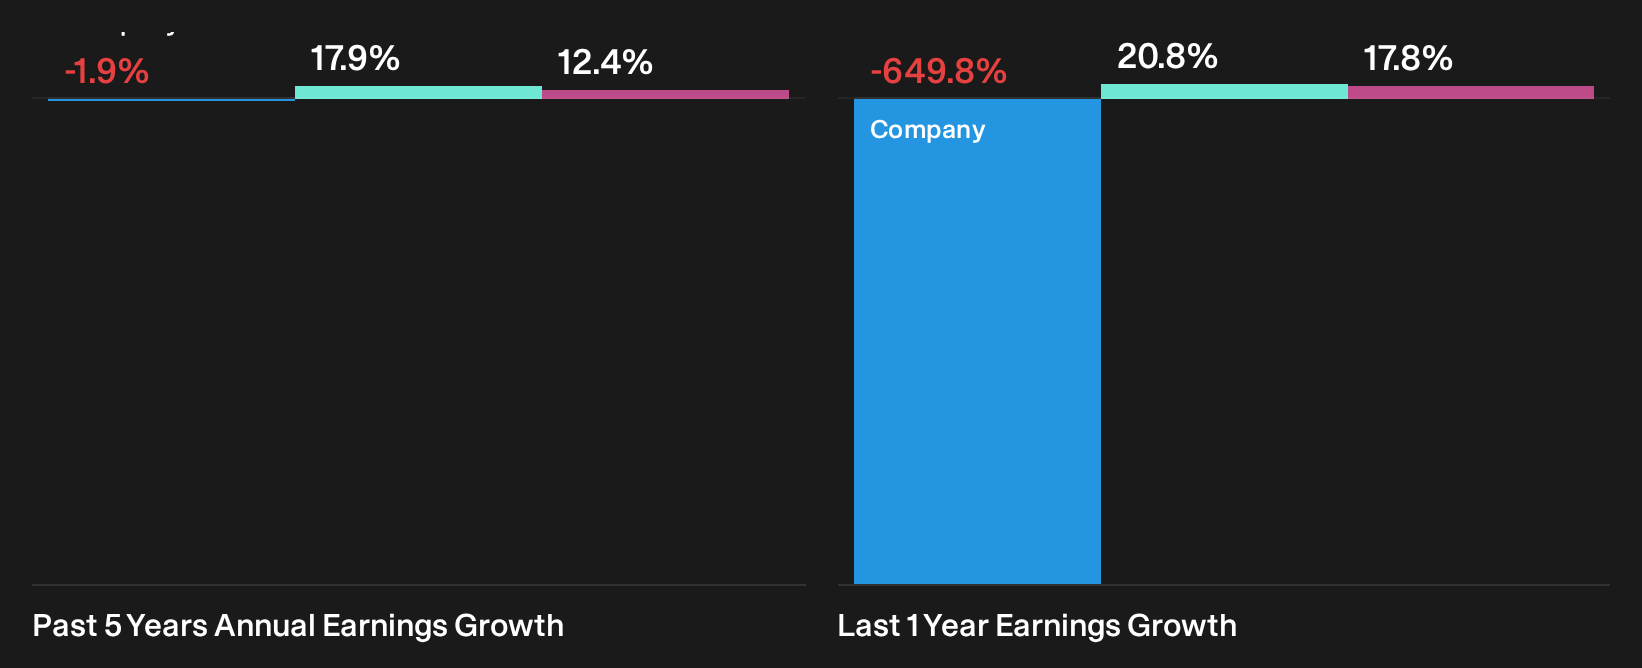
Macmahon Holdings (ASX:MAH)
Overview: Macmahon Holdings provides contract surface and underground mining and civil infrastructure services that give miners long term, fee based project support.
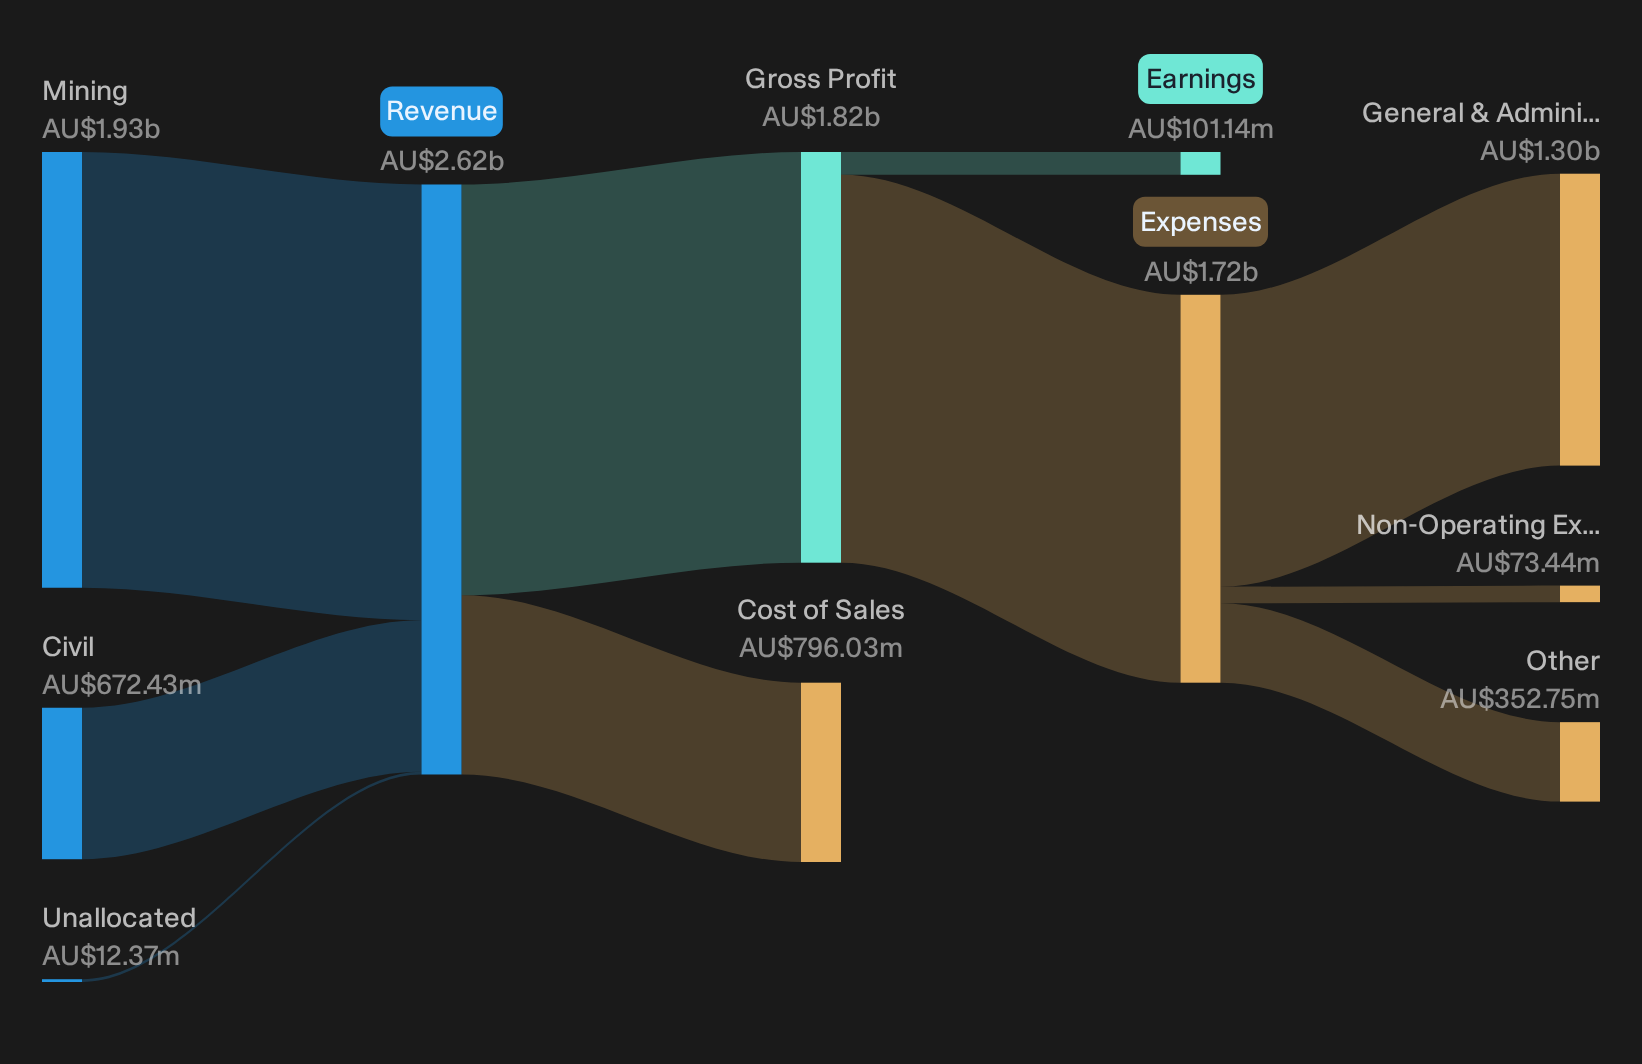
Operations: Macmahon generates about A$1.93b from mining services and A$672 million from civil work, with almost all revenue earned in Australia.
Market Cap: A$2.0b
Macmahon Holdings fits the Financially Fit Penny Stocks theme through its contract mining and civil work, where multi year agreements can support steadier cash flow and lower project risk than owning the mines themselves.
"The growing mix of underground mining and civil infrastructure work, with underground now around 24% of revenue and civil contributing roughly 26%, supports Macmahon Holdings’ aim to reach underground revenue of A$750 million and civil revenue of A$1 billion by FY28."
One key consideration is how shifts in the way those contracts convert into cash could either reinforce that growth plan or limit potential upside at the margin.
That cash conversion question is where the full narrative for Macmahon Holdings maps out how Macmahon Holdings could see contract cash flows accelerate, stall or quietly decouple from headline revenue targets.
Perenti (ASX:PRN)
Overview: Perenti provides underground and surface contract mining, drilling and technical services, giving miners fee based access to large, recurring projects.
Operations: Perenti generates about A$2.43b from Contract Mining Services and A$843 million from Drilling Services, with smaller contributions from Mining and Technology Services.
Market Cap: A$1.89b
Perenti fits the Financially Fit Penny Stocks theme through its contract mining focus, where long term service agreements can support steadier cash generation than early stage explorers.
"Expanding work in hand of $6.2b with a contract renewal rate above 90% for long term contracts and relationships with large gold producers supports the view that Perenti’s existing client base can sustain revenue and earnings over multi year periods."
The real swing factor is how one shifting element in that contract and regional mix ultimately filters through to margins and cash returns.
That turning point is exactly where the full narrative for Perenti shows whether Perenti’s contract mix is quietly building accelerating cash strength or masking margin risk.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Stocks with building momentum can break out while slower money is still watching. Catch what others miss while it matters, get in early.
- Explore potential yield resilience by scanning income ideas with the 5 dividend fortresses that focus on stronger balance sheets instead of payout stories tied to cheap credit.
- Track early AI momentum shifts through the 53 AI infrastructure stocks that highlights businesses supplying the picks and shovels for expanding compute demand.
- Search for defensive characteristics using the 6 resilient stocks with low risk scores that filters for sturdier fundamentals so you are not exposed to more fragile stories when sentiment drops.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com