
Did OLED Rear Light Win Just Shift Elmos Semiconductor's (XTRA:ELG) Investment Narrative?
- Elmos Semiconductor SE reported that its new 48 channel E522.96 LED controller was chosen for initial OLED rear light applications by a well known German premium automaker, supporting high resolution lighting designs with more than 500 individually controllable pixels across both rear lights.
- The design win signals that Elmos Semiconductor’s higher channel count LED controllers and related portfolio, including the E522.95 and Smart Edge Gateway ICs, are aligning with automakers’ shift toward complex lighting functions and flexible vehicle architectures.
- We will now see how Elmos Semiconductor’s OEM win for its 48 channel LED controller could shape the longer term investment narrative.
Scan how Elmos Semiconductor's OLED lighting win compares with other auto electronics players by lining up the hand picked 90 robotics and automation stocks that could benefit from similar hardware adoption trends.
Elmos Semiconductor Investment Narrative Recap
To own Elmos Semiconductor, you need to believe its focus on high content automotive chips, backed by secure 8 inch capacity and long term OEM relationships, can keep turning design wins into steady production. The new OLED controller selection fits this thesis but is one product within a broader portfolio, so it does not transform the near term story on its own.
The key short term swing factor still looks like how reliably Elmos Semiconductor can access foundry and assembly capacity as AI power chips compete for similar nodes. The biggest risk is that external suppliers prioritize other customers, which could delay ramps, pressure gross margin pass through and make earnings less predictable.
The E522.96 rear light win lines up closely with earlier commentary about tight 8 inch capacity giving Elmos Semiconductor room to pass on higher input costs. A premium German OEM choosing a higher channel controller supports the idea that content per vehicle can rise, which matters if you are watching whether the order book can feed into future serial production.
Previous focus on long dated capacity deals, including Dortmund access to at least 2028 and the SK keyfoundry agreement through 2037, looks relevant here. If Elmos Semiconductor can pair those wafer agreements with more multi year design wins like the OLED controller, the combination of content, supply security and China demand momentum becomes the core operational catalyst to track against capacity and earnings volatility risk.
Elmos Semiconductor's current analyst narrative points to revenues of €889.1 million and earnings of €179.8 million by 2029, based on an assumed 12.5% yearly revenue growth rate and an earnings increase of about €77.5 million from €102.3 million today.
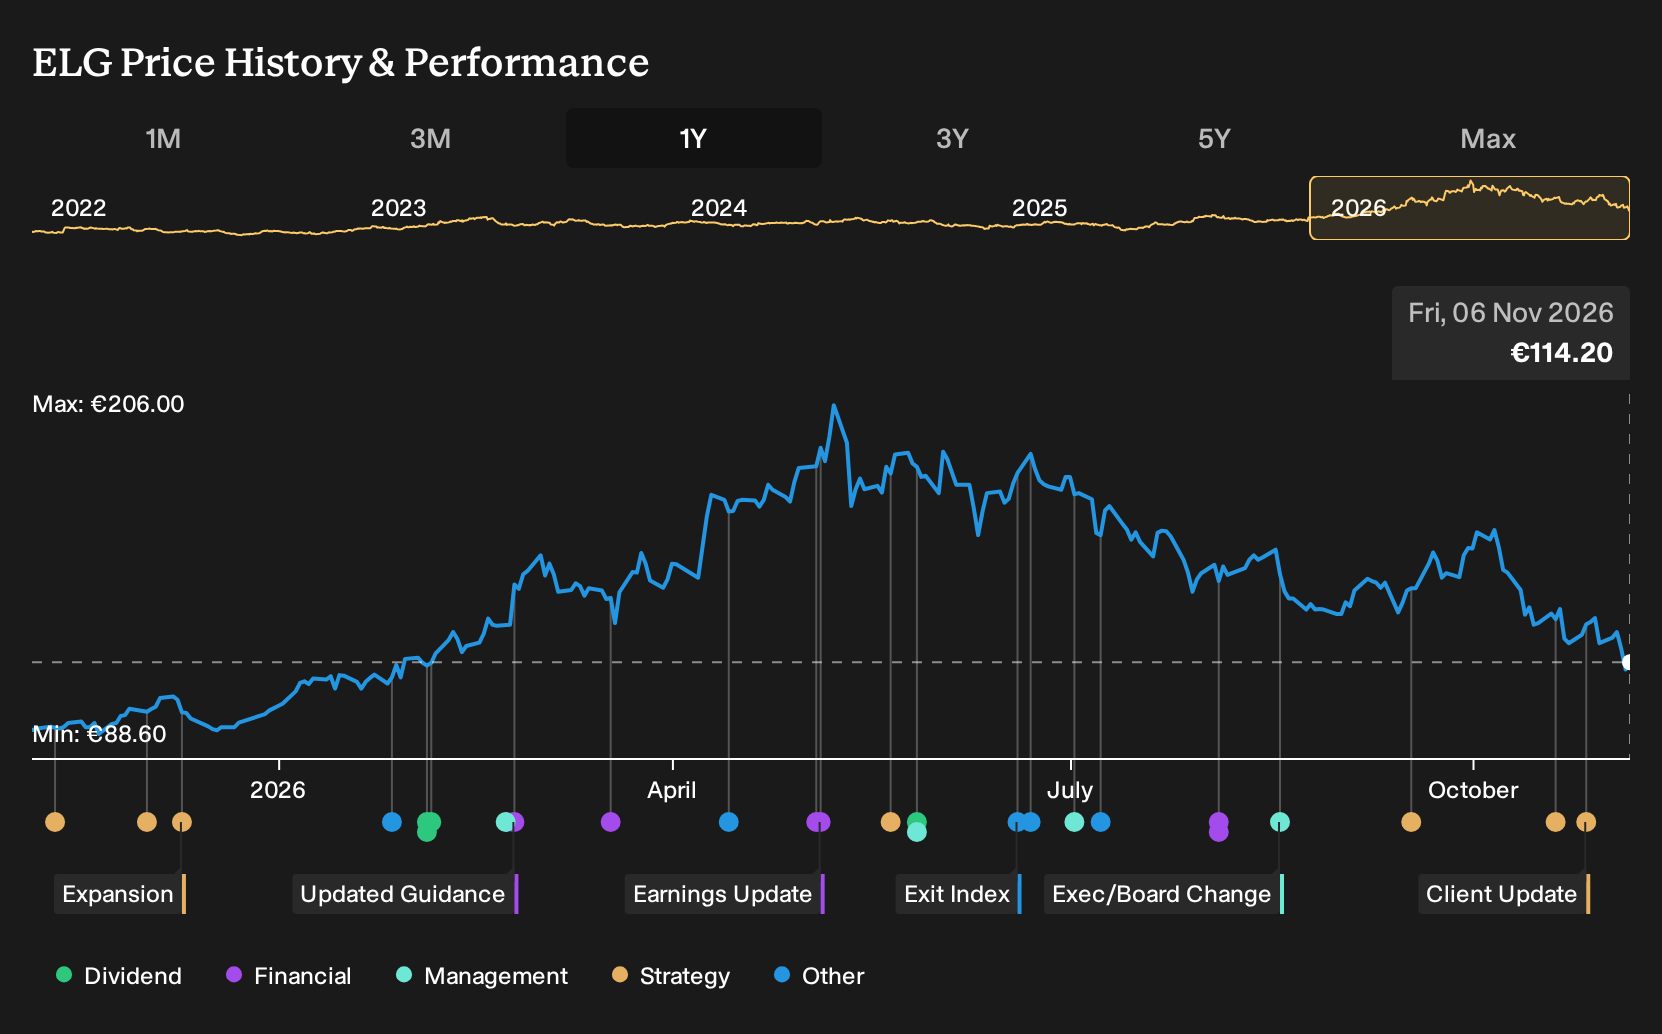
Uncover why Elmos Semiconductor's fair value indicates a 69% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on wafer capacity risk and more on how Elmos Semiconductor could use its cash flow. Before this OLED news, the bullish camp was already modeling about €925.9 million of revenue and €199.2 million of earnings by 2029. You can compare that upbeat script with your own expectations and decide whether this design win nudges those forecasts up or not.
Explore 4 other Elmos Semiconductor fair value estimates, including one that suggests potential upside of up to 88% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Elmos Semiconductor research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Elmos Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elmos Semiconductor's overall financial health at a glance.
Looking for more Elmos Semiconductor style investment ideas?
If the Elmos Semiconductor story has you thinking about where else complex chip demand and solid balance sheets could matter, it can help to line up a wider watchlist using the Simply Wall St Screener.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (192 results) and see which businesses pair sturdy balance sheets with consistent fundamentals.
- If income is the priority, you may want to focus on payout strength and stability by scanning a set of 228 dividend fortresses that could fit a yield focused playbook.
- Hungry for under-the-radar opportunities? Look across a 582 high quality undiscovered gems that combine strong underlying metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com