
Gold Stocks To Watch As Central Bank Buying Meets A Hawkish Fed
Gold is being squeezed from both sides, with a hawkish Fed and softer long term price forecasts on one side and persistent central bank buying on the other. That tension is where opportunity often hides, as some companies see near term pressure while others quietly build leverage to any eventual shift in real yields. This article walks through three stocks exposed to that tug of war and explains how the recent news event could matter for your portfolio decision making.
The three stocks below are only a starting sample, since the wider screen surfaced 28 more gold mining and royalty companies with equally compelling narratives that are not covered in this article.
To identify and analyze those additional opportunities in one place, head straight to the Gold Mining and Royalty Companies screener.
AngloGold Ashanti (AU)
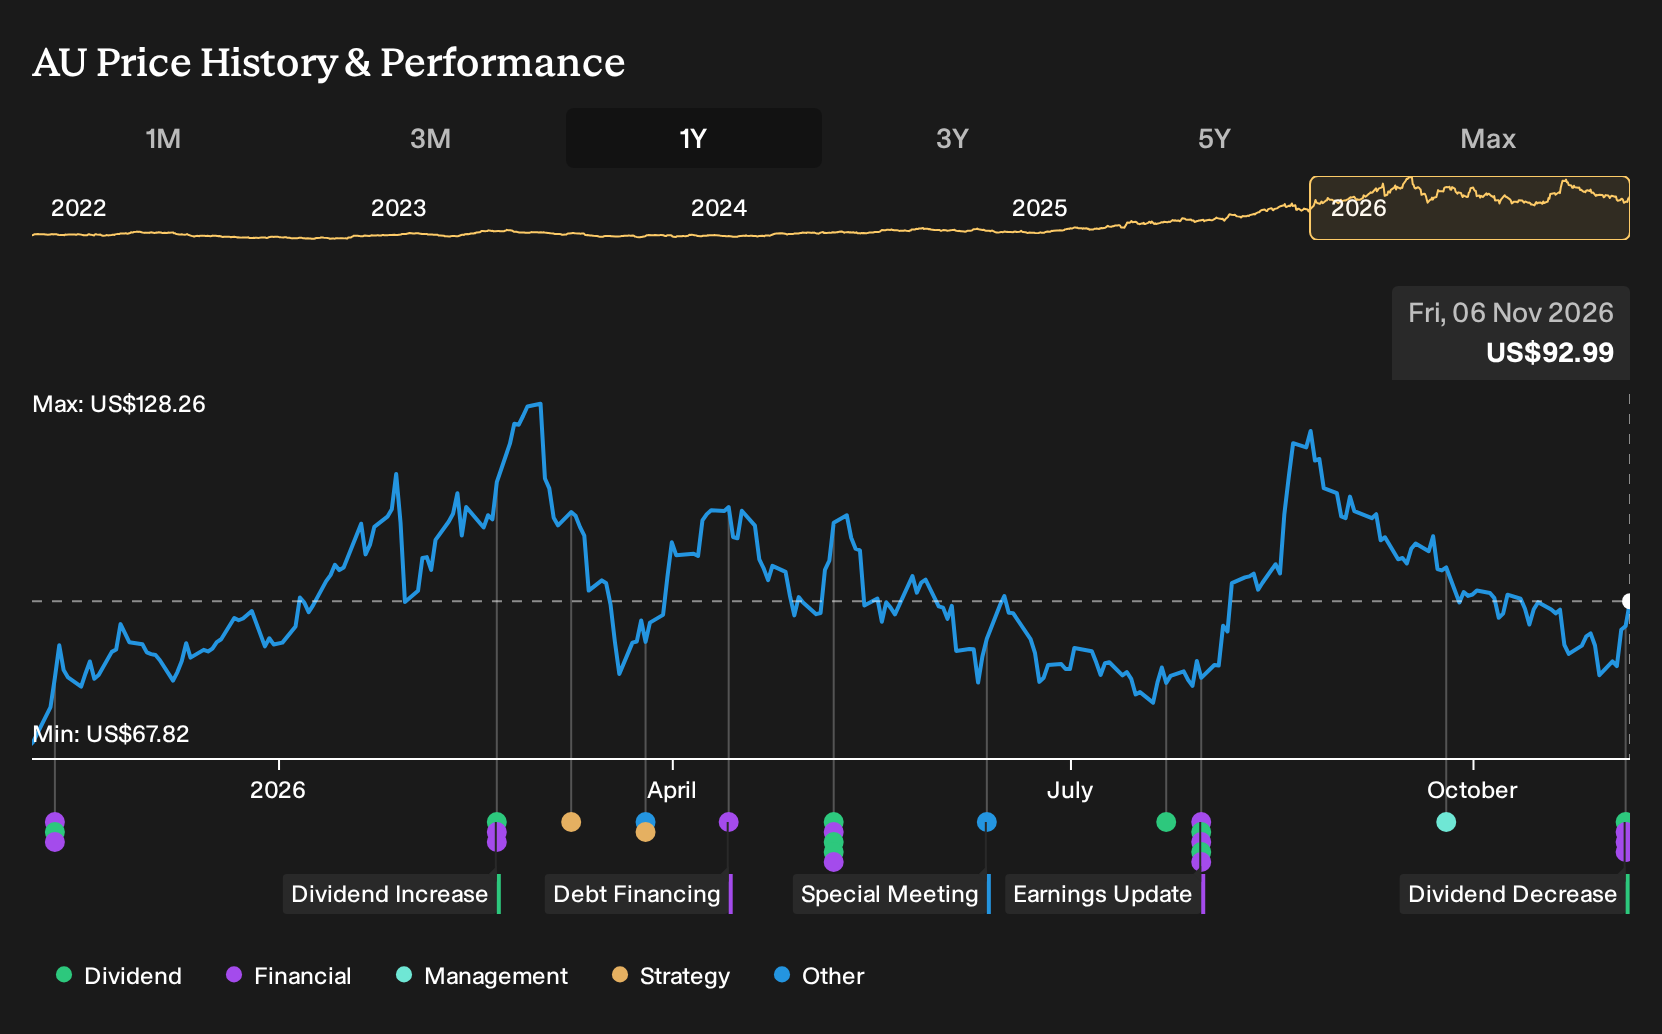
AngloGold Ashanti is one of the purest plays in this gold-focused screen, with large scale production giving direct exposure to moves in the bullion price across cycles.
AngloGold Ashanti is a global gold producer with operations across Africa, Australia and the Americas, generating about US$12.0b from metals and mining activity tied mainly to gold, and the stock carries a market value of roughly US$47.0b.
⚠️ High geopolitical exposure (Africa, South America)
What really matters from here is how one pressure in its operating footprint intersects with the next big shift in gold demand.
That pressure point is exactly where the full narrative for AngloGold Ashanti shows whether geopolitical risk is masking leverage to a sharp turn in gold demand.
Barrick Mining (TSX:ABX)
Barrick Mining is one of the flagship gold producers in this theme, with a portfolio built around large mines that give direct exposure to bullion prices through scale production and long life ore bodies.
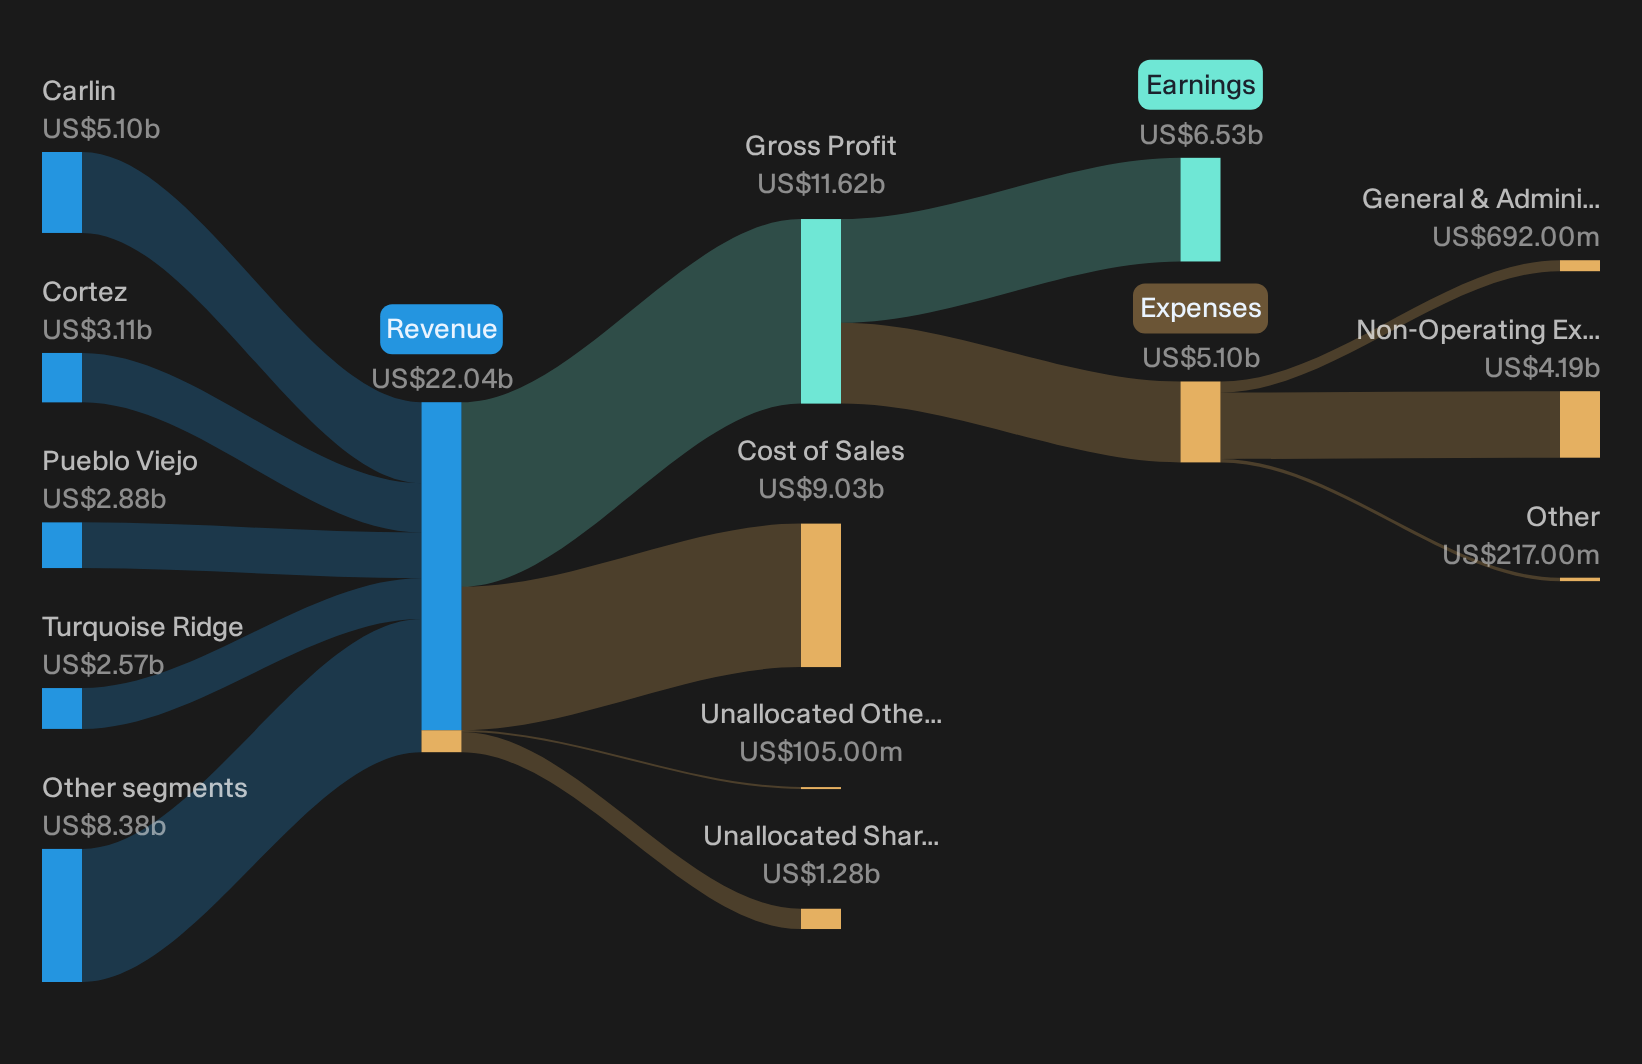
Barrick Mining is a global miner in the gold focused screen, earning about $5.1b from Carlin, $3.1b from Cortez, $2.9b from Pueblo Viejo and $2.6b from Turquoise Ridge, with other sites adding billions more. The stock carries a market value near CA$94.1b.
For investors using this screener to stay close to the metal itself rather than peripheral plays, Barrick Mining is where the gold theme becomes very tangible. Its large producing hubs and project choices can influence how sensitive its cash flows are to long term bullion moves.
Agreement with Newmont to restructure the Nevada Gold Mines joint venture, including bringing Fourmile and Newmont’s Mike and Fiberline assets into the JV and resolving historic disputes, is expected to let Barrick Mining reconfigure processing capacity, reduce ore trucking and pursue higher throughput in Nevada, which would directly affect group revenue and unit cash costs.
What happens to margins from here depends on how one unseen pressure inside that reconfigured Nevada system ultimately feeds through to cash generation.
That hidden pressure point is exactly where the full narrative for Barrick Mining shows whether Nevada’s reconfiguration is quietly accelerating Barrick Mining’s cash engine or masking fresh risks.
Wheaton Precious Metals (TSX:WPM)
Wheaton Precious Metals is the pure gold streaming play in this screen, giving you exposure to future metal production without owning or running mines directly. This makes it a central way to express a long term view on gold pricing and demand.
Wheaton Precious Metals Corp. runs a precious metal streaming model, financing miners in exchange for rights to future gold, silver and other metal output. The stock is a large cap in this theme with a market value of about CA$87.3b.
Although Wheaton Precious Metals sets out a path to lift production to around 1.2 million gold equivalent ounces by 2030 from nine growth projects, interruptions such as the substation outage at Hemlo that pushes back its throughput ramp by several months indicate that even small delays at new streams can drag on the timing of volume-driven revenue and earnings.
For gold focused investors, the key question is what happens when one crucial assumption about how quickly those future ounces arrive begins to shift.
When that timing risk starts to matter, the full narrative for Wheaton Precious Metals shows how Wheaton Precious Metals could turn delayed ounces into accelerating optionality for patient shareholders.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, early momentum and quietly dropping valuations rarely stay under the radar for long, so consider using this window while it matters and explore opportunities early.
- Explore early-stage momentum by scanning 10 elite penny stocks with strong financials that pair higher risk with balance sheets that may be stronger than many micro caps in this corner of the market.
- Track real-world AI adoption through 40 profitable AI stocks that aren't just burning cash where cash flows and profitability targets help filter out stories that rely mainly on hype rather than operating performance.
- Review income-oriented ideas with the 7 dividend fortresses that focuses on higher-yielding companies with fundamentals that support their ability to keep paying investors when sentiment shifts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com