
DiamondRock Hospitality (DRH) Posted Stronger Results, Is The Valuation Upside Already Priced In?
DiamondRock Hospitality (DRH) just posted its third quarter and nine month 2026 results, reporting higher sales, revenue, net income and earnings per share than in the same periods a year earlier.
The upbeat third quarter report lands after a strong run in DiamondRock Hospitality’s stock, with a 30 day share price return of 11.25% and a 90 day gain of 15.75%. This has contributed to a 53.95% year to date rise and a 1 year total shareholder return of 62.93% that signals building momentum rather than fading enthusiasm.
Scan how DiamondRock Hospitality compares with a curated group of hotel and real estate peers in our list of solid balance sheet and fundamentals (25 results).
DiamondRock Hospitality now appears to be a stronger hotel REIT following its latest earnings and sharp share price run. The open question is whether that improved story is already fully reflected in today’s valuation.
Most Popular Narrative: Fairly Valued
Against a last close of $14.04, the most followed narrative pegs DiamondRock Hospitality’s fair value at $14.04, which points to a share price that already lines up closely with modeled future cash flows using an 8.32% discount rate.
The multiyear plan to invest 7% to 9% of annual revenue, or about $80 million to $100 million per year, into lower intensity but ROI focused projects such as L’Auberge de Sedona and The Dagny aims to keep capital needs below peer levels while still targeting double digit EBITDA yields, which can support free cash flow and FFO per share.
See why 2 investors see DiamondRock Hospitality as 0% overvalued.
Result: Fair Value of $14.04 (ABOUT RIGHT)
Still, higher labor costs in markets like New York and tougher deal competition on hotel sales and purchases could test how durable this DiamondRock Hospitality narrative really is.
Find out about the key risks to this DiamondRock Hospitality narrative.
Another View: DiamondRock Hospitality Through A Cash Flow Lens
The share price might look roughly in line with fair value at $14.04, yet the SWS DCF model points in a different direction. On that framework, DiamondRock Hospitality trades about 38% below an estimated future cash flow value of $22.74, which flags a much larger valuation gap. That raises a simple question for investors: Is the cash flow outlook too generous, or are current expectations too low?
Look into how the SWS DCF model arrives at its fair value.
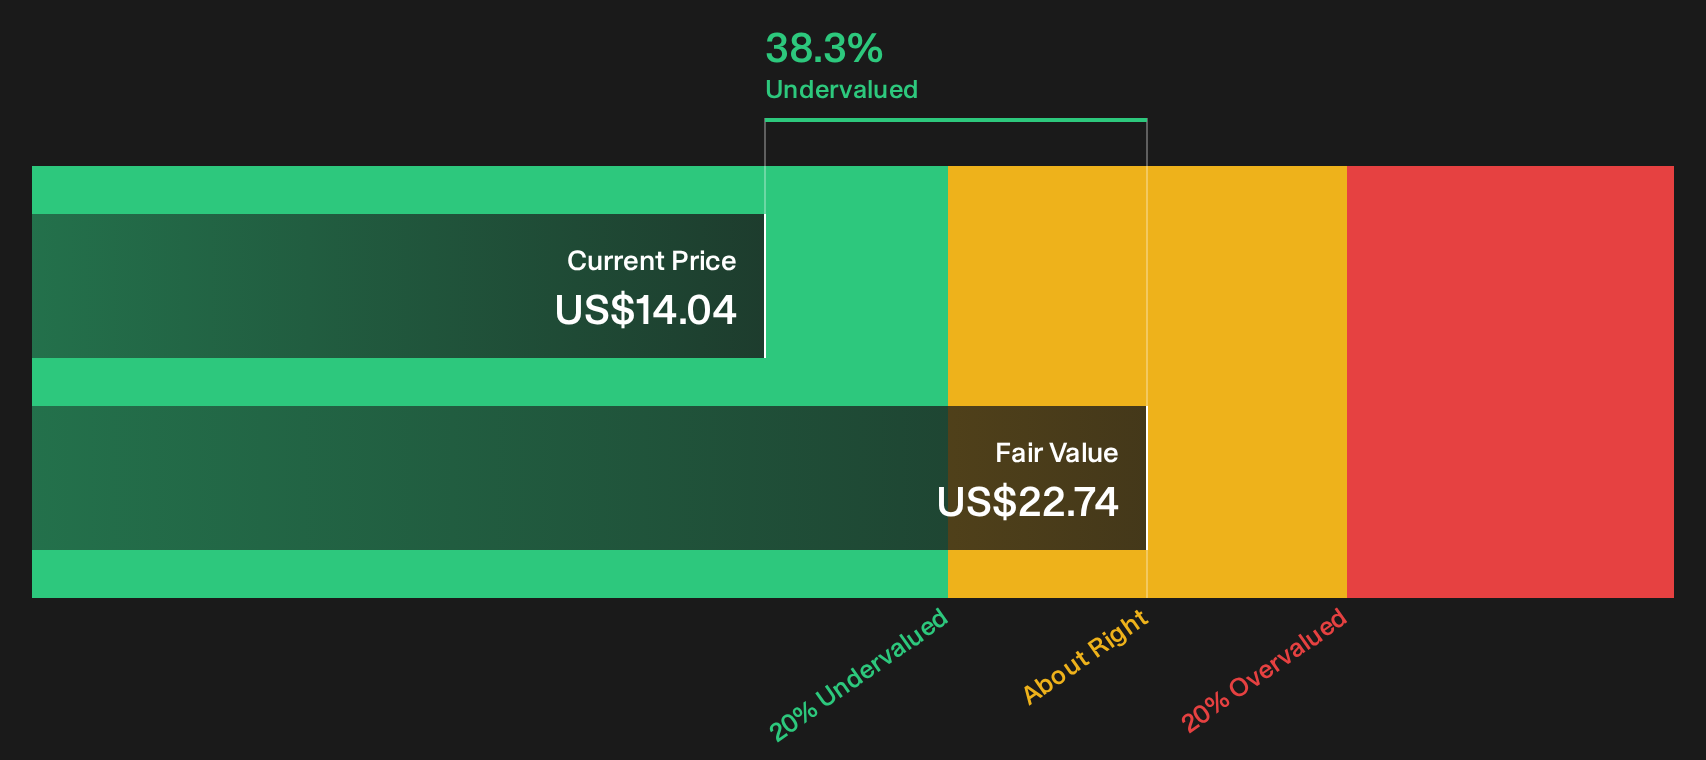
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DiamondRock Hospitality for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Momentum and valuation can point in different directions, so it pays to inspect the detail yourself and not just inherit the crowd’s mood. Move quickly, review both the upside drivers and the pressure points, then weigh DiamondRock Hospitality on your own terms using these 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond DiamondRock Hospitality?
If DiamondRock Hospitality has your attention, do not stop here. Fresh ideas often sit just outside your current watchlist, and missing them can cost real opportunities.
- Target quality at a discount by focusing on companies that combine resilient balance sheets with appealing valuations using the 36 high quality undervalued stocks.
- Build a steadier income stream by concentrating on businesses with robust payouts and higher yields through the 7 dividend fortresses.
- Dial back portfolio risk by filtering for companies with stronger financial footing via the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com