
How Investors Are Reacting To OSI Systems Stock After Earnings Growth
- OSI Systems reported first quarter fiscal 2027 revenue of US$403.47 million and net income of US$24.57 million, with both basic and diluted EPS from continuing operations higher than a year earlier.
- Management signaled continued focus on organic investment and selective acquisitions, highlighting interest only in targets that deepen market penetration or add complementary end markets.
- We will now see how OSI Systems' stronger quarterly earnings performance could influence the existing investment narrative built around backlog conversion.
Scan beyond OSI Systems and compare its acquisition led playbook with a curated 19 high quality undiscovered gems that could be building similar momentum away from the spotlight.
OSI Systems Investment Narrative Recap
To own OSI Systems, you need to believe its record backlog, government contracts, and growing service base can translate into steadier revenue and healthier profitability, even as some regions soften. The latest quarter, with US$403.47 million in sales and US$24.57 million in net income, reinforces that the operating engine is still converting orders into earnings.
The near term swing factor remains how quickly that US$1.9b pipeline turns into delivered Security and RF projects, given prior delays in Mexico and the Middle East. Execution risk sits on the other side. If logistics or export timing slip again, backlog conversion, margins, and confidence in the fiscal 2027 guidance range could be tested.
The first quarter fiscal 2027 earnings print is the clearest reference point for this news. Revenue reached US$403.47 million, compared with US$384.62 million a year earlier, and both basic and diluted EPS from continuing operations were higher. For you, that is a concrete check on whether OSI Systems is tracking against its modest full year revenue and non GAAP EPS guidance.
This result feeds directly into the main catalysts investors watch: backlog drawdown, service growth, and RF project delivery. It also sits against a mixed risk backdrop that includes high debt, Security softness in Mexico, and geopolitical disruptions. The quarter does not remove those pressures, although it shows the broader portfolio still producing higher earnings while management pursues targeted acquisitions and buybacks.
OSI Systems' analyst narrative points to forecast revenue of US$2.2b and projected earnings of US$229.2 million by 2029, anchored on an assumed 6.9% yearly revenue growth rate and an earnings rise of about US$74.5 million from US$154.7 million today.
Uncover why OSI Systems' fair value indicates a 42% potential upside to its current price, which could narrow quickly.
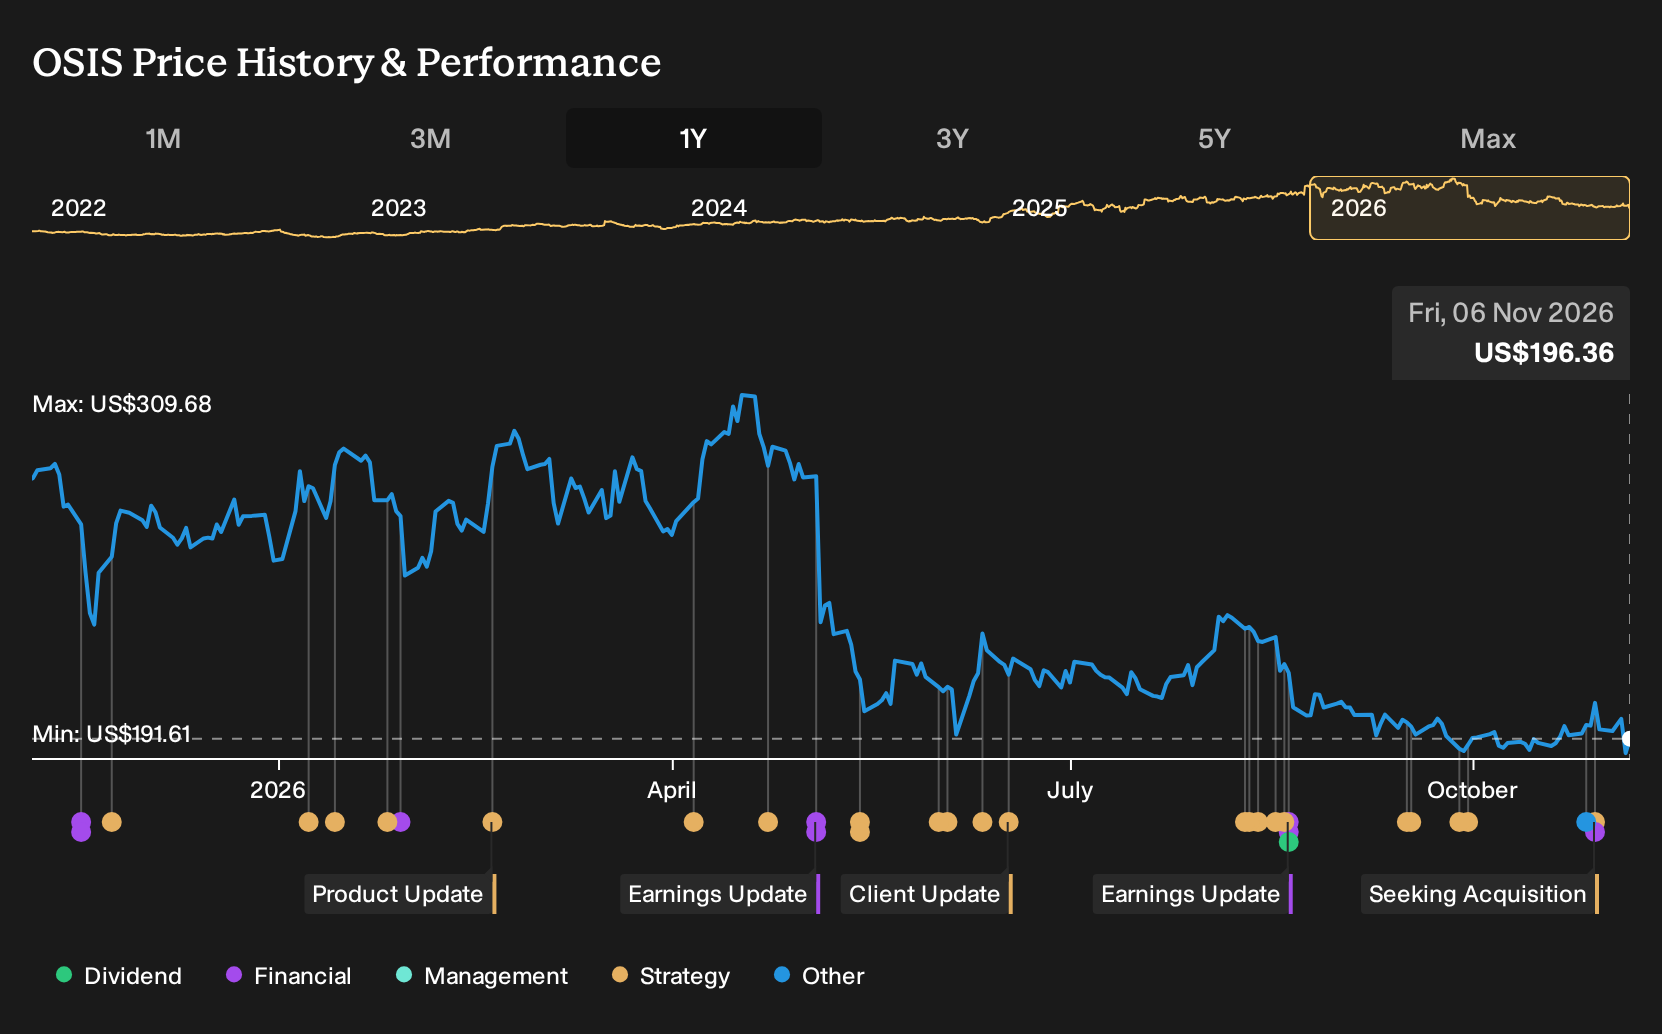
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$85 to US$278 per share for OSI Systems, which shows how far apart private investors can be. When you set those pre-news opinions against record backlog, planned acquisitions, and geopolitical delivery risks, you are looking at very different potential journeys. Explore the full spread before taking a stance.
Explore 2 other OSI Systems fair value estimates, including one that suggests as much as 57% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent analysis.
- A great starting point for your OSI Systems research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for OSI Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OSI Systems' overall financial health at a glance.
Looking for more investment ideas beyond OSI Systems?
If this OSI Systems update has sharpened your thinking, use that same mindset to scan the wider market. The Simply Wall St Screener can help you focus on companies that better fit your risk, income, or value preferences.
- For income focused investors who want to aim for steadier cash flows, review a curated 7 dividend fortresses that have yields above 5% and an emphasis on durability.
- If capital preservation and balance sheet strength sit higher on your list, start with a list of solid balance sheet and fundamentals (25 results) and see which businesses pair low leverage with resilient fundamentals.
- When your goal is to reduce downside risk rather than chase every rally, use a 31 resilient stocks with low risk scores that concentrates on companies with more conservative risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com