
How Investors Are Reacting To PayPal Stock Raised Earnings Outlook
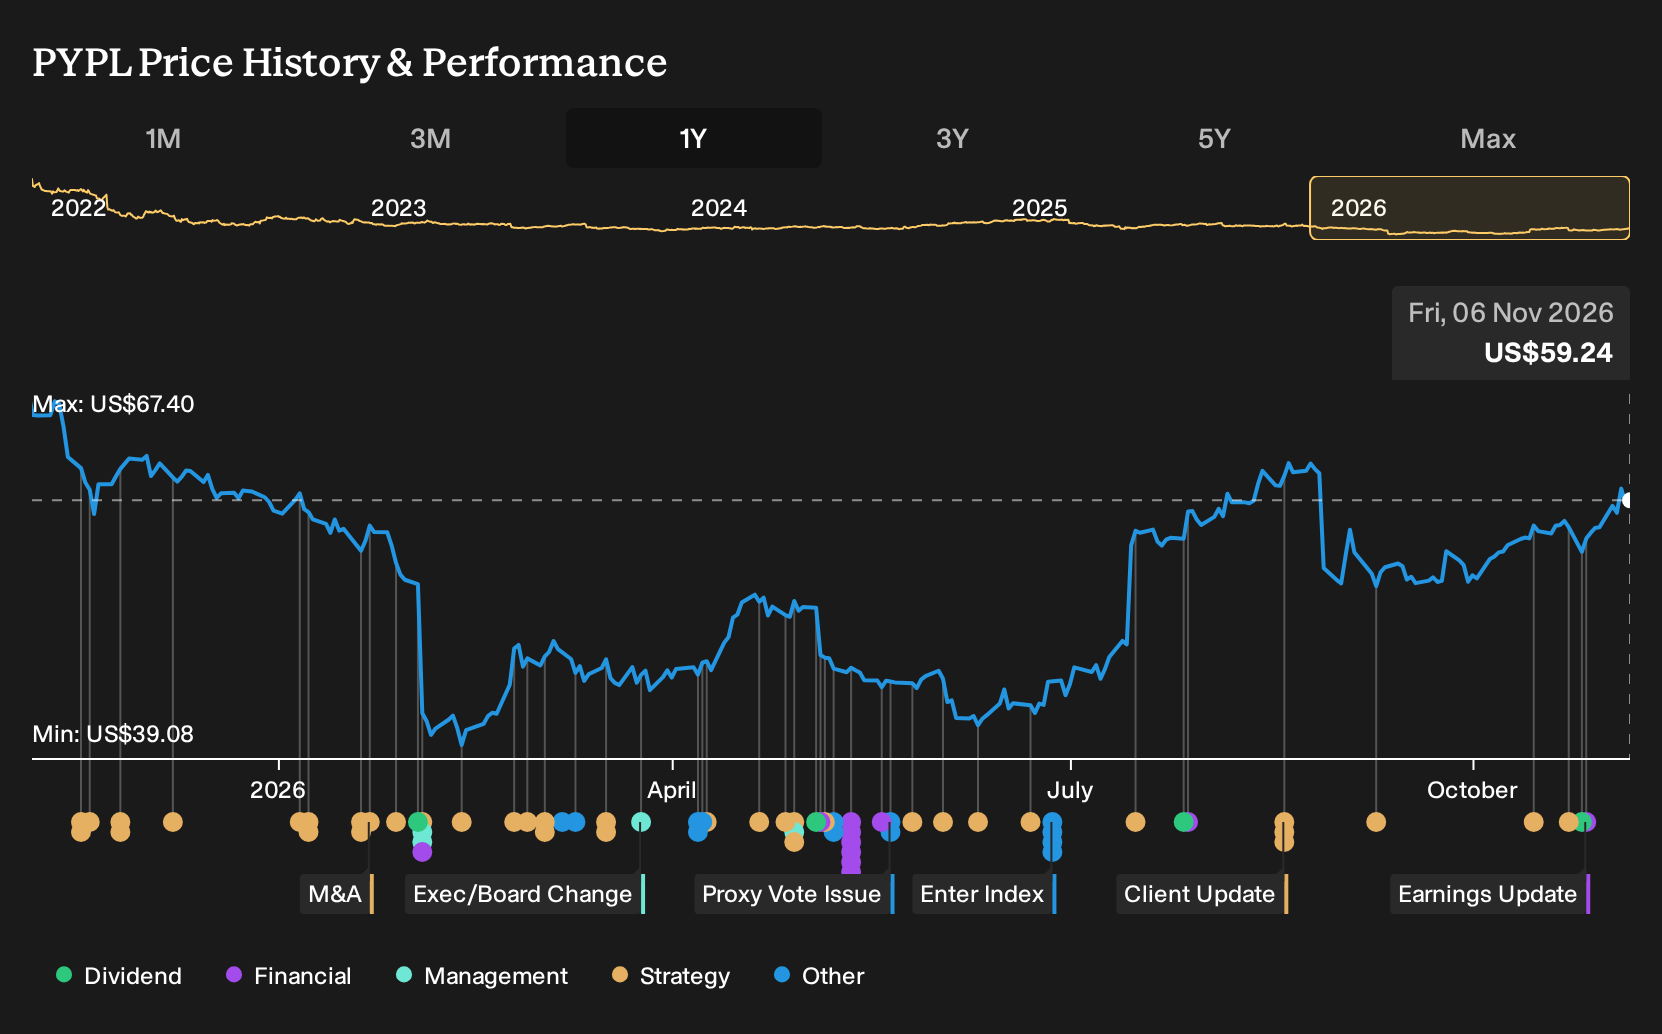
- PayPal Holdings reported third quarter 2026 basic EPS from continuing operations of US$1.26, slightly below the prior year, and affirmed a US$0.14 quarterly dividend payable on December 24, 2026.
- Management raised the 2026 adjusted EPS outlook while describing 2027 as an investment year funded by ongoing cost savings and growth spending.
- We will look at how PayPal Holdings' investment narrative is shaped by the raised 2026 earnings outlook alongside tighter cost control.
Scan how PayPal Holdings compares with other payment and fintech stocks that also balance earnings power with reinvestment by reviewing our curated list of 36 high quality undervalued stocks.
PayPal Holdings Investment Narrative Recap
To own PayPal Holdings, you need to believe the payment platform can keep shifting usage into Venmo, Braintree and newer flows while holding the line on profitability. The higher 2026 adjusted EPS outlook leans on cost savings and operating discipline rather than surging revenue, so the near term story is mostly about execution, not expansion.
The key near term catalyst is management proving that heavier use of lower take rate products does not erode transaction margins faster than expenses come out. The biggest risk remains exactly that mix shift. If cross border headwinds in Europe or pricing pressure persist, the benefit of the large cost program could feel muted.
The clearest recent data point for this catalyst comes from the third quarter report where basic EPS from continuing operations was US$1.26, slightly below last year, while adjusted EPS and Pay with Venmo volumes were stronger. That mix shows how much the investment case turns on monetising Venmo and new payment flows, not just defending branded checkout.
For you as a shareholder, this update matters because it pairs raised 2026 adjusted EPS guidance with a plan to treat 2027 as an investment year funded by ongoing savings. The dividend affirmation at US$0.14 per quarter signals a commitment to return some cash, but the heavier focus still sits on reinvesting in products, technology and the broader consumer ecosystem.
What The Current Analyst Framework Implies For PayPal Holdings
PayPal Holdings' current analyst framework ties the cost program and product push to fairly modest growth assumptions rather than a breakneck expansion story. Consensus forecasts point to revenue increasing about 4.3% per year over the next few years, with profit margins easing from 14.4% today to 12.3% by 2029 as mix shifts further toward Venmo, Braintree and other lower take rate flows.
On earnings, the group of analysts expects PayPal Holdings to move from roughly US$4.9b in earnings today to about US$4.7b by 2029. This represents a decrease of US$0.2b, even as earnings per share land near US$6.4 because share count is projected to decline around 7% a year. Those same models lean on 2029 revenues of about US$38.7b and a P/E of 10.3x on that US$4.7b earnings figure, compared with about 9.2x today and an industry multiple near 16.4x for US diversified financial stocks.
PayPal Holdings' narrative projects US$38.7b revenue and US$4.7b earnings by 2029, which lines up with analyst models that build in 4.3% yearly revenue growth and an earnings decrease of about US$0.2b from roughly US$4.9b today.
Uncover why PayPal Holdings' fair value points to a 4% potential downside to its current price, a premium that may not be sustainable.
Exploring Other Perspectives
Some of the most optimistic analysts focus on PayPal Holdings' cost savings program as the real swing factor. Before this earnings update, the bullish group was modelling about US$40.6b of revenue and US$6.4b of earnings by 2029, a far stronger outcome than consensus. Your view can differ widely, so treat this quarter’s numbers as a fresh prompt to recheck those assumptions and explore multiple angles before deciding what feels realistic to you.
Explore 23 other PayPal Holdings fair value estimates, including one that suggests as much as 120% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PayPal Holdings research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for PayPal Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PayPal Holdings' overall financial health at a glance.
Looking For More Ideas Beyond PayPal Holdings?
Once you have a view on PayPal Holdings, it often helps to widen the lens and see how other businesses stack up on quality, income and risk using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting in your returns, consider higher yielding opportunities through our 7 dividend fortresses.
- For a focus on durable balance sheets and cleaner fundamentals, filter for companies that pass tight financial health checks using the list of solid balance sheet and fundamentals (25 results).
- If you are hunting for under the radar prospects with strong business metrics, scan through the 19 high quality undiscovered gems and see what catches your eye.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com