
Will Earnings Miss Change Edison International (EIX) Stock Narrative
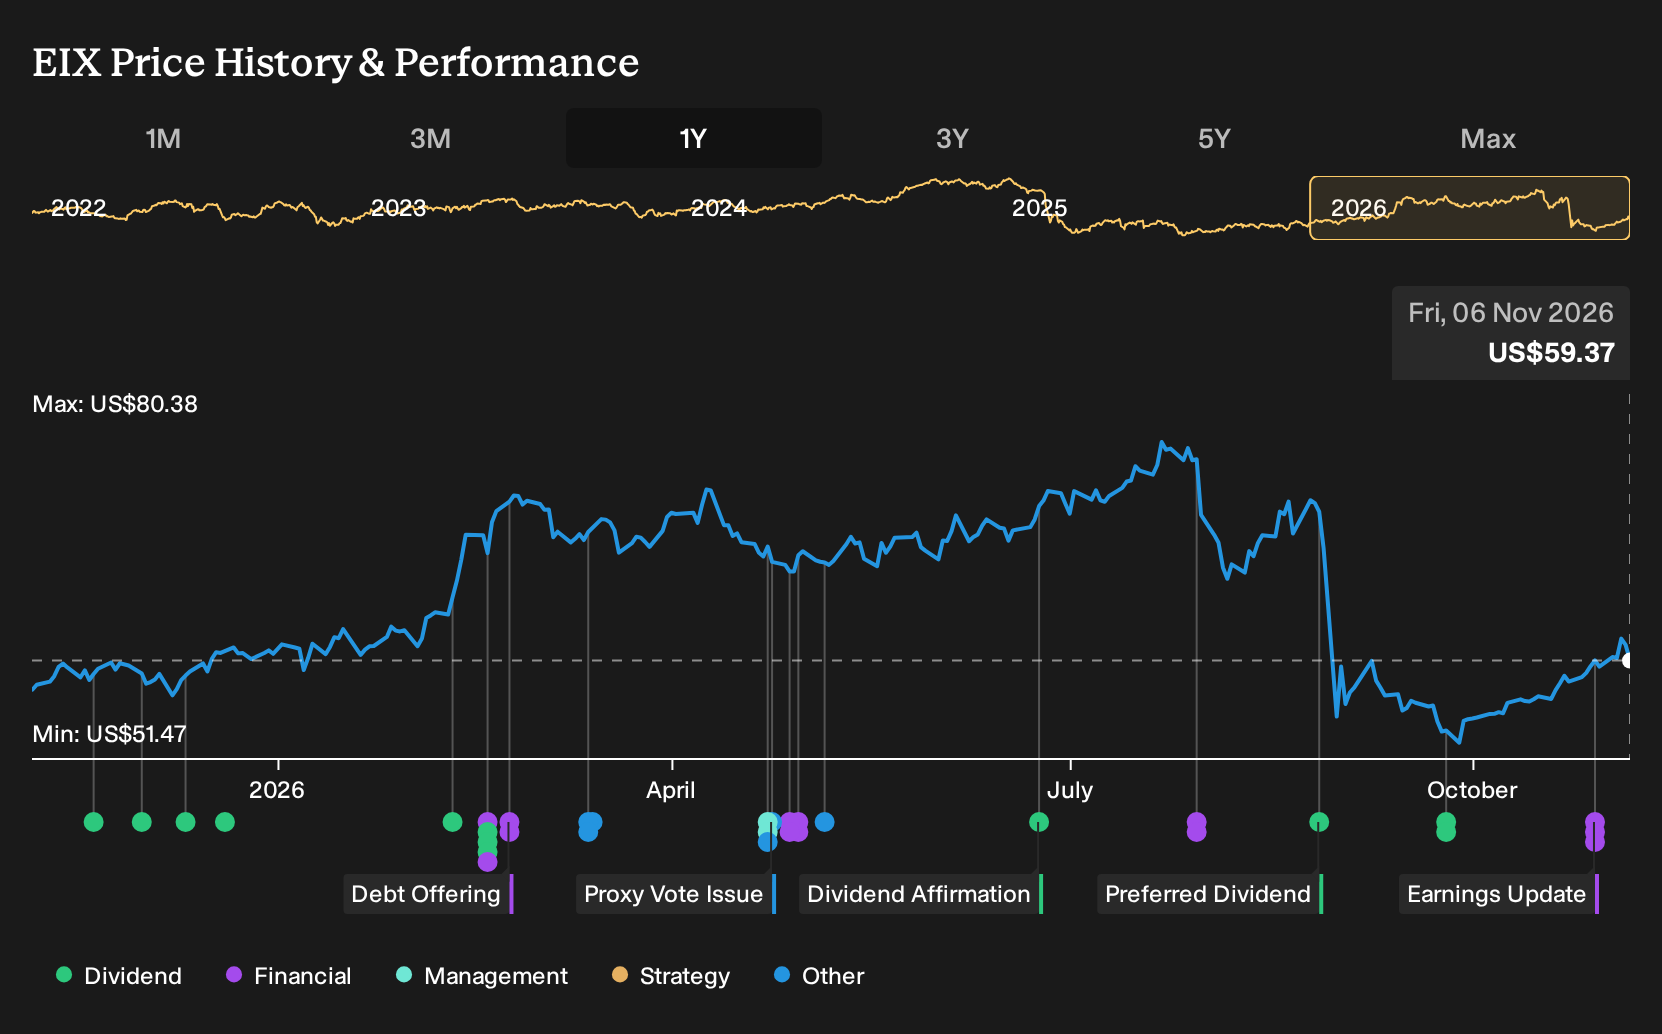
- Edison International reported third quarter 2026 sales of US$4,886 million and net income of US$724 million, with earnings per share from continuing operations below the prior year, and narrowed its full year 2026 basic EPS guidance range to US$5.66 to US$5.96.
- The utility also filed a shelf registration tied to its dividend reinvestment plan and continues to process Eaton Fire claims through its Wildfire Recovery Compensation Program. Together, these developments highlight both its capital access needs and ongoing wildfire related obligations.
- Next, the focus turns to how Edison International’s softer earnings and trimmed 2026 guidance may reshape the longer term investment narrative.
Scan how other regulated utilities are priced for growth and risk compared to Edison International by reviewing our curated list of 41 power grid technology and infrastructure stocks.
Edison International Investment Narrative Recap
To stay comfortable owning Edison International, you need to believe the regulated grid investment story can keep moving forward while wildfire exposure and higher financing needs remain manageable. The latest quarter showed softer sales and earnings, and the slightly trimmed 2026 EPS guidance signals less cushion around near term performance than before.
The key near term catalyst is continued execution on the US$38b to US$41b 2026 to 2030 capital plan, including grid hardening and clean energy build out. The biggest risk remains wildfire liability and related regulation. The Eaton Fire link and claims volume underline that this risk is still very active, so the earnings miss feels operationally relevant rather than a one off.
The Eaton Fire Wildfire Recovery Compensation Program is the announcement most tightly connected to this earnings update. Edison International has already seen more than 17,600 claims submitted, with over US$1.1b in offers extended and thousands of claimants paid, which ties directly into wildfire related cost visibility and timing.
For you as a shareholder, this matters because wildfire cash outflows sit alongside a large capital program and interest costs that are not comfortably covered by earnings. Program uptake, settlement pace and any gap between insured or recoverable amounts and total obligations will feed straight back into how credible that 2026 EPS guidance range and balance sheet resilience look over the next year.
Edison International's narrative projects US$20.9b revenue and US$2.7b earnings by 2029. That path assumes revenue growth of 2.4% per year and an earnings decline of US$1b from current earnings of US$3.7b.
Uncover why Edison International's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view around Edison International focuses heavily on wildfire cash costs rather than future grid projects. The most bearish analysts were already assuming 2029 revenue of about US$19.8b and earnings near US$2.5b, with only an 8.1x P/E. That is a much more cautious story than consensus, and this latest earnings miss plus guidance trim may prompt you to recheck both sets of forecasts.
Explore 4 other Edison International fair value estimates, including one that suggests as much as 29% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Edison International research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Edison International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edison International's overall financial health at a glance.
Looking for more investment ideas beyond Edison International?
If this Edison International update has sharpened how you think about risk, income and balance sheet strength, use that same lens across the market with a few focused stock lists built to save you time.
- For investors who care most about capital preservation and steadier profiles, start with a 31 resilient stocks with low risk scores that already screen well on resilience.
- If you want to tilt toward value with quality fundamentals, use the 36 high quality undervalued stocks to scan for businesses where price and financial strength look more aligned.
- For readers hunting for future leaders that are not widely followed yet, check out a 19 high quality undiscovered gems that pair solid metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com