
Learn Why The Bull Case For Enterprise Products Partners Stock Could Change Following Earnings Beat
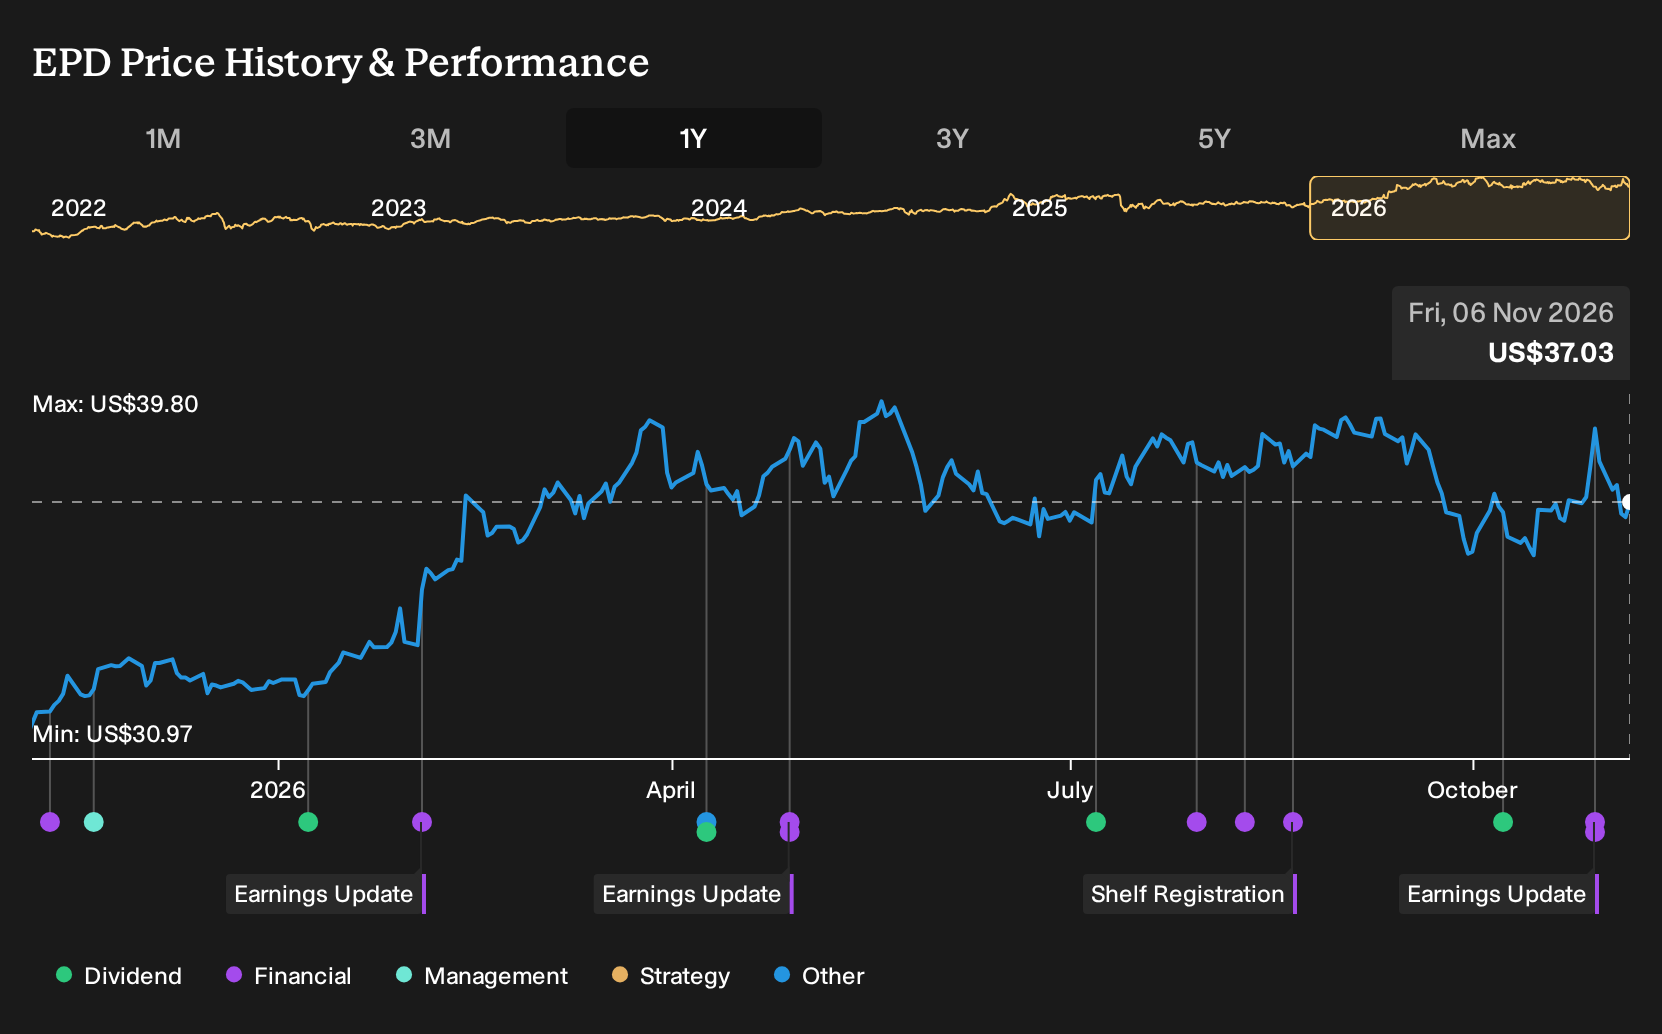
- Enterprise Products Partners reported higher third quarter 2026 sales of US$17,948 million and net income of US$1,624 million, with diluted EPS from continuing operations at US$0.75. The company also reported increased pipeline and marine terminal throughput across key product streams.
- The combination of stronger earnings, higher transported and exported volumes, and ongoing multi billion dollar expansion projects highlights how Enterprise Products Partners is leaning on large scale midstream infrastructure to support fee based cash generation.
- We will look at how Enterprise Products Partners' investment narrative is influenced by this stronger third quarter earnings and volume performance.
Enterprise Products Partners Investment Narrative Recap
To own Enterprise Products Partners, you need to be comfortable with a fee based midstream model that leans on high utilization of pipelines, plants, and export docks. The latest quarter, with US$17,948 million in sales and US$1,624 million in net income, supports that volume driven story in the near term. The key short term swing factor remains execution on bringing new Permian processing and fractionation projects up to expected throughput.
On the risk side, the bigger issues are still operational reliability at the PDH units and whether the heavier growth capex for 2026 and 2027 earns strong returns. The third quarter volume gains and earnings do not remove those concerns, but they help show the existing system is absorbing more barrels and molecules while those projects are being built.
The most relevant update for this earnings print is the operating data through September 30, 2026. Pipeline transportation volumes for NGLs, crude, petrochemicals, and refined products reached 8,865 MBPD in the quarter, with natural gas volumes at 22,695 BBtus/d and equivalent system throughput at 14,837 MBPD. Marine terminal activity was 2,535 MBPD. That combination indicates Enterprise Products Partners is moving more product through its network.
For investors watching catalysts, that higher throughput sits directly against the raised capex plan of roughly US$2.9b to US$3.4b in 2026 and around US$3b in 2027. Stronger system activity can help support the case that new Permian plants, fractionation, and LPG export expansions have a real volume base to draw from, while the main operational watchpoint remains avoiding unplanned PDH downtime that could chip away at petrochemical earnings.
Enterprise Products Partners' current earnings are about US$6.2b, and analysts expect earnings to reach roughly US$7.6b by 2029, which is an increase of about US$1.4b. The same forecasts point to revenues of about US$67.7b by 2029 that would require around 5.0% yearly top line growth.
Discover why Enterprise Products Partners' fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between US$41.42 and US$90.51 per unit, which is a wide band for Enterprise Products Partners. Those private estimates pre date the October earnings and throughput update. Some Community members focus on PDH reliability and heavy capex risk, while others lean on volume driven catalysts and invite you to weigh these competing stories.
Explore 2 other Enterprise Products Partners fair value estimates, including one that suggests it could be worth just $41.42.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Enterprise Products Partners research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enterprise Products Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Enterprise Products Partners' overall financial health at a glance.
Looking For More Investment Ideas Beyond Enterprise Products Partners?
Once you have formed a view on Enterprise Products Partners, it can help to compare it with other opportunities that share similar qualities such as income durability, balance sheet strength, or re rating potential. The Simply Wall St Screener is built for exactly that kind of side by side comparison.
- If income reliability is high on your list, scan a curated set of 7 dividend fortresses that focus on sizeable yields supported by underlying fundamentals.
- If capital preservation and resilience matter more, sort through a 31 resilient stocks with low risk scores to see which businesses have historically paired measurable quality with lower risk scores.
- If you want to widen the opportunity set, cast a wider net across 19 high quality undiscovered gems that combine solid fundamentals with less crowded investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com