
Sat Out Urban Outfitters' Rally? Here Is The Bet Holders Made
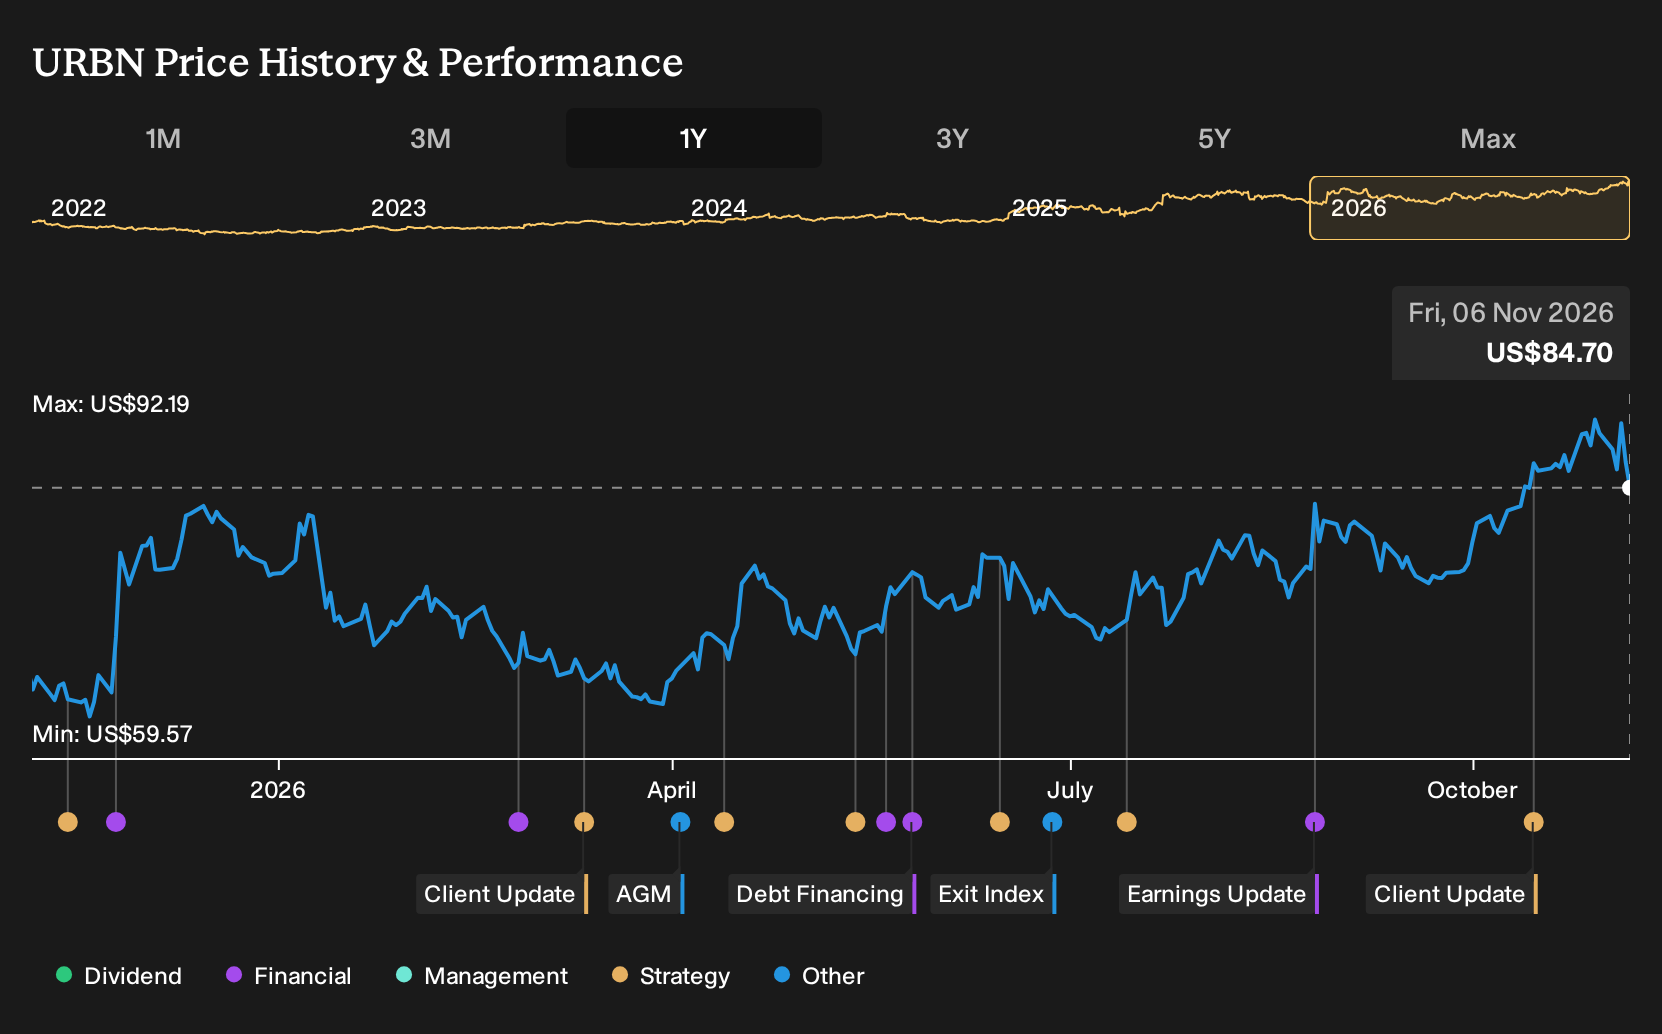
If Urban Outfitters was on your watchlist rather than in your portfolio, the result may sting. Investors who held Urban Outfitters over the past year are up 32.6%, including dividends. The move arrived after analysts were split in late 2025 between a bullish view built on stronger e-commerce and Nuuly growth, and a cautious stance focused on margin pressure. If you rewind to that disagreement, which side of the revenue and profit margin assumptions looked more realistic based on what was already on record?
The easy part of this move is behind Urban Outfitters. Zero in on 36 high quality undervalued stocks for companies trading below our estimates.
The Two Urban Outfitters Narratives Investors Lived With
The shares cost US$62.53 at the start of the period, and Urban Outfitters sat between two competing stories that both sounded plausible.
On the optimistic side, the bull Narrative pointed to a Fair Value of US$79.67 as the price those upbeat assumptions implied. That view relied on 7.1% annual revenue growth and Nuuly subscriber momentum, with a future P/E of 16.5x assumed if omnichannel and youth spending held up.
The bear Narrative argued for a Fair Value of US$47.28 based on more restrained expectations. It used 2.2% annual revenue growth and a 6.8% profit margin assumption, with concern that higher inventory and store expansion costs might squeeze earnings even if sales progressed.
What The Evidence Did To The Urban Outfitters Argument
Urban Outfitters posted Q2 2027 revenue of US$1,661.9 million and net income of US$240.7 million, with net margin at 14.5% versus 9.6% in Q2 2026. That margin level sat well above both the bull and bear assumptions and arrived alongside record quarters where Nuuly and Free People growth featured heavily. The evidence leaned toward the optimistic case.
The useful takeaway is simple. When a thesis hinges on margin and new engines like Nuuly, track reported net margin alongside segment updates rather than only watching P/E or headline sales elsewhere.
What Urban Outfitters' Recent Run Already Prices In
Urban Outfitters now trades at US$84.7 after a 32.6% gain over the past year, while the selected Narrative’s Fair Value sits below the current price based on its own assumptions.
This view depends on whether Nuuly, FP Movement and the wider Free People group can scale profits fast enough to offset cost pressure and markdown risk. A buyer today effectively leans on that outcome. The question is how the fuel surcharge headwinds and Anthro markdowns in the Narrative reshape that bet.
"Although Nuuly is currently growing revenue with several hundred thousand subscribers and new automated facilities planned to support up to about 1.2 million subscribers, the roughly 70 basis point quarterly gross margin headwind from fuel surcharges risks absorbing much of the expected operating leverage from lower logistics cost per order. This could leave group operating income short of what is implied by current subscriber and revenue targets."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Looking Past Urban Outfitters
Urban Outfitters sits where fashion, e-commerce and logistics meet your closet. Nearby, another company is wrestling with a similar puzzle.
Instead of clothing, it connects shoppers and merchants across a broad online marketplace. The same rails also move digital payments, savings and credit between them.
Funding those loans burns cash upfront, long before earnings fully surface. That approach blurs the line between recurring expense and long-term investment.
If its lending engine stays both durable and disciplined, shareholder outcomes could eventually diverge sharply from what headline cash flow suggests today.
That argument has a Narrative and a number behind it. → See the company one Narrative values 59% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com