
Why HCG Fell Even As Sales Rose
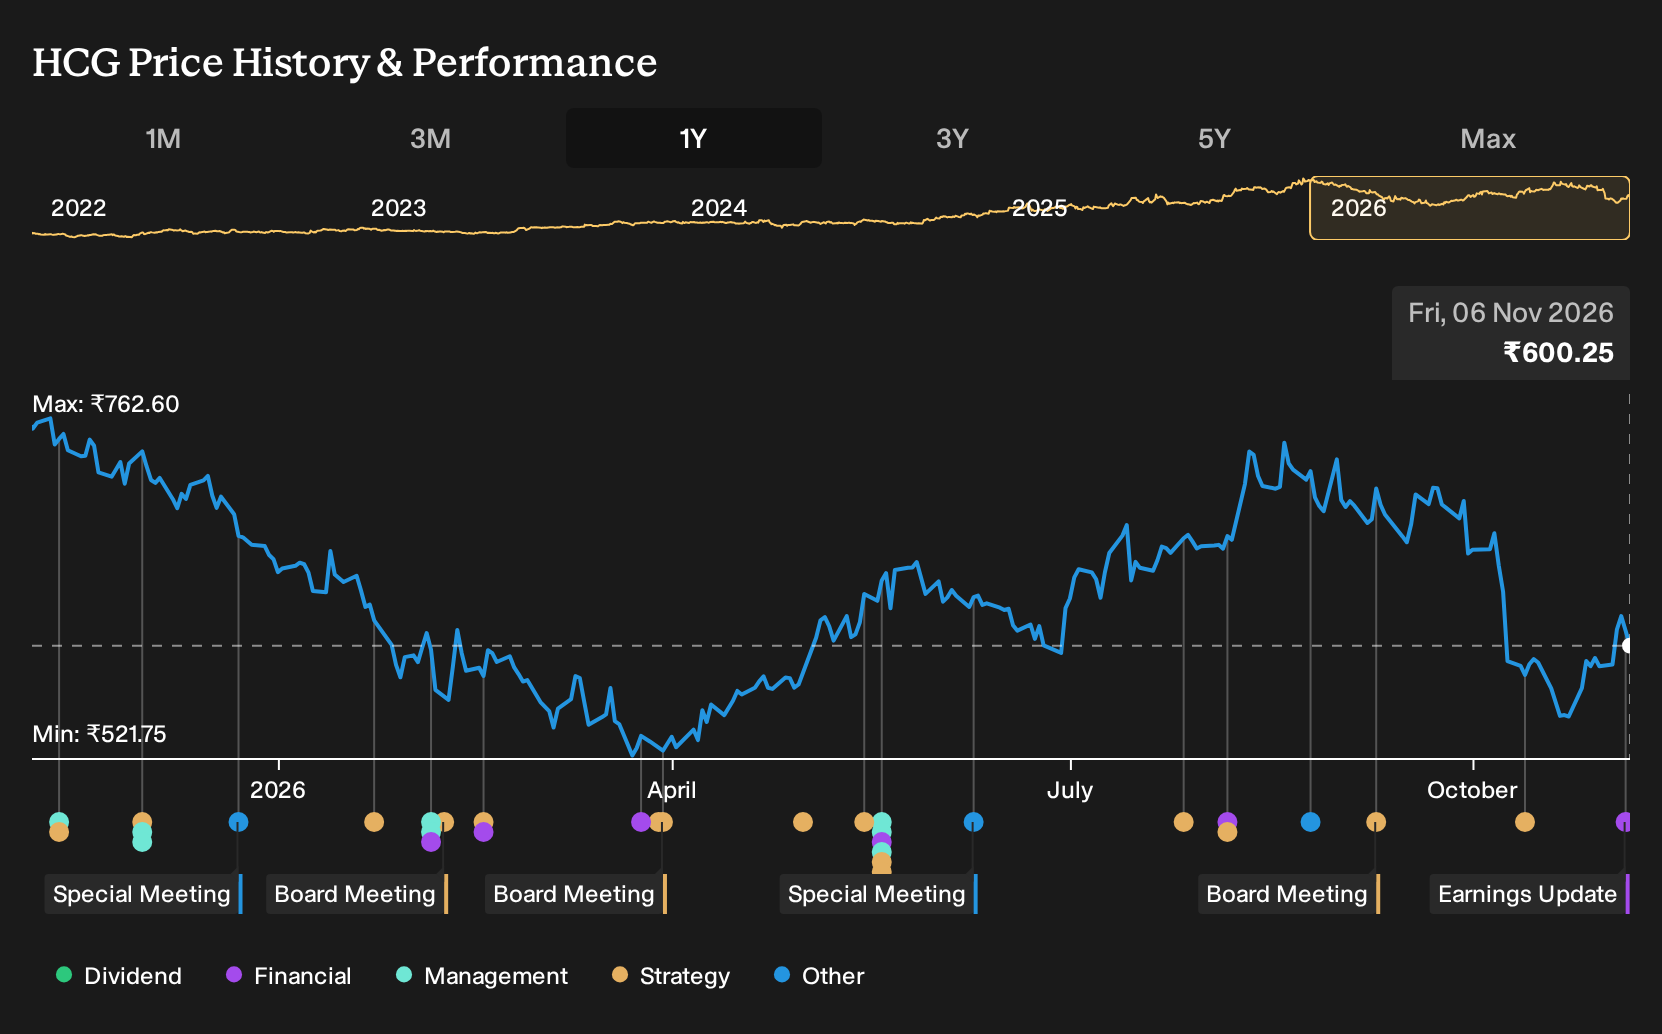
If you bought into HealthCare Global Enterprises on the promise of precision oncology leadership, digital traction and KKR-backed expansion, the payoff so far has been uncomfortable. Investors who held HealthCare Global Enterprises over the past year are down 20.5%, including dividends. If that holding period started when bullish and cautious analyst cases were both on record, what did those original assumptions miss about rising capex, high P/E expectations and the pressure that later squeezed net margins?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
HealthCare Global Enterprises has already moved. See which of 218 high quality undervalued stocks still trade below our estimates.
The Two HealthCare Global Narratives Investors Had To Weigh
The shares cost ₹755 at the start of the period, and anyone buying HealthCare Global Enterprises then had to choose which story felt more believable.
The bullish narrative put fair value at ₹824. It leaned on KKR capital and expertise, assuming revenue could compound at 17.7% a year and that profit margins might rise from 1.6% to 9.4%, supported by aggressive precision oncology investment and rapid digital traction.
The more cautious view saw fair value at ₹693. That case still assumed 14.8% annual revenue growth and margins rising to 8.3%, but highlighted risks from high debt, seasonality in earnings and potential disruption as KKR reshaped the business.
What The Results Changed For The HealthCare Global Story
The clearest new fact was operational. HealthCare Global Enterprises reported total revenue of ₹6,468.5m in Q2 2026 and ₹7,337.1m in Q2 2027, while net income fell from ₹162.7m to ₹47.9m and net margin slipped from 2.5% to 0.7%. Higher sales alongside thinner profitability challenged the bullish case that assumed a smooth path to much higher margins.
The main lesson is simple. When a thesis leans on margin expansion, watch net income and net margin together, quarter by quarter, to see whether extra capacity and capex are translating into stronger profitability or just higher scale on weaker returns.
What HealthCare Global Investors Are Being Asked To Believe Now
HealthCare Global Enterprises now trades at ₹600, with the selected Narrative arguing that fair value sits above that quote based on oncology-focused expansion, revenue mix change and tighter balance sheet guardrails.
A buyer today would need to believe the planned bed additions, oncology technologies and payer mix shift genuinely support the margin and earnings path described in the Narrative for the fall to signal opportunity rather than warning.
"The plan to add around 1,000 beds by FY30, with about 600 from brownfield projects and 400 from greenfield hospitals in locations such as Whitefield and Maharashtra, is set to expand capacity beyond the current base and can lift revenue and operating leverage."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Another Way To Read HealthCare
HealthCare Global shows how hard specialty treatment economics can be for operators. It also highlights what reliable reimbursement and cost control mean to hospital-heavy models.
Step sideways and you find a different fulcrum. Instead of running cancer centres, this other business designs health plans and coordinated care programs.
Its customers rely on value-focused contracts, data tools and pharmacy services to keep medical bills controlled. Those programs steer complex patients into more structured, closely monitored care.
If this shift toward managed costs and sharper incentives spreads further, companies that organise care rather than deliver it could gain new importance.
One Narrative has already put a figure on it. → Uncover the company trading 18% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com