
Should Raised EPS Guidance Require Action From STERIS Stock Investors?
- STERIS reported past second quarter and six month results to September 30, 2026, with higher sales and earnings per share, reaffirmed revenue growth guidance for fiscal 2027, put new debt facilities in place, and filed an omnibus shelf registration for multiple security types.
- The combination of raised EPS guidance, a planned Xodus Medical acquisition that is expected to add to margins and earnings, and a restructuring plan aimed at cost savings highlights management focus on both growth and efficiency at STERIS.
- The next area of attention will be how STERIS's higher EPS outlook could reshape the longer term investment narrative that investors are using.
STERIS Investment Narrative Recap
To own STERIS, you need to be comfortable with a healthcare equipment and services business that leans heavily on recurring chemistries and sterilization contracts, and is actively investing in new capacity. The raised EPS outlook, the Xodus Medical deal, and the restructuring plan all fit within that same theme. The near term catalyst remains execution on higher earnings guidance, supported by steady procedure volumes and margin discipline.
The biggest risk still lies in execution rather than a single headline. Tariff costs, large capital projects in North Carolina and Ohio, and restructuring charges could pressure cash generation if timing or costs slip. The latest moves do not erase those concerns, but they also do not materially change the core risk profile.
A key recent data point is the new US$1.6 billion revolving credit facility that runs to 2031, paired with a delayed draw term loan of up to US$500 million tied to the Xodus Medical acquisition. For a shareholder, this matters less as a technical financing detail and more as an indication that STERIS has significant committed liquidity behind its expansion plans.
Both the revolver and the term loan include leverage and interest coverage covenants, along with limits on additional indebtedness and liens. That creates a formal framework around balance sheet risk. It also means investors may want to monitor how STERIS paces share buybacks, dividends, and large projects against these obligations, since future cash flow and operating consistency will be central to maintaining this capital structure.
STERIS' analyst narrative points to forecast revenue of US$7.3b and consensus earnings of US$1.2b by 2029, based on an assumed 6.6% yearly increase in revenue and a projected rise in earnings from US$805.0m today to US$1.2b, an uplift of about US$395m from current earnings.
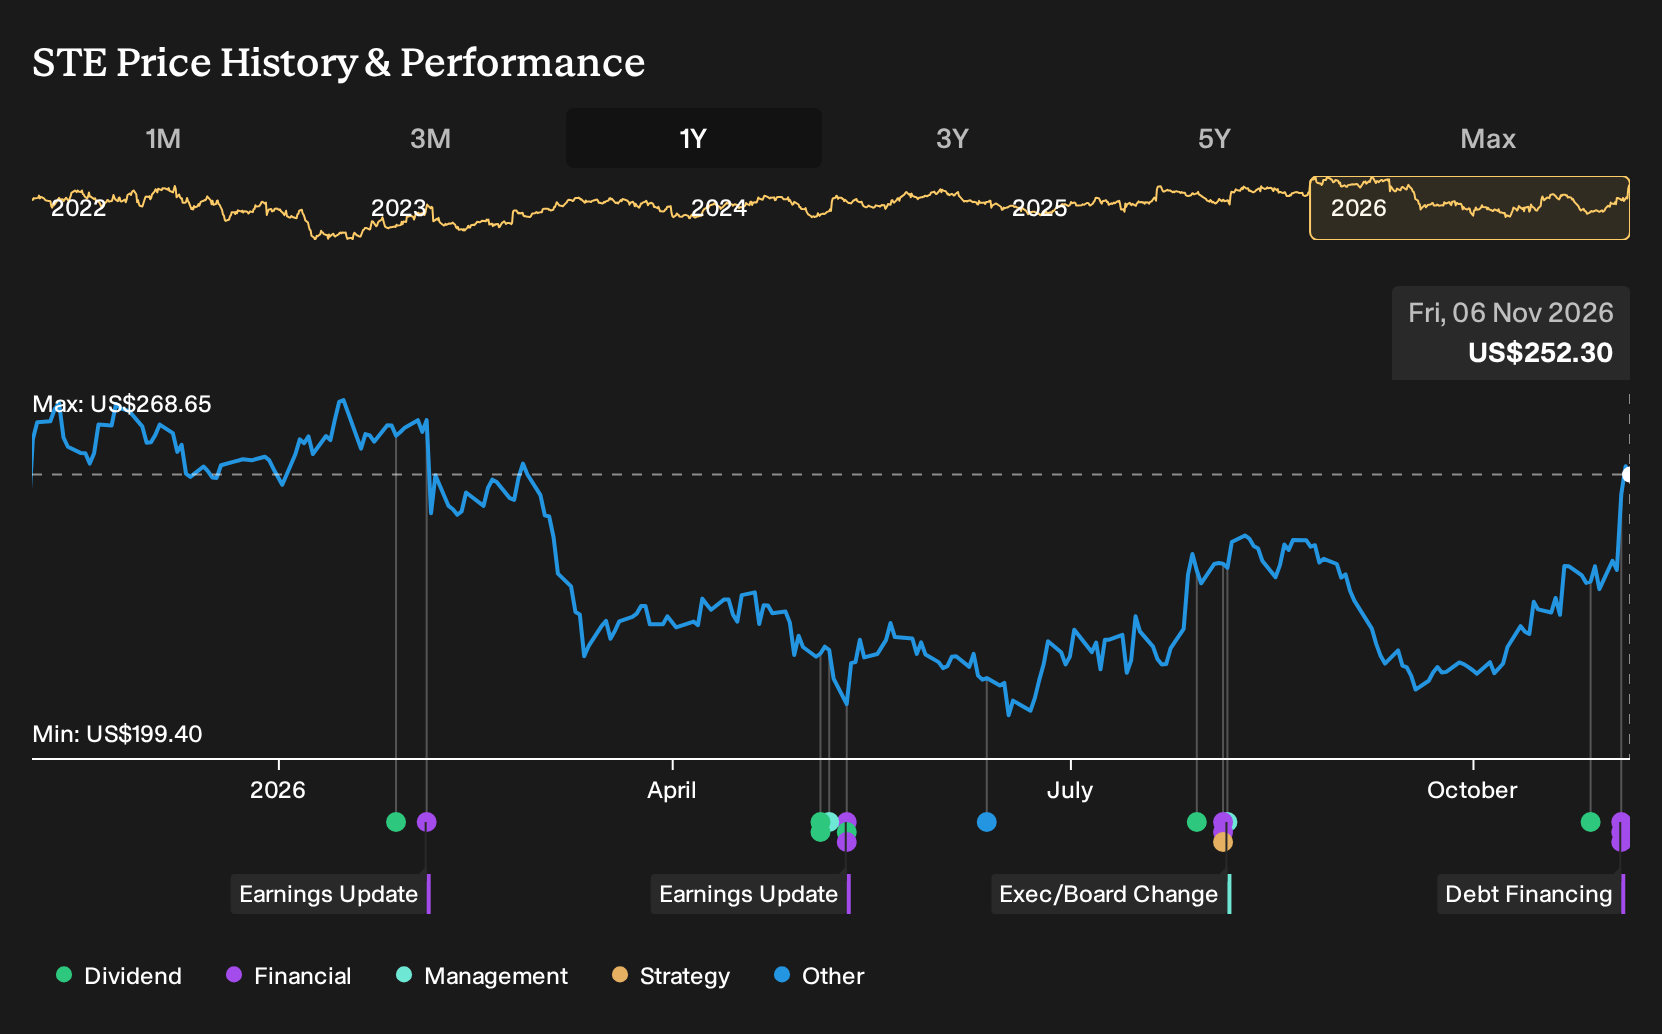
Uncover why STERIS' fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$205 and US$263 a share, with one view anchoring the low end and another leaning toward the upper range. You are weighing those retail forecasts against tariff and project execution risks on STERIS, as well as fresh financing capacity from the new credit facilities and shelf registration. Investor opinions can differ widely, so it can help to review several of these community viewpoints before deciding how today’s price lines up with your own expectations.
Explore another STERIS fair value estimate, including one that suggests it could be worth as much as $263.12.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your STERIS research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for STERIS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate STERIS' overall financial health at a glance.
Looking For More Investment Ideas Beyond STERIS?
If the STERIS story has sharpened your thinking about cash flow quality, balance sheet strength, and long term earnings power, it can be useful to line it up against other opportunities using a consistent framework.
- Prefer businesses where the market price looks conservative relative to quality. Scan a curated set of 36 high quality undervalued stocks that share similar fundamentals.
- Value resilience and capital preservation. Compare STERIS with a 31 resilient stocks with low risk scores that screens for companies with steadier risk profiles.
- Hunting for fresh opportunities off the beaten path? Use a 19 high quality undiscovered gems to spot lesser known stocks with strong underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com