
What Waste Connections Stock's 2026 Outlook Raise Means For Shareholders
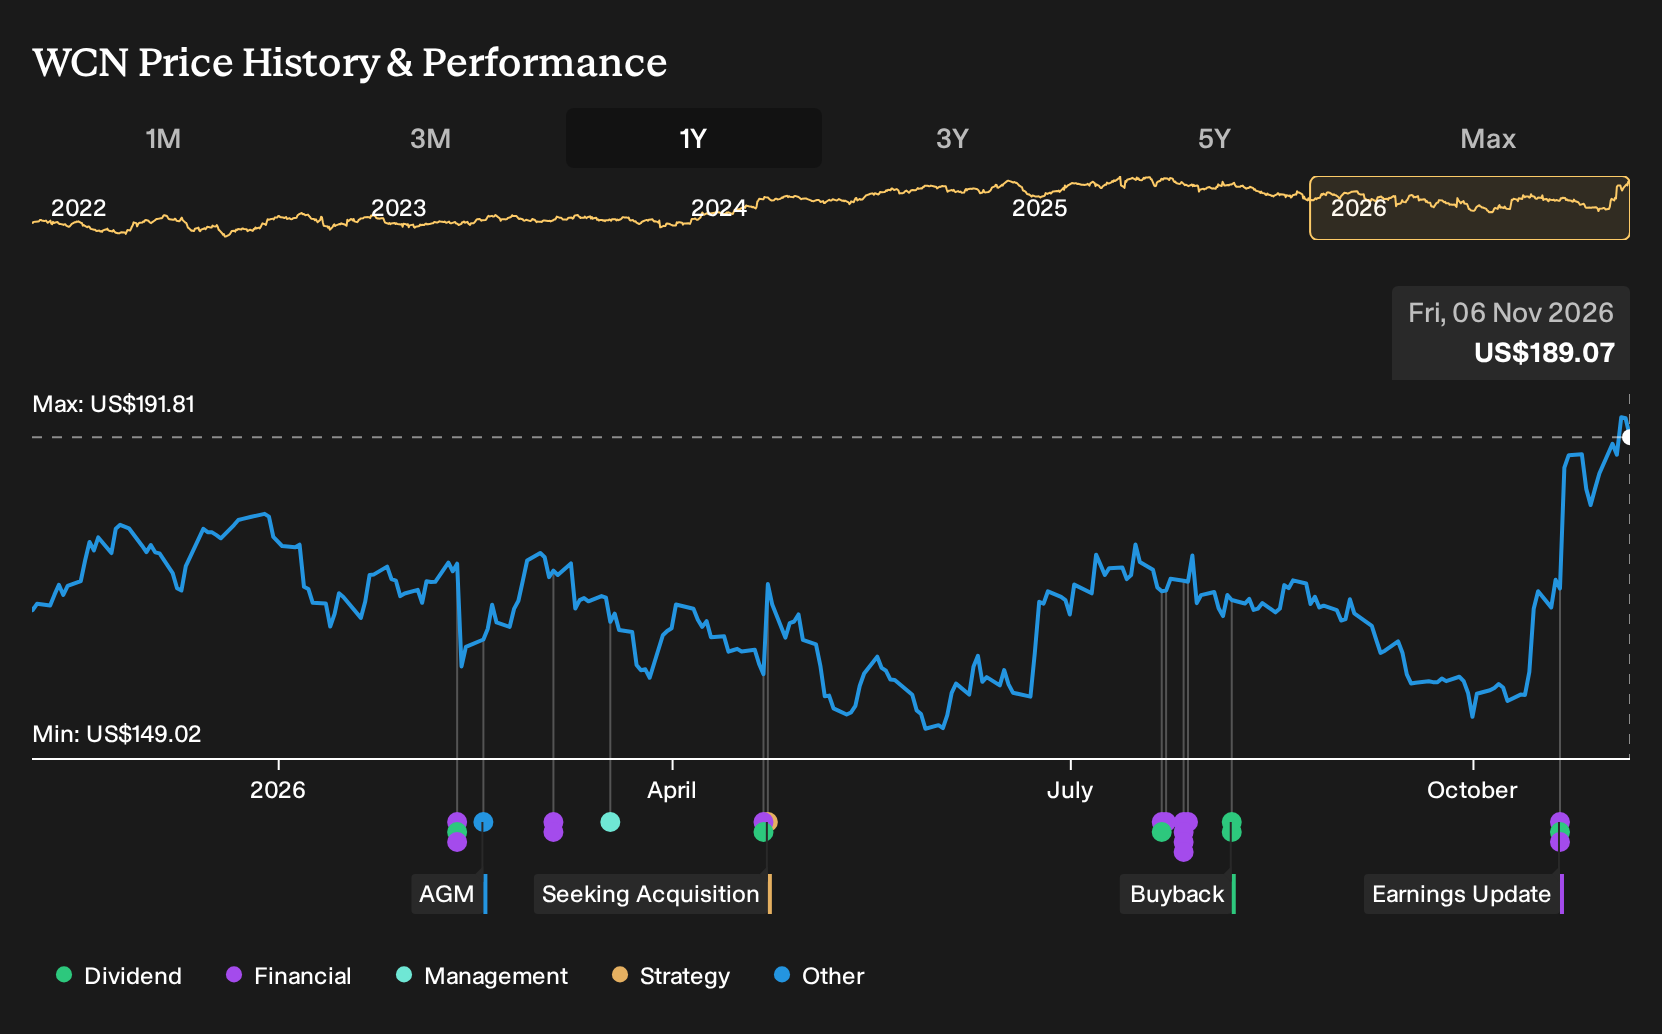
- Waste Connections recently raised its 2026 outlook after highlighting strong profit per employee, supported by ownership or operation of 114 landfills and ongoing tuck in acquisitions.
- The update underscored how control of landfill assets, disciplined pricing and acquisition driven expansion are central to Waste Connections' earnings power and cash generation plans.
- Next, the focus shifts to how Waste Connections' upgraded 2026 outlook, anchored on landfill control, may reshape its broader investment narrative.
Scan beyond Waste Connections and identify other waste and infrastructure players pursuing similar asset heavy, cash flow focused expansion using our hand picked list of solid balance sheet and fundamentals (25 results)
Waste Connections Investment Narrative Recap
To own Waste Connections, you need to believe that control of 114 landfills, tight pricing and steady tuck in deals can keep supporting earnings and cash generation, even when collection volumes are soft. The raised 2026 outlook leans on that view. It reinforces the idea that pricing tools, employee productivity and landfill leverage remain the key near term drivers.
The main short term catalyst is whether Waste Connections can keep expanding margins while fuel, labor and remediation costs pull the other way. Chiquita Canyon spending, fuel inflation and execution on AI and routing projects still matter most on the risk side. The latest outlook upgrade does not erase those pressure points, but it suggests they are currently manageable.
The most relevant recent update is management’s 2026 outlook raise, backed by higher profit per employee and continued landfill centric expansion. That guidance rests on disciplined core pricing, tuck in acquisitions and improving net income and cash flow, even with some volume softness. For you, the question is whether those levers can offset ongoing headwinds.
Operationally, the outlook lift highlights three practical catalysts: first, price discipline supported by AI tools that help retention and rate quality; second, integration of US$100 million of acquired annualised revenue and exclusive franchises that are still ramping; and third, the gradual shift of renewable natural gas projects and Chiquita remediation from heavy spend toward cleaner free cash flow after 2026, assuming costs track the existing ranges.
Waste Connections’ analyst narrative points to revenues of US$11.8b and earnings of US$1.7b by 2029, based on an assumed 6.0% yearly revenue growth rate. That path implies earnings rising by about US$600m from US$1.1b today to the 2029 consensus level.
Uncover why Waste Connections' fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on slower AI and digital rollout at Waste Connections. The most cautious analysts were pencilling in revenue of about US$11.5b and earnings of US$1.6b by 2029, slightly below consensus. That is a more restrained story, and it shows how sharply expectations can differ before this latest outlook upgrade is fully digested.
Explore 2 other Waste Connections fair value estimates, including one that suggests it could be worth just $182.54.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Waste Connections research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Waste Connections. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waste Connections' overall financial health at a glance.
Looking For More Ideas Beyond Waste Connections?
If this Waste Connections update sharpened your thinking about asset heavy, cash flow focused businesses, you can apply that same lens across the wider market. The Simply Wall St Screener lets you filter for balance sheets, earnings profiles and payout policies that match the kind of profile you want to research next.
- For investors who care most about capital strength and resilience, start with a curated 31 resilient stocks with low risk scores that already clear a balance sheet quality bar.
- If income is your priority, widen your watchlist with a hand picked set of 7 dividend fortresses that combine yield with supporting fundamentals.
- When you want to go beyond the usual large caps, explore a focused pool of 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com