
What Bears Saw Before China Unicom (Hong Kong) Slid
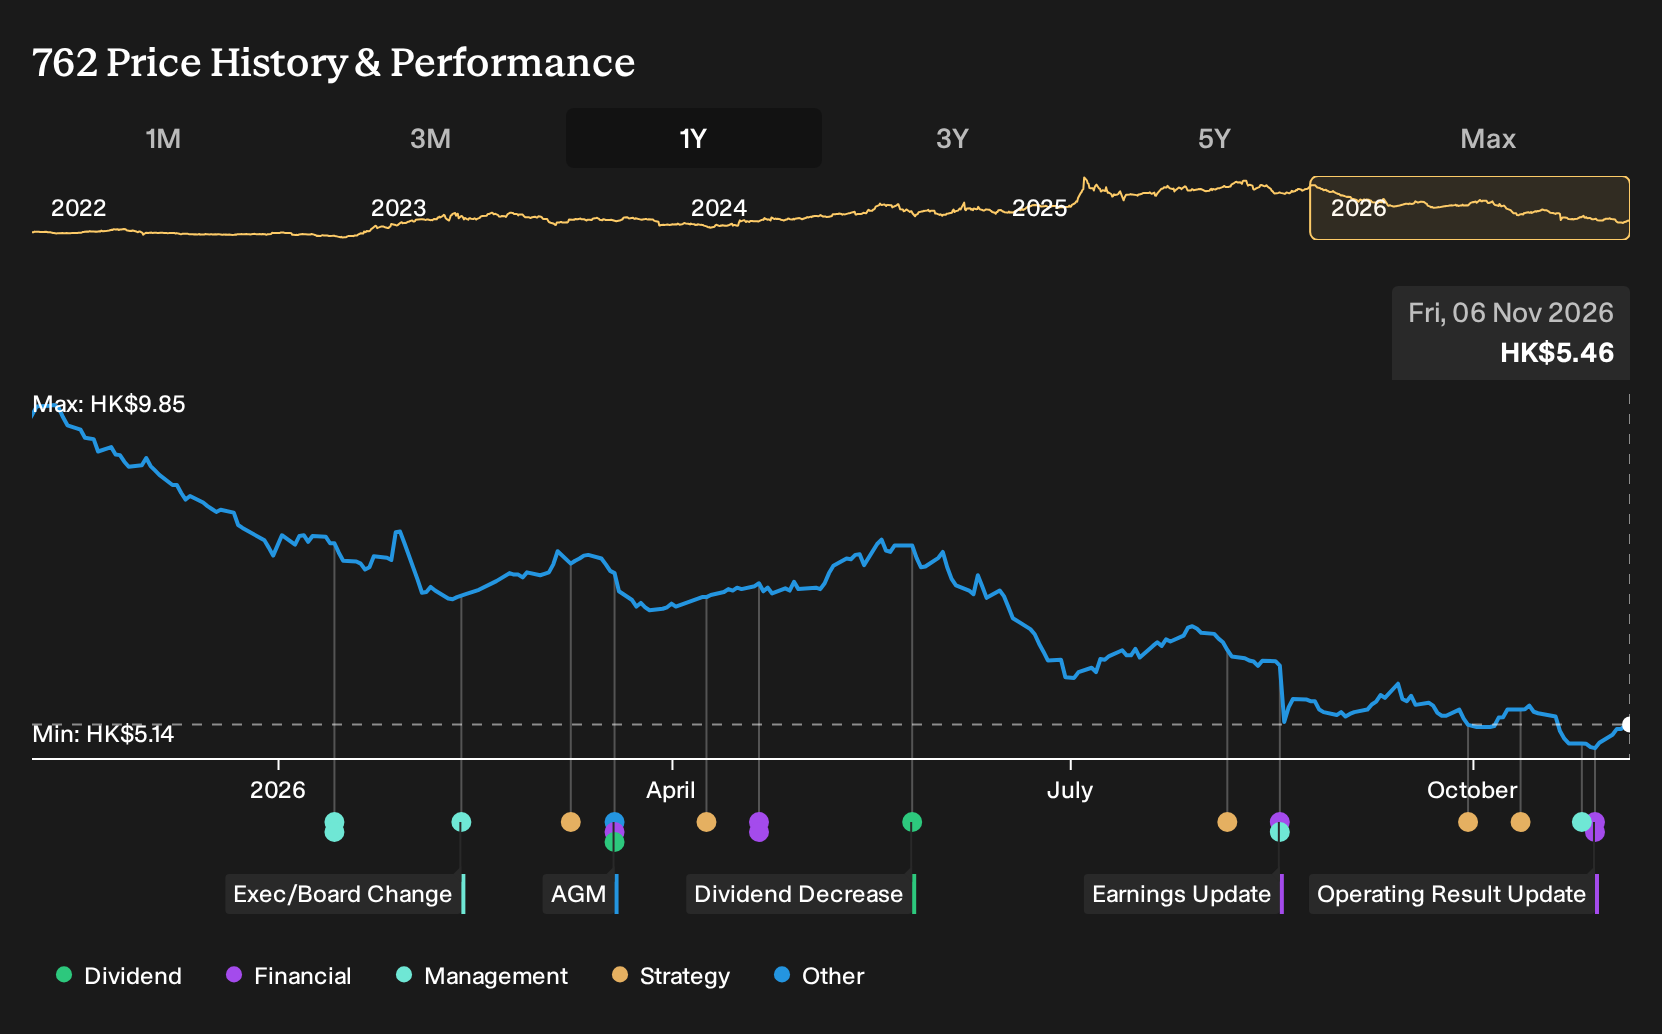
If you backed the growth story around China Unicom (Hong Kong), 5G-A rollouts and industrial IoT momentum, the past year has been a harsh reality check. For China Unicom (Hong Kong) shareholders, the loss over the past year was 43.4%, including dividends. If you had bought on the 2025 bullish case of rising cloud revenue, higher margins and a richer future P/E, what exactly did that thesis miss about execution risks, state influence and capital intensity?
China Unicom (Hong Kong) is not the only name tied to this theme. Zero in on 52 AI infrastructure stocks and compare how each one is priced.
The Two Stories Around China Unicom (Hong Kong) Back Then
The shares cost HK$9.72 at the start of the period, so anyone looking at China Unicom (Hong Kong) had to decide which story felt more realistic.
The bullish view pointed to a Fair Value of HK$10.97, essentially the price implied if growing digital services delivered better profits. That script leaned on assumptions for revenue growth of 3.3% a year and profit margins rising from 5.4% to 6.0% by 2028.
The cautious camp worked off a Fair Value of HK$9.21, a lower implied price based on more restrained expectations. This side focused on slowing domestic demand, continued heavy capex for 5G and 6G, and only modest margin improvement to 5.6% by 2028.
What The Results Changed For China Unicom (Hong Kong)
China Unicom (Hong Kong) did grow total revenue from CNY 92,783m in Q3 2025 to CNY 93,283m in Q3 2026, which gave the bullish digital services story some support. Profit told a different story. Net income excluding extra items fell from CNY 5,516m to CNY 3,812m and net margin slipped from 5.9% to 4.1%. The evidence supported the cautious case.
The key assumption that was tested here was margin expansion. When assessing any telecom, track net income and net margin alongside top-line growth to check whether new digital products are actually turning into better profitability.
What Today's China Unicom (Hong Kong) Price Already Assumes
China Unicom (Hong Kong) now trades at HK$5.46, well below where the share sat a year ago. The selected Narrative places its Fair Value above that level and leans on computing power, AI centric services and cloud workloads as the differentiator.
At this price, you are testing one core idea. The assumption is that disciplined capex into computing infrastructure converts into higher quality cash generation over time.
"Bullish analysts expect China Unicom to turn its computing power, AI centric services, and Unicom Cloud into a larger share of revenue over time, while using 5G, 5G A, and 10G broadband coverage to support above sector growth in digital services."
One Narrative disagrees with today's price. → See where this Narrative says China Unicom (Hong Kong) should trade
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 39% below our estimate - turns active ownership in electrification and data assets into fee-based exits.
- Company 2 - 42% below our estimate - rolls out cash recycling ATMs and branch-in-a-box systems for banks.
- Company 3 - 49% below our estimate - scales an asset light hotel network while selling higher margin lifestyle retail products.
Those are three of them. See the full list of 221 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com