
Will Better Earnings Change CenterPoint Energy Stock Narrative
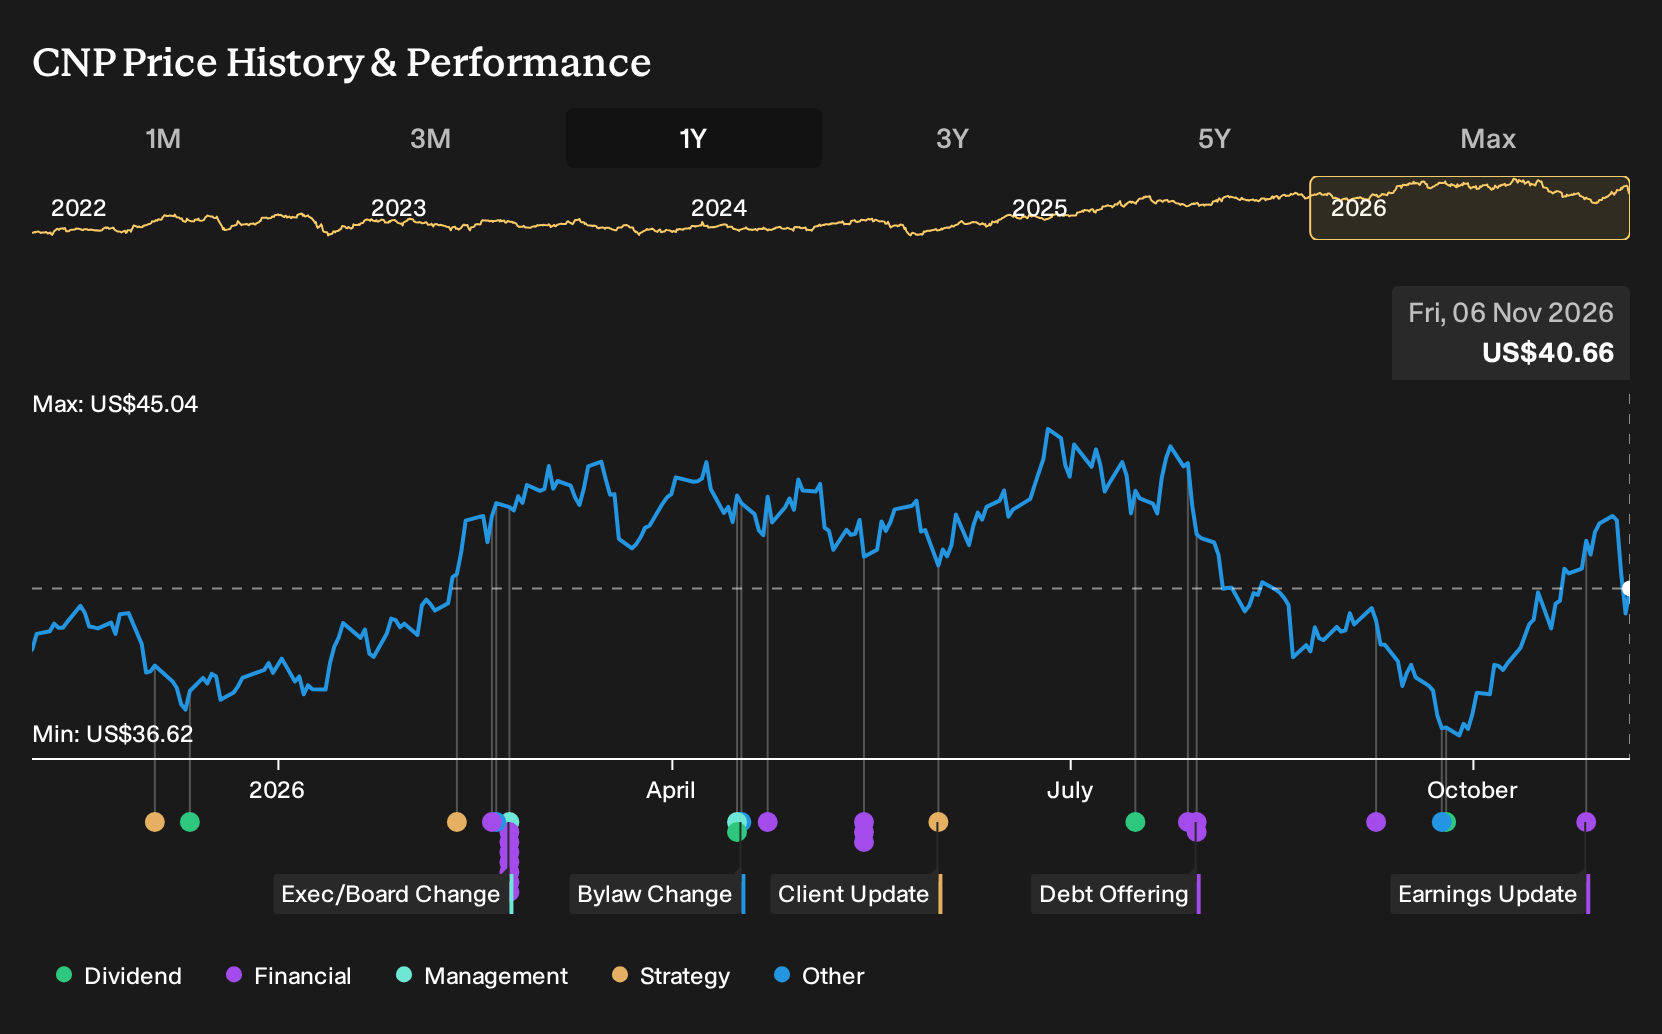
- CenterPoint Energy reported third quarter 2026 revenue of US$2,191 million and net income of US$331 million, with basic EPS from continuing operations at US$0.50, compared with US$0.45 a year earlier.
- Across the first nine months of 2026, CenterPoint Energy's revenue reached US$7,318 million and net income was US$891 million, with higher basic and diluted EPS from continuing operations than the prior year, reflecting operational firmness across its regulated utility footprint.
- This article will now examine how CenterPoint Energy's quarterly earnings from continuing operations could influence the broader investment narrative around the utility.
CenterPoint Energy Investment Narrative Recap
To own CenterPoint Energy, you need to believe the regulated electric and natural gas operations can keep turning heavy capital spending into steady earnings while customer demand in places like Houston and Indiana stays supportive. The latest quarter showed higher revenue and net income from continuing operations, which helps the case that the utility is executing against that plan right now.
The key near term swing factor remains how cleanly CenterPoint Energy can fund its large investment program without letting financing costs and equity issuance dilute earnings. Interest coverage and premium P/E expectations are the main pressure points. The fresh earnings address those pressure points slightly, but do not radically shift the risk profile.
The third quarter 2026 report is the announcement to focus on here because it gives a live check on the investment narrative. CenterPoint Energy posted US$2,191 million in revenue and US$331 million in net income for the quarter, with basic EPS from continuing operations of US$0.50 compared with US$0.45 a year earlier.
Across the first nine months of 2026, revenue of US$7,318 million and net income of US$891 million, alongside higher basic and diluted EPS from continuing operations than the prior year, speak directly to execution on the capital plan and large load opportunities. For a shareholder, those numbers intersect with the main catalysts and the biggest risk, that future funding needs could pressure interest coverage and lead to compression in the current P/E premium if sentiment cools.
CenterPoint Energy's narrative projects US$11.4b revenue and US$1.6b earnings by 2029. This is based on an assumption of 6.0% yearly revenue growth and an earnings increase of about US$0.5b from US$1.1b today.
Uncover why CenterPoint Energy's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about US$29 and US$44, so private investors are assigning CenterPoint Energy a wide range of possible worth. Consider that alongside the premium to large cap peers and the heavy capital plan, as both factors could influence how you weigh these contrasting opinions.
Explore 2 other CenterPoint Energy fair value estimates, including one that suggests as much as 29% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your CenterPoint Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CenterPoint Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CenterPoint Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond CenterPoint Energy?
If the CenterPoint Energy story has you thinking about position sizing, diversification, and what else might fit alongside a regulated utility, it can help to scan a wider field of opportunities that share some of the financial qualities you value most.
- For investors who want quality at a discount, focus on businesses that combine solid fundamentals with appealing valuations using our curated 39 high quality undervalued stocks.
- If resilience matters most to you, narrow in on companies with stronger balance sheets and healthier fundamentals with this targeted list of solid balance sheet and fundamentals (24 results).
- When you are hunting for underfollowed opportunities, look toward smaller, fundamentally robust stocks that receive less market attention through our focused 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com