
Is Live Nation Entertainment (LYV) Undervalued On Strong Earnings And Ticketmaster Outlook?
Live Nation Entertainment (LYV) just posted third quarter 2026 results that put its live events engine in focus, with higher sales, improved quarterly earnings, and a raised outlook for its Ticketmaster ticketing operations.
The share price reaction has been muted in the short term, with Live Nation Entertainment down over the past day and week, but the 1-month share price return of 2.58% and year to date gain of 20.60% suggest underlying momentum is still intact. In that context, a 1-year total shareholder return of 24.72% and a 3-year total shareholder return of about 2x reflect how earnings, record attendance and the expanding venue pipeline have helped reshape investor expectations, even after the latest move to US$175.25 per share.
Spot patterns behind Live Nation Entertainment's momentum by comparing it with a hand picked 19 high quality undiscovered gems showcasing similar business strength and market interest.Live Nation Entertainment now couples packed venues with a share price near US$175. The business looks strong. The real tension is whether that concert engine is already fully priced in.
Most Popular Narrative: 13% Undervalued
Live Nation Entertainment closed at $175.25, while the most followed narrative pins fair value near $201.96. That gap rests on a very specific view of how venues, tickets and sponsorships compound together over time.
Ongoing buildout of Venue Nation arenas, including over 20 projects in construction or fully permitted and a planned 15 million fan capacity addition across 2026 and 2027, is set to increase owned infrastructure exposure and on site spending opportunities that can support higher revenue and improved net margins once these venues are fully contributing.
See why 22 investors see Live Nation Entertainment as 13% undervalued.
Result: Fair Value of $201.96 (UNDERVALUED)
Still, the legal overhang around Ticketmaster, including the US$450 million accrual and the upcoming remedies trial, could pressure Live Nation Entertainment’s profits and weaken the current valuation case.
Find out about the key risks to this Live Nation Entertainment narrative.
Another View: What Multiples Say About Live Nation Entertainment
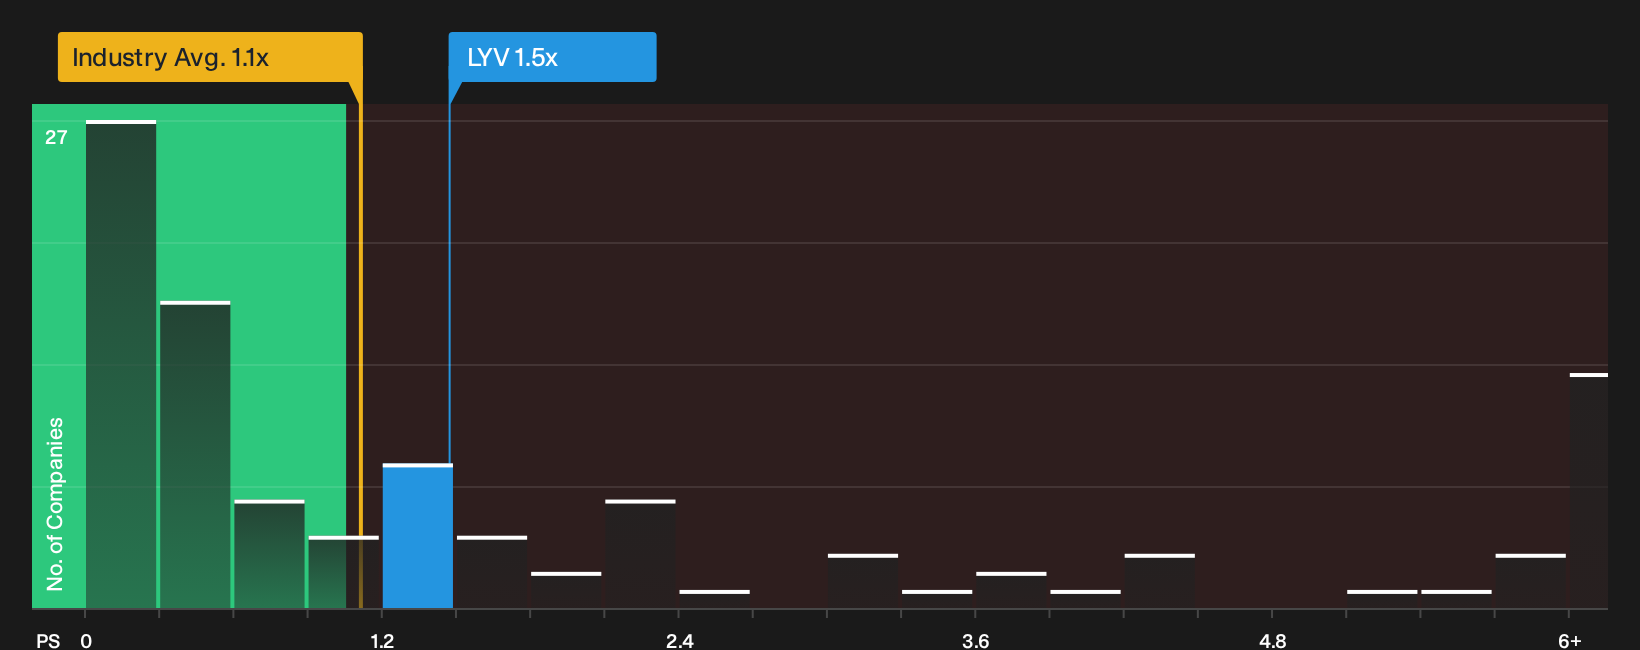
There is a different signal coming from simple sales based pricing. Live Nation Entertainment trades on a P/S ratio of 1.5x, which is richer than the US Entertainment sector average of 1.1x, yet sits well below both its peer average of 3.8x and a fair ratio estimate of 2.4x. That mix points to a stock that the wider market prices cautiously compared with similar businesses, even though regression work suggests the multiple could shift higher over time. How comfortable are you with that gap between today’s sticker price and where sentiment might head next?
See what the numbers say in more detail, then weigh it against your own expectations for concerts, ticketing and sponsorship before leaning on any single yardstick. Use this valuation breakdown as one reference point alongside your broader research, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment across Live Nation Entertainment is mixed enough that it pays to see the raw figures yourself, then move quickly to form your own stance. To frame those positives clearly, start with the 2 key rewards.
Looking For More Investment Ideas Beyond Live Nation Entertainment?
If Live Nation Entertainment has sharpened your appetite for opportunities, do not stop here. Broaden your watchlist, pressure test your thinking and keep fresh ideas coming.
- Pinpoint potential value opportunities early by scanning a curated list of companies that combine quality fundamentals with attractive pricing using the 39 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by focusing on businesses that pair sturdy finances with resilient operations through the list of solid balance sheet and fundamentals (24 results).
- Hunt for less crowded prospects by filtering for high quality companies that market attention has not yet fully embraced via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com