
Does Earnings And CEO Succession Change The Bull Case For Clean Harbors (CLH)?
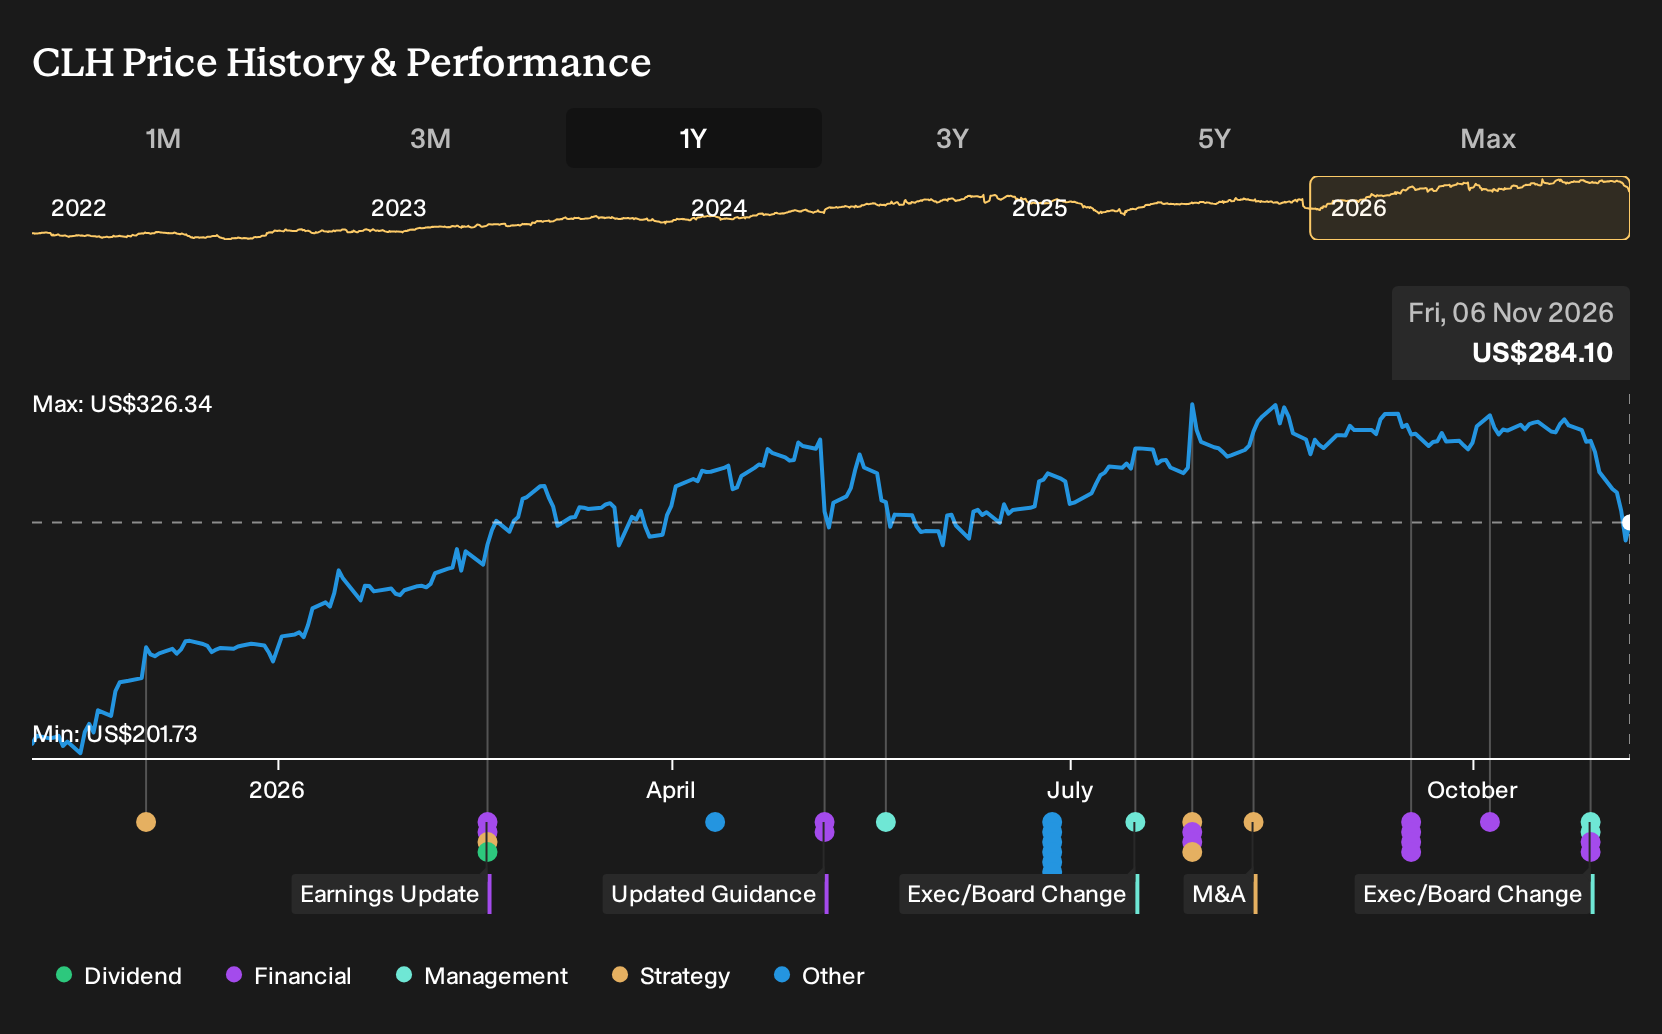
- Clean Harbors reported third quarter 2026 revenue of US$1,869.45 million and net income of US$208.1 million, issued full year 2026 GAAP net income guidance of US$528 million to US$563 million, and outlined leadership changes including Mike Battles retiring as Co CEO and director at year end 2026.
- The combination of higher third quarter and year to date earnings, fresh full year profit guidance and a defined move to Eric Gerstenberg as sole CEO in 2027 provides investors with more concrete data on how Clean Harbors is converting waste demand and its asset base into profitability under the next phase of leadership.
- We will now see how Clean Harbors' stronger earnings and 2026 net income guidance could influence the longer term investment narrative.
Scan how Clean Harbors' earnings momentum and leadership transition compare by reviewing list of solid balance sheet and fundamentals (24 results) across the wider industrial and environmental services space.
Clean Harbors Investment Narrative Recap
To own Clean Harbors, you need to believe the demand for hazardous waste treatment, PFAS destruction and sustainability services can support steady earnings, even if headline revenue growth is moderate. The latest quarterly results, with US$1,869.45 million in revenue and US$208.1 million in net income, reinforce that the assets are currently being used to generate solid profitability.
The near term catalyst is execution on the existing project pipeline and high utilization at core facilities, while keeping Industrial Services from dragging on consolidated margins. The biggest risk remains balance sheet pressure from prior debt funded expansion if acquired businesses or new capacity do not sustain attractive returns.
The fresh full year 2026 GAAP net income guidance of US$528 million to US$563 million is the clearest operational signal in this update. It provides a concrete profit range to compare against Clean Harbors' capital spending, interest costs and PFAS or disposal contract pipeline, and to judge whether current margins look sustainable.
That range also frames the CEO transition. Eric Gerstenberg becoming sole CEO on 1 January 2027, with Mike Battles staying on as an adviser, points to continuity in how the firm runs its environmental network. For catalysts tied to PFAS work, incinerator utilization and Safety Kleen Sustainability Solutions, the focus stays on execution quality rather than a sudden change in direction.
What The Clean Harbors Forecasts Are Really Asking You To Believe
Clean Harbors' analyst narrative rests on a set of fairly specific numbers. Forecasts assume revenue will grow by 5.5% each year for the next three years, with profit margins moving from 7.0% today to 8.6% by 2029. Consensus earnings estimates point to US$439.1 million today rising to US$629.3 million by 2029, which is an increase of about US$190 million in annual profit that investors need to underwrite.
On these projections, the valuation story leans heavily on where the business could be by the end of the decade. Analysts are working toward 2029 revenue of US$7.3b and earnings of US$629.3 million, paired with a P/E multiple of 35.9x that is higher than the 18.3x cited for the wider US Commercial Services industry. For readers, the crux is simple: you would need to be comfortable that Clean Harbors can translate its hazardous waste, PFAS and sustainability footprint into that level of revenue and income by 2029, and that the stock could still command a premium multiple at that point.
Clean Harbors' narrative projects US$7.3b revenue and US$629.3 million earnings by 2029. This setup implies 5.5% yearly revenue growth and about US$190 million earnings increase from the current US$439.1 million level.
Uncover why Clean Harbors' fair value highlights a 27% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$350 and about US$473 per share, so private investors are already spanning a wide gap on what Clean Harbors is worth. When you layer on the 2026 profit guidance and CEO transition, it becomes clear how quickly opinions can diverge, so explore several viewpoints before deciding where you sit.
Explore 2 other Clean Harbors fair value estimates, including one that suggests as much as 67% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Clean Harbors research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Clean Harbors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Clean Harbors' overall financial health at a glance.
Looking For More Investment Ideas Beyond Clean Harbors?
Once you have formed a view on Clean Harbors, it can help to compare that thesis against other businesses with different balance sheets, cash flow profiles and dividend policies. The Simply Wall St Screener gives you a fast way to scan for stocks that fit the kind of risk and reward mix you want.
- If you want potential mispricing backed by fundamentals, start with a focused set of 39 high quality undervalued stocks that pair earnings power with stronger balance sheets.
- If capital preservation matters as much as upside, filter for 29 resilient stocks with low risk scores that score well on volatility, leverage and earnings stability.
- If you are hunting for ideas that the broader market may be overlooking, scan through 19 high quality undiscovered gems with solid financials but limited coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com