
NOV (NOV), What Is Behind The Fresh Attention?
NOV (NOV) drew fresh attention after third quarter results showed higher net income and earnings per share compared with last year, paired with guidance that points to roughly flat revenue in the coming quarter.
NOV’s share price has slipped over the past week and quarter, with a 7 day share price return of down 9% and a 90 day share price return of down 11%. However, the 1 year total shareholder return sits at 17% and the 5 year total shareholder return at 41%, which points to gains built over a longer horizon.
Scan other energy equipment players showing similar earnings momentum and contrasting guidance by running the hand-picked 39 high quality undervalued stocks alongside the latest move from NOV.
After a sharp pullback despite sturdier earnings from NOV and only flat near term guidance, the key question now is whether most of the upside has already been realized or if meaningful value still remains on the table.
Most Popular Narrative: 21% Undervalued
NOV last closed at $17.56, compared with a widely followed narrative fair value of $22.18 that is built around backlog, margins and earnings capacity. That gap puts the focus squarely on how much of NOV’s cash flow potential is already reflected in the share price after the recent pullback.
Deepwater projects that use floating production systems and subsea kit continue to build multi year order books for NOV, with record EBITDA margins in Energy Equipment, a book to bill of 135% and a 28% backlog rise in subsea flexible pipe, and an approved US$200 million Brazil plant expansion. Together these factors point to additional revenue and earnings as this backlog is worked down.
See why 15 investors see NOV as 21% undervalued.
Result: Fair Value of $22.18 (UNDERVALUED)
Still, this NOV narrative can be knocked off course if tariff and freight costs keep climbing, or if regional disruptions like those reported in the Middle East persist.
Find out about the key risks to this NOV narrative.
Another View On NOV’s Valuation
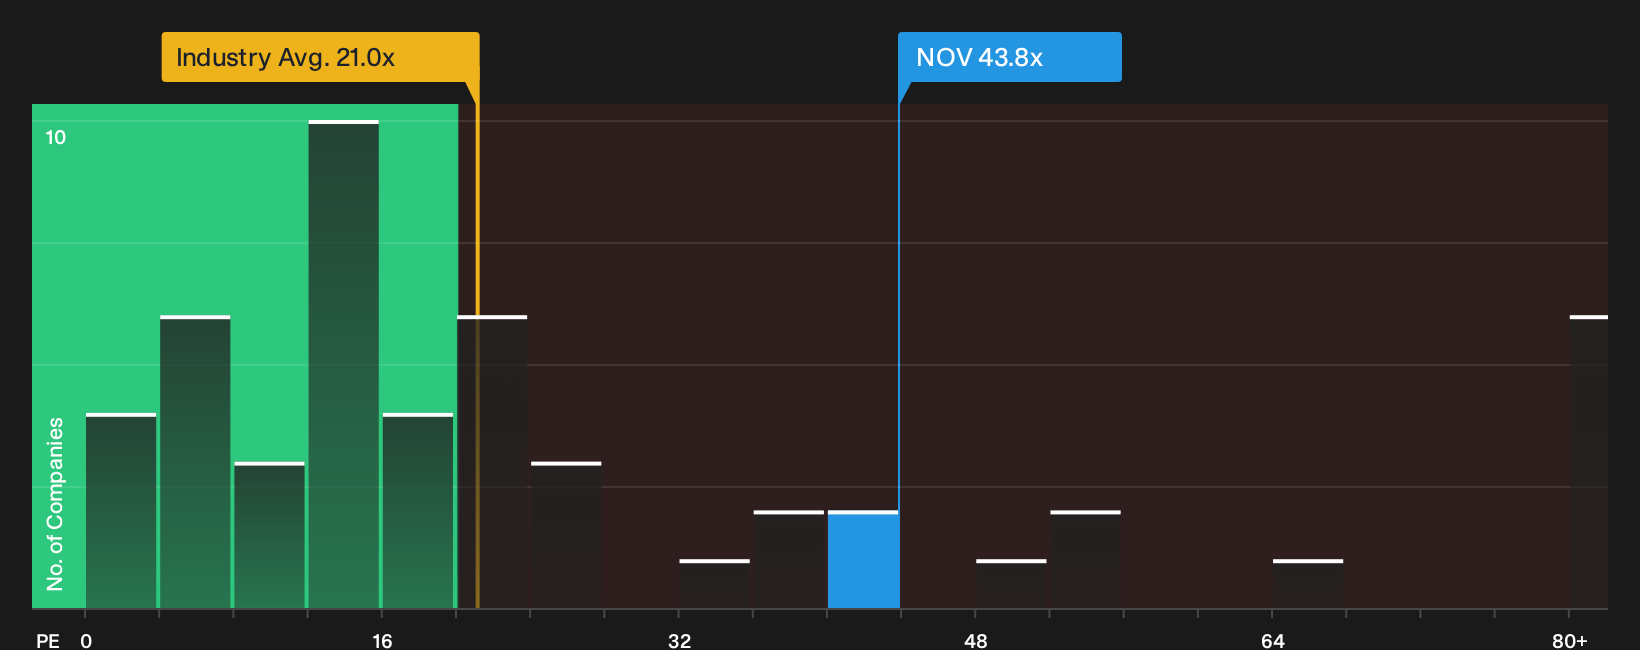
That 21% undervalued narrative leans on earnings capacity and backlog. A different lens, the P/E ratio, tells a tougher story. NOV trades on 43.8x earnings compared with both the US Energy Services industry at 20.7x and a fair ratio estimate of 23.7x. This points to a meaningful valuation risk if sentiment cools.
For a closer look at how those earnings multiples stack up against the fair ratio and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around NOV rings familiar, consider acting promptly, review the underlying figures yourself, and then weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond NOV?
NOV gives useful signals, but you limit yourself if you stop here. Cast a wider net now and stress test your thinking against other opportunities.
- Target potential upside by scanning a curated pool of undervalued candidates using the 39 high quality undervalued stocks before prices fully reflect their fundamentals.
- Protect your capital first and chase returns second by filtering for companies on the 29 resilient stocks with low risk scores that pair resilience with disciplined risk profiles.
- Hunt for future leaders hiding in plain sight through the 19 high quality undiscovered gems and see which quietly compounding businesses others may be ignoring.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com