
Is Easterly Government Properties (DEA) Trading At A Premium After Results?
Easterly Government Properties focuses on leasing buildings to U.S. government agencies, and its shares have seen mixed fortunes that leave a clear question about what investors are paying for today. After a multi year period that included both gains and a sizeable drawdown, the issue now is whether the current price lines up with what the business earns.
- The stock is down about 38.2% over 5 years, which puts the spotlight on whether the present valuation still reflects the earning power of a portfolio tied to federal tenants.
- Recent results highlighted net income and Core FFO alongside new leases and financing moves, which can influence how sustainable earnings look and how much cash flow is left for shareholders after funding the real estate footprint.
- The analysts covering Easterly Government Properties have run their own numbers. See what analysts think Easterly Government Properties's shares could be worth.
For investors, the debate is whether Easterly Government Properties' current share price is justified by its earnings when set against a Fair Ratio benchmark.
If you want to test the same earnings focused question across a broader watchlist, scan companies through the 39 high quality undervalued stocks.
Has Easterly Government Properties Run Too Far on Earnings?
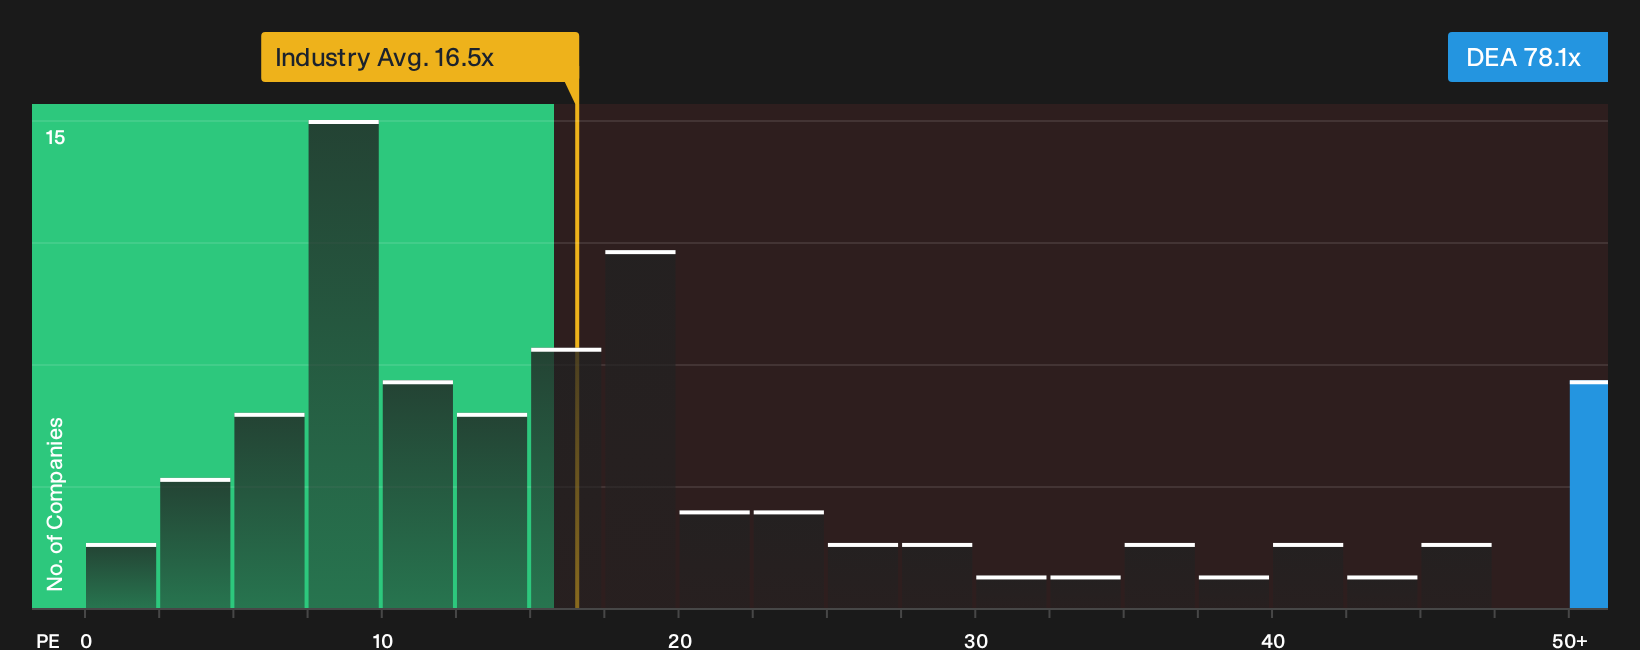
A P/E lens fits Easterly Government Properties because earnings are a core focus for many REIT investors alongside cash based measures like FFO. On this metric, the stock trades on a P/E of about 78.1x, compared with an Office REITs sector average near 16.5x and a peer group closer to 58.4x. That is a rich multiple for a landlord of government leased offices, so the share price already bakes in a premium for perceived stability and the quality of its tenant roster.
Because the Fair Ratio model adjusts for factors such as sector, risk profile and market size, it points to a lower P/E than the current level, which leaves Easterly Government Properties looking overvalued on this yardstick. Despite raising the lower end of its 2026 Core FFO guidance and renewing several federal leases, the valuation still sits well above both the tailored benchmark and broader Office REIT averages, so you need to decide whether that kind of premium feels justified. Explore the numbers behind Easterly Government Properties's P/E valuation.
The Easterly Government Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Easterly Government Properties valuation puzzle leaves off by explaining which expectations for future growth, margins and earnings would need to occur for the shares to be worth much more or much less than today. Each one presents Easterly Government Properties' fair value as a proposition about how the business might perform over time, which you can then track as fresh results and new information appear on the Community page.
One of the top community narratives on Easterly Government Properties: 11% undervalued
"The current valuation implies that investors are pricing Easterly Government Properties cautiously relative to its long-duration government cash flows..."
Discover why this Narrative puts Easterly Government Properties at 11% undervalued.
The share price is only one piece of the Easterly Government Properties puzzle
Valuation tells you what Easterly Government Properties costs today, but analyst projections for earnings and cash flow a few years out offer a separate lens on where expectations sit. Explore where analysts expect Easterly Government Properties to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com