
How Investors May Respond To Exelixis (EXEL) Strong Earnings And Buyback
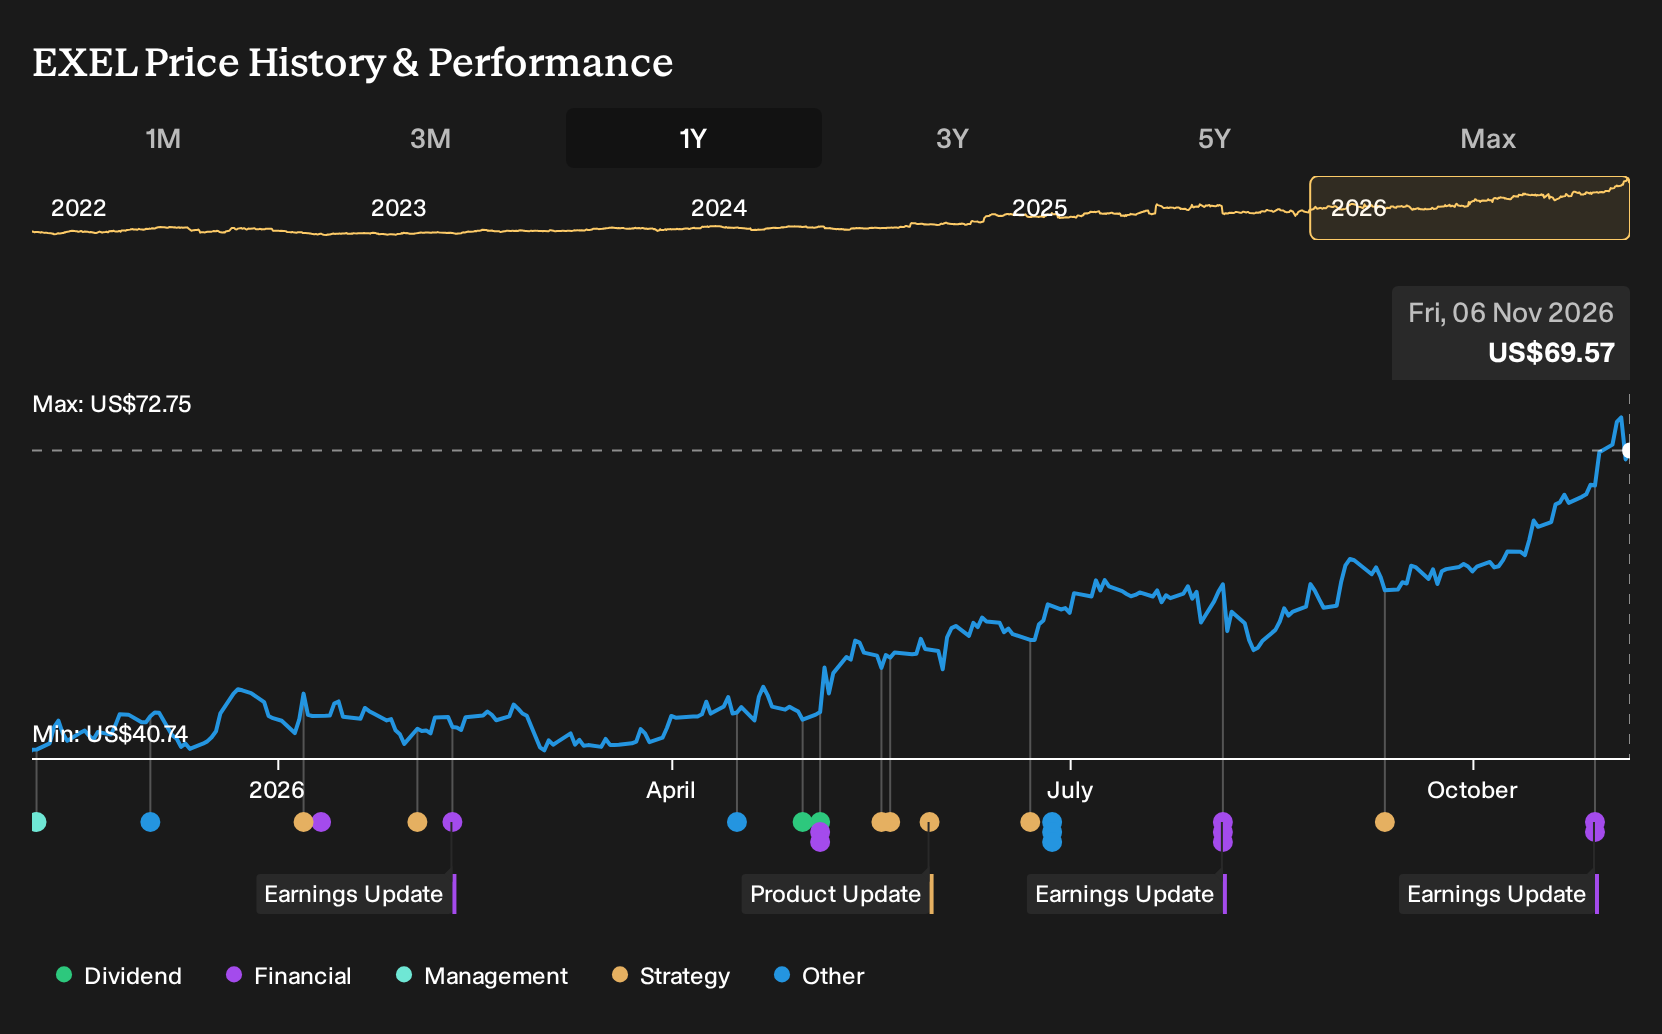
- Exelixis reported third quarter 2026 revenue of US$658.7 million and net income of US$218.1 million, alongside nine month revenue of US$1.8982 billion and net income of US$640.61 million, with earnings per share from continuing operations higher than the prior year on both a basic and diluted basis.
- The business also completed a sizeable buyback program announced in May 2026, spending US$402.16 million to retire 7,475,284 shares. This reduces the share count and concentrates future earnings across a smaller shareholder base.
- We will look at how Exelixis' investment narrative is shaped by these earnings figures and the completed share repurchase.
Exelixis Investment Narrative Recap
To own Exelixis, you need to be comfortable with a story that still leans heavily on cabozantinib while working to build a second oncology pillar around zanzalintinib and other pipeline assets. The latest quarterly numbers show the business generating substantial profit and cash, which gives it room to keep funding trials and commercial execution even as CABOMETYX NET ramp questions linger.
The key near term catalyst is regulatory and commercial progress for new indications, particularly zanzalintinib in colorectal cancer and other tumors. The biggest risk is that cabozantinib dependence collides with slower than hoped uptake for new launches or further regulatory delays. That would matter more to the long term narrative than the quarter itself.
The most relevant update here is management holding 2026 total revenue guidance at US$2.5b to US$2.55b after reporting US$1.8982b for the first nine months. Keeping that range in place ties the current earnings beat back to execution on existing CABOMETYX indications and newer NET use rather than resetting short term expectations higher.
For you as an investor, that guidance stance keeps attention on whether Exelixis can deliver the remaining revenue this year while progressing its late stage pipeline through reviews and launches. It also means the focus stays squarely on execution risk around cabozantinib exclusivity, regulatory decisions on zanzalintinib combinations, and the ongoing securities investigations into prior guidance.
Exelixis' current analyst story focuses on revenues reaching US$3.6b and earnings of US$1.5b by 2029, based on forecast revenue expansion of 12.9% a year and an earnings uplift of about US$615m from the US$885.1m reported today.
Uncover why Exelixis' fair value indicates a 17% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view on Exelixis emphasizes the share repurchase as the real catalyst. The most optimistic analysts were already modeling revenue of about US$3.9b and earnings of roughly US$1.6b by 2029, before this earnings report and buyback completion. You can compare that upbeat script with consensus and decide which story feels closer to your own expectations, knowing both camps may adjust their models after this news.
Explore 4 other Exelixis fair value estimates, including one that suggests up to 187% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Exelixis research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Exelixis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Exelixis' overall financial health at a glance.
Looking For More Investment Ideas Beyond Exelixis?
Once you have a view on Exelixis, it can help to line that thesis up against other opportunities that share similar qualities, whether you care most about value, balance sheet strength, or lower risk profiles. The Simply Wall St Screener lets you quickly filter for businesses that match the traits you prioritize, so you can build a shortlist that actually fits your style rather than chasing every headline.
- If you want potential mispricing with quality fundamentals on your side, start by scanning our hand picked 39 high quality undervalued stocks and see which ideas deserve a closer look.
- If resilience and financial strength matter most to you, focus on companies with cleaner balance sheets using this curated list of solid balance sheet and fundamentals (24 results) as your next research stop.
- If you prefer opportunities where downside risk screens lower on our models, narrow the field by reviewing the 29 resilient stocks with low risk scores and build a watchlist that matches your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com