
Why Higher Rates Are Driving Investors Toward US Large Cap Dividend Stocks
Rates look set to stay higher for longer after a strong October jobs report, and that shifts the spotlight onto large US companies that already generate cash and pay dividends. When money is no longer free, dependable income and steadier share price moves start to matter more, and fast. This article examines three stocks from a value and dividend screener that appear closely tied to the latest macro shock.
The three stocks highlighted next are only a first pass at what higher-for-longer rates could mean for value and income opportunities, and the full process surfaced 12 more large US companies with similarly grounded stories that are not covered below. To go broader than this short list, head straight into the US Large-Cap Value and Dividend Stocks screener to identify, compare, and analyze the higher-conviction ideas that fit your own risk and income goals.
Lamb Weston Holdings (LW)
Overview: Lamb Weston Holdings produces and sells frozen potato products and appetizers to restaurants, foodservice distributors, and retailers across North America and internationally.
Operations: Lamb Weston generates about US$4.5b in North America revenue and US$2.2b from international markets, reflecting a broadly diversified sales base.
Market Cap: US$7.6b
Lamb Weston Holdings fits the screener as a sizeable food producer with a dividend and cash generation profile that can appeal when investors prize resilience. Recent commentary around its European business also shows how operational details can matter more than headline macro moves.
"The call now places the cause on supply. Mike Smith calls the European crop “a tale of two years,” argues that raw potato quality and yield “is likely going to be the limiter,” and says “not all open industry capacity will be used.”
What happens to Lamb Weston’s earnings power now leans heavily on how one unresolved pressure feeds through to future pricing and mix.
If that pricing power question matters to you, read the full narrative for Lamb Weston Holdings to see whether short term supply stress is masking longer term earnings strength.

Bunge Global (BG)
Overview: Bunge Global is a global agribusiness and food group that buys, processes, and sells oilseeds, grains, and related products for food, feed, fuel, and milling customers.
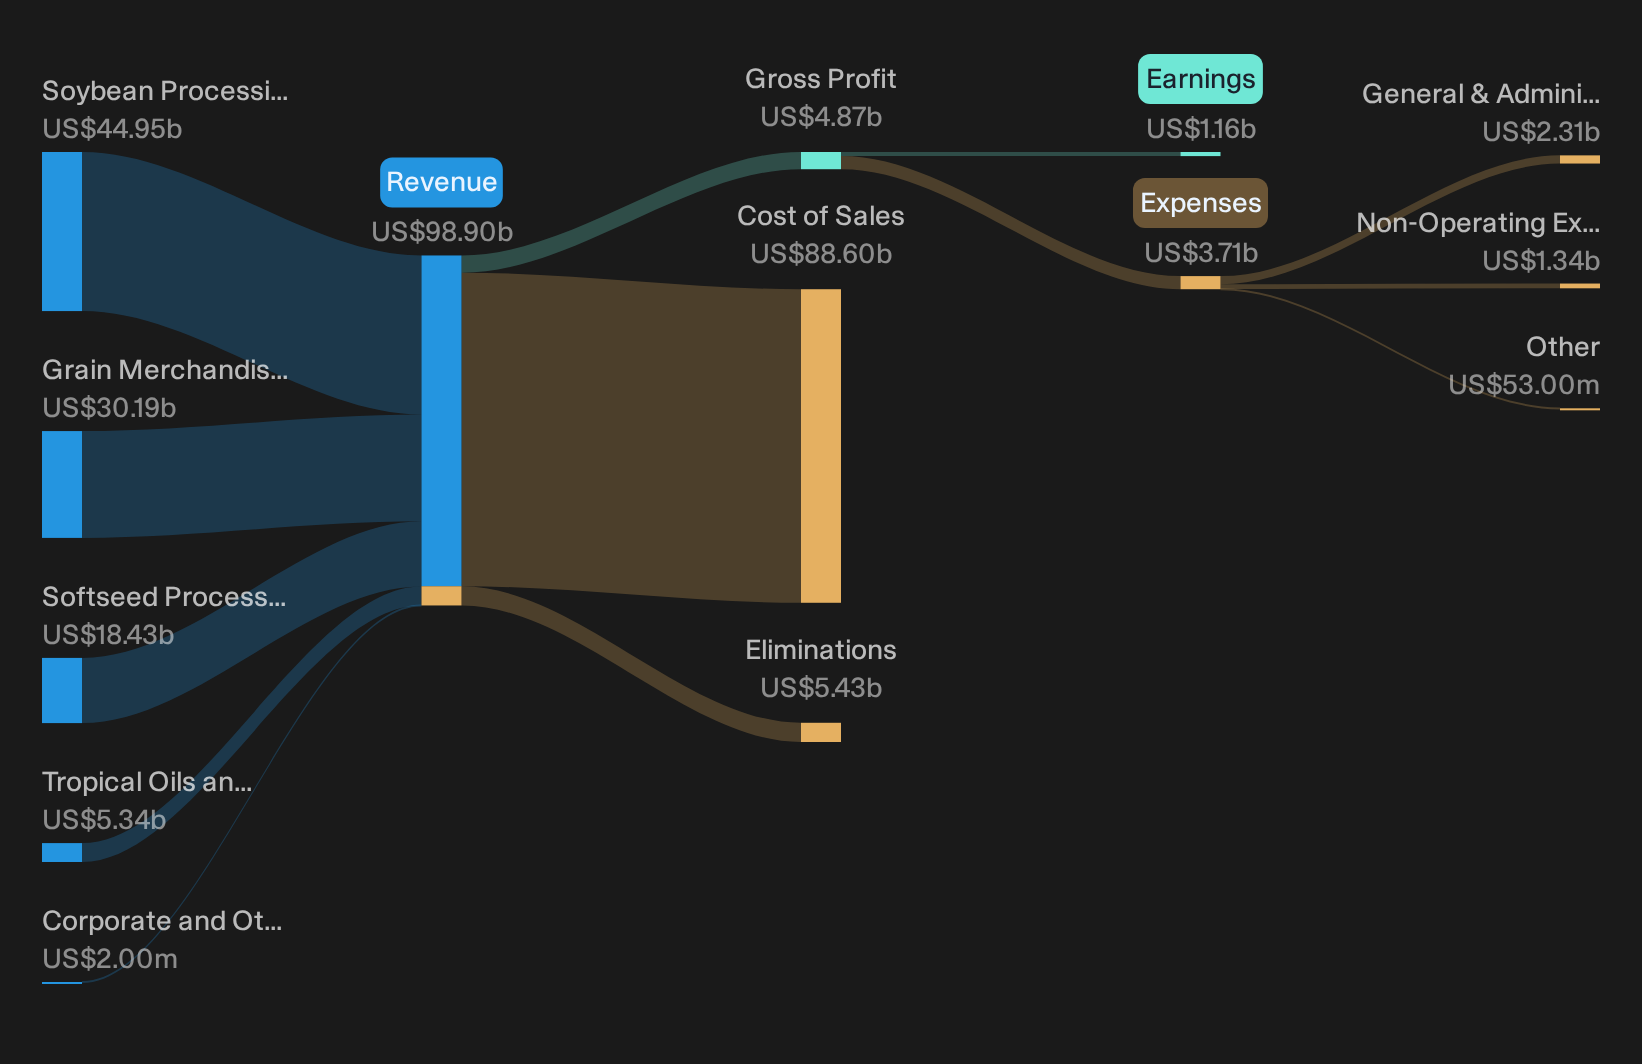
Operations: Bunge Global earns about US$44.9b from Soybean Processing and Refining, US$30.2b from Grain Merchandising and Milling, and US$18.4b from Softseed Processing and Refining, with smaller contributions from Tropical Oils and Specialty Ingredients and Corporate and Other, partly offset by eliminations.
Market Cap: US$18.9b
For investors looking at large US agribusinesses that already produce cash and pay dividends, Bunge Global links the screener theme to the real economy through its role in moving crops, oilseeds, and food ingredients across the globe.
"The completion and integration of the Viterra merger provides substantial cost and commercial synergies, expands Bunge Global's global origination, processing and distribution footprint, and positions the company to capture greater market share in higher growth regions, which can support higher revenue and operating margins over time."
What happens to Bunge Global’s margin profile now depends heavily on how one unseen funding and cash flow pressure develops as rates stay higher.
That funding question is the real hinge. Read the full narrative for Bunge Global to see whether higher rates end up accelerating or quietly stalling Bunge Global’s merger upside.
Upbound Group (UPBD)
Overview: Upbound Group offers technology and data-driven lease-to-own, installment and financial health solutions to non-prime consumers across Rent-A-Center, Acima, Brigit and Mexico, aligning with a value and dividend screen that favors cash-generative, income-oriented US financial businesses in a higher-rate backdrop.
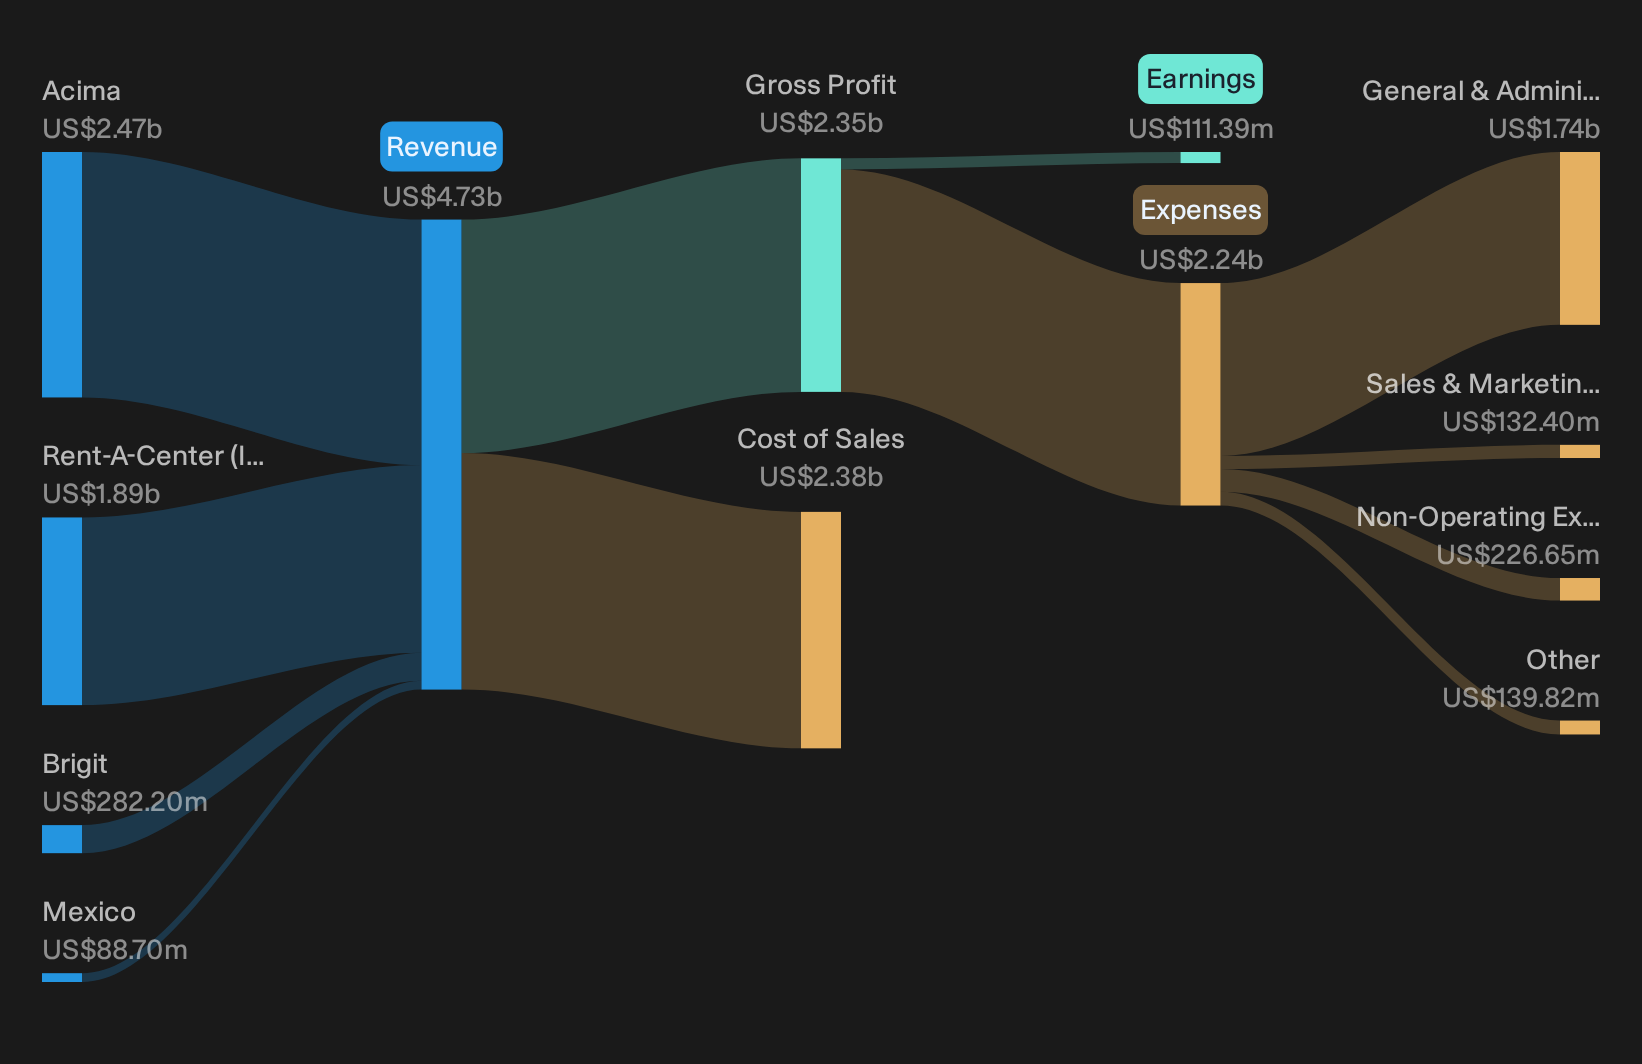
Operations: Upbound Group generates about US$2.5b from Acima, US$1.9b from Rent-A-Center including franchising, US$282 million from Brigit and US$89 million from Mexico.
Market Cap: US$1.5b
Upbound Group brings something different to this value and dividend screen: a US-focused financial solutions platform that leans on recurring payments from non-prime customers rather than headline growth stories.
"Brigit’s continued expansion, with Q2 2026 revenue of US$71 million, paying users of about 1.7 million and rising ARPU, points to a larger recurring fee base that can reshape Upbound Group’s mix toward higher margin, subscription style earnings."
What happens to those subscription-like earnings now depends heavily on how one unresolved credit and funding pressure plays through the next rate phase.
Those pressures are exactly why reading the full narrative for Upbound Group can help you see whether Upbound Group’s recurring fees are quietly compounding or at risk of stalling.
Seeking Alternatives Before The Crowd?
Fresh opportunities move fast. Some are building quiet momentum, others are dropping into value territory, and a few stay under the radar for now.
- Spot income ideas by scanning the 8 dividend fortresses that focus on payouts backed by balance sheets built to handle tougher conditions.
- Review the 41 profitable AI stocks that aren't just burning cash that pair AI exposure with current earnings instead of cash burn.
- Explore the 42 power grid technology and infrastructure stocks filled with businesses involved in modernizing critical electricity infrastructure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com