
3 British Growth Stocks For November 2026
Inflation worries are back on corporate earnings calls and central banks are keeping borrowing costs in focus, which puts reliable growth at a premium for UK investors. Fast growing British companies where insiders hold meaningful stakes can look interesting when the market questions what growth is worth paying for. This article highlights three stocks from a high growth, high insider ownership screen that could deserve a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where executives and board members have substantial skin in the game. However, if you want the standouts, these 6 high growth high conviction stocks are the most outstanding.
International Workplace Group (LSE:IWG)
Overview: International Workplace Group provides flexible office, coworking, membership and virtual workspace solutions for companies and landlords across global markets.
Operations: International Workplace Group generates about $3.3b from company-owned centres, with a further $151 million from managed and franchised operations.
Market Cap: £2.0b
International Workplace Group fits this fast growth and insider-backed screener because its flexible workspace network leans heavily on recurring memberships and fee-based partnerships. Management consistently points to these as the main engine for future expansion.
"Management plans to use automation and AI to hold core overheads flat and improve cash conversion. However, the acknowledged sensitivity of EBITDA to company-owned revenue suggests that if these tools fail to offset softer RevPAR or occupancy, the expected benefit to net margins and free cash flow may not materialise."
For investors, a single tension between recurring-fee expansion and that older company-owned footprint could end up steering where margins and cash generation settle.
Where that balance ultimately lands, the full narrative for International Workplace Group explains how recurring fees, leverage and insider incentives could be quietly reshaping International Workplace Group’s risk and opportunity profile.

Saga (LSE:SAGA)
Overview: Saga focuses on the UK over 50s market, offering cruise and package holidays alongside insurance and personal finance products.
Operations: Saga generates most of its £706.9 million revenue in the UK, led by £538.3 million from Travel and £143.6 million from Insurance Broking.
Market Cap: £1.3 billion
Saga appeals to this fast growth and insider-backed theme because its cruise and holiday operations target an expanding retiree audience that management is actively trying to convert into higher margin travel customers.
"Although Saga highlights strong forward bookings in Ocean Cruise, with booked load factors into future years and higher per diems, the plan to keep adding value through onboard investment raises the hurdle for sustaining price led growth without eroding incremental margin if demand normalises, which could pressure operating margin expansion and profit growth."
The question is what happens if a subtle shift in how Saga balances pricing power against those added onboard costs changes the travel profit equation.
If that trade off between pricing power and onboard spend is what interests you, read the full narrative for Saga to see how Saga’s travel engine could still accelerate.

Greencore Group (LSE:GNC)
Overview: Greencore Group manufactures chilled and ambient convenience food such as sandwiches, salads and ready meals for major UK and Irish retailers.
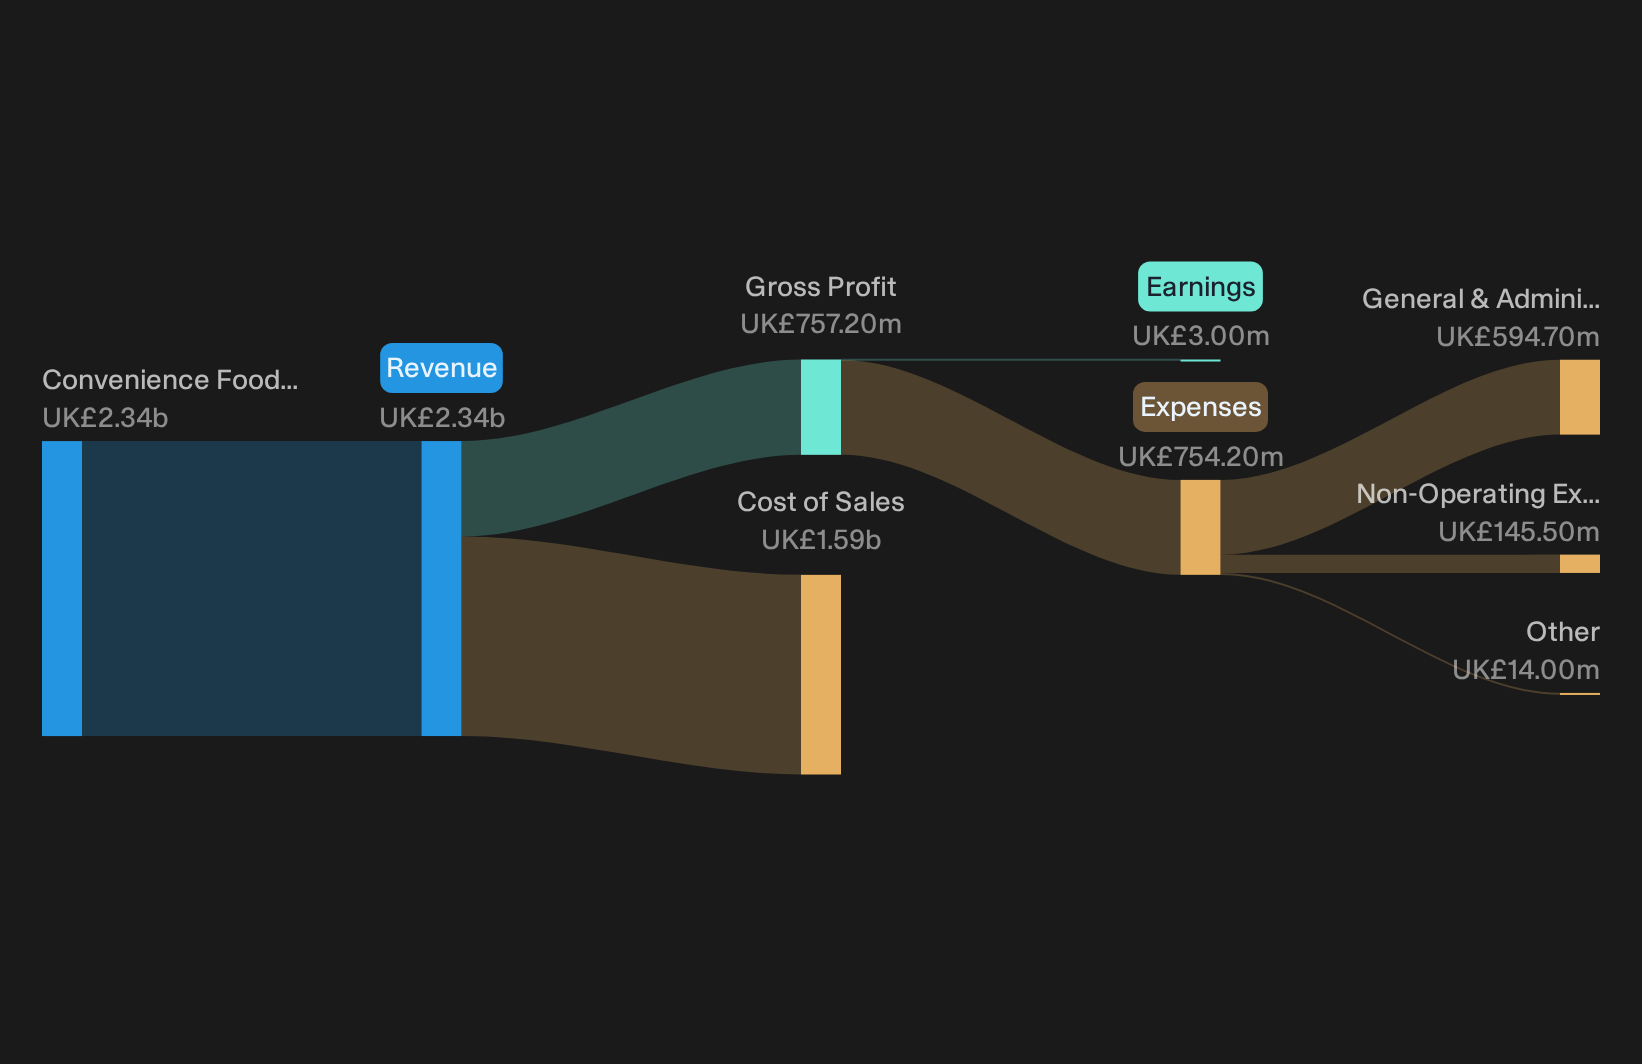
Operations: Greencore Group generates about £2.3b in revenue from its Convenience Foods UK & Ireland division, supplying supermarkets and travel outlets.
Market Cap: £2.4b
Greencore Group matters for this fast growing, high insider ownership theme because its convenience food shelves are where everyday habits meet higher margin ready to eat demand.
"Operational excellence programs and a five year automation roadmap, which have already lifted units per labour hour and target at least 10% direct labour savings over time, can continue to support higher operating margins and earnings as more projects are rolled out across Greencore Group sites."
The real swing factor is whether one stubborn pressure on cash generation eases in time for those operational gains to fully show up.
If that pressure is what you are weighing, the full narrative for Greencore Group shows how Greencore Group’s automation gains could decouple earnings power from near term cash strain.
Seeking Alternatives Before The Crowd?
Fresh ideas move first and slow research often gets caught chasing momentum as opportunities start flying. Scan these curated shortlists while it matters and aim to act early.
- Target stronger balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (9 results) before quality is fully priced in by the market.
- Focus on structural demand in electrification and infrastructure upgrades by reviewing carefully filtered 42 power grid technology and infrastructure stocks while these themes are still building momentum under the radar.
- Consider potential capacity tightness in key materials by checking the hand picked 16 top copper producer stocks before the crowd starts chasing late cycle miners.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com