
Howmet Aerospace (HWM) Lifts Guidance After Q3 Beat But Is The Valuation Still Compelling
Howmet Aerospace (HWM) just delivered third quarter 2026 results that showed higher sales and net income versus a year earlier, while management lifted 2026 guidance and outlined revenue expectations for 2027.
Investors have had a choppy ride with Howmet Aerospace this year, with the share price down about 27% over the past 90 days and about 8% over the past month, even as the latest earnings beat expectations and guidance moved higher. That pullback sits against a share price that is only modestly lower year to date and a very large 5 year total shareholder return of more than 7x, which hints that recent weakness may reflect a reset in expectations rather than a collapse in confidence.
Scan beyond Howmet Aerospace and see how other high quality industrials are setting up right now with our curated 19 high quality undiscovered gems list.
After such a sharp pullback in Howmet Aerospace despite stronger recent earnings and higher guidance, the key tension now is simple. Does today’s price still leave enough upside to compensate for the risks?
Most Popular Narrative: 33% Undervalued
The prevailing narrative pegs Howmet Aerospace’s fair value at $306.75 versus the last close of $205.81. This frames recent share weakness very differently from the price chart and sets up a clear hinge on execution and capital allocation.
The main thing that has to go right is that Howmet Aerospace executes on its large capacity expansion and integration of CAM fasteners so that heavier capital spending and acquisitions translate into sustained high margins and cash generation.
The numbers and recent valuation work imply that even after a share price move of roughly 7 to 8 times over five years and some views of around 20% overvaluation, the stock is still being treated as a high quality compounder with further upside expected versus current earnings forecasts.
See why 92 investors see Howmet Aerospace as 33% undervalued.
Result: Fair Value of $306.75 (UNDERVALUED)
Still, the narrative around Howmet Aerospace could shift quickly if industrial gas turbine demand cools or if investors decide that a lower P/E multiple is warranted.
Find out about the key risks to this Howmet Aerospace narrative.
Another View on Howmet Aerospace Valuation
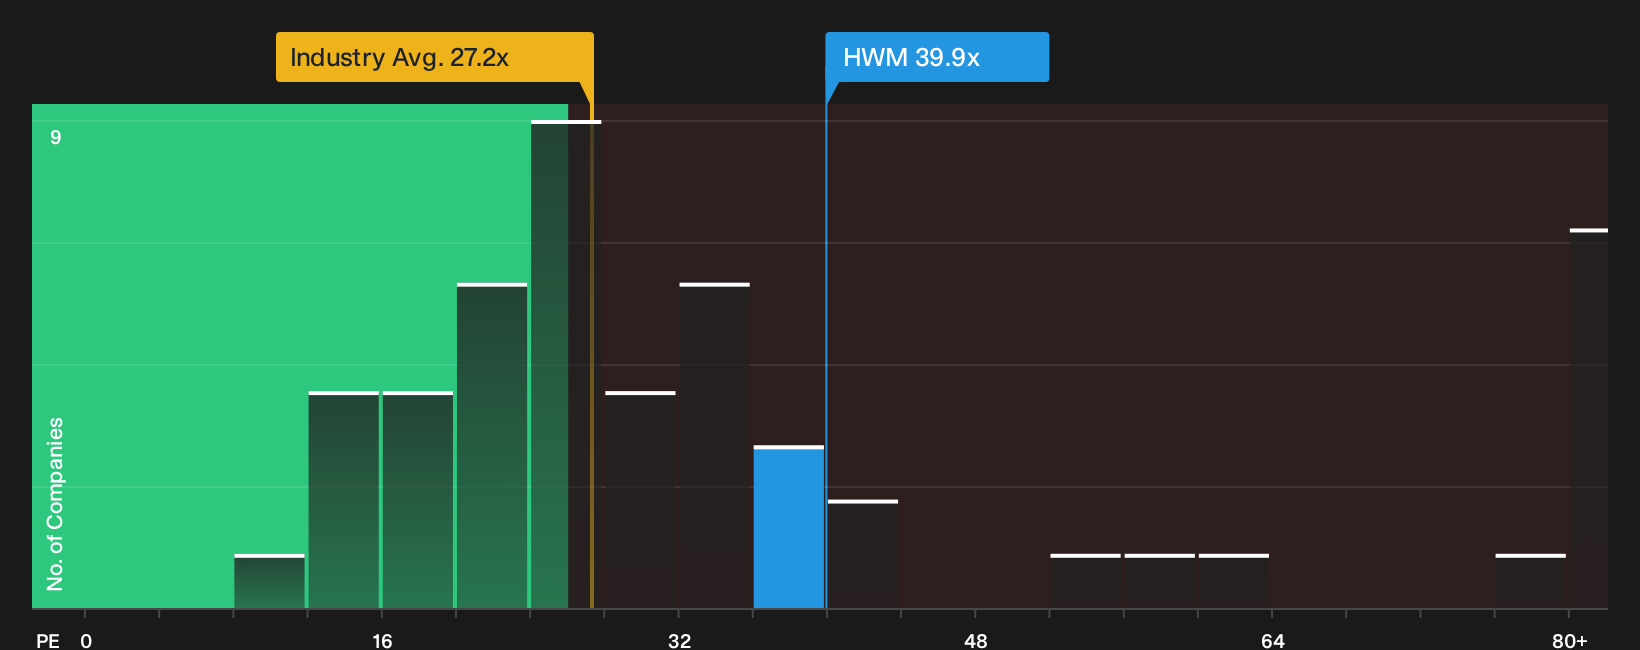
The story looks different once price multiples are brought into the picture. Howmet Aerospace trades on a P/E of 39.9x while the US Aerospace & Defense industry sits around 27.2x and peers average 23.9x. The fair ratio sits at 32.4x, which signals richer pricing and less margin for error than the headline fair value suggests. Where do you place more weight: the narrative of upside, or the risk that the market drifts closer to that fair ratio?
For a closer look at how the current pricing stacks up against earnings power and peer benchmarks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in Howmet Aerospace leave plenty of room for debate, so move fast, review the data, and pressure test both sides of the story with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Howmet Aerospace?
If you stop with Howmet Aerospace, you risk missing other setups that fit your style and risk limits, so broaden your radar with a few targeted filters.
- Target potential mispricings by scanning a curated pool of stocks that our models flag as attractively valued through the 39 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on companies with healthier finances using the list of solid balance sheet and fundamentals (24 results).
- Zero in on stability first by filtering for businesses with historically lower risk profiles through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com