
What SLB (SLB)'s Norway Subsea Contract Means For Shareholders
- SLB secured a contract from Aker BP for the Lyra field on the Norwegian Continental Shelf and introduced new subsea, digital and nano-enabled production technologies that target faster project execution and longer treatment life in mature reservoirs.
- The combination of standardized subsea systems, FDPlan digital field development and ChampionX nano-chemistry indicates that SLB is placing greater emphasis on efficiency-driven, service-intensive work that can influence project economics for both new offshore tiebacks and aging fields.
- We will now see how SLB's investment narrative could be shaped by the Lyra subsea contract that emphasizes standardized offshore technology.
SLB Investment Narrative Recap
To own SLB, you need to believe that its mix of long cycle offshore work, higher margin digital tools and production chemicals can support steadier cash generation across cycles. The Lyra subsea award fits that view, but on its own it does not change the near term picture. The more immediate swing factor is execution on the broader backlog and integration of new offerings.
The biggest operational risk still sits in regional and segment concentration. Disruption in the Middle East, slower uptake in data center solutions or weaker appetite for large integrated upstream projects could all weigh on margins. Lyra slightly reinforces the offshore production systems story, yet does not materially offset those broader uncertainties by itself.
The Crescent Petroleum deal for FDPlan in the Middle East and North Africa is the clearest operational echo of what Lyra represents. Both contracts lean into SLB’s push to use standardized hardware and shared digital environments to shorten project planning and reduce life of field costs. That ties directly to the recurring revenue and margin expansion narrative.
For you as an investor, that FDPlan deployment matters because it tests whether SLB’s software and data platforms can move from slideware to embedded workflows that customers rely on. If adoption stalls, the digital catalyst and expected resilience in cash flow look softer. If it scales, it supports the same efficiency story that underpins Lyra and similar subsea wins.
SLB's current analyst script ties together a forecast for about US$43.0b in revenue and US$5.5b in earnings by 2029, built on assumed annual top line growth of 5.7% and an earnings increase of roughly US$2.4b from the US$3.1b reported today.
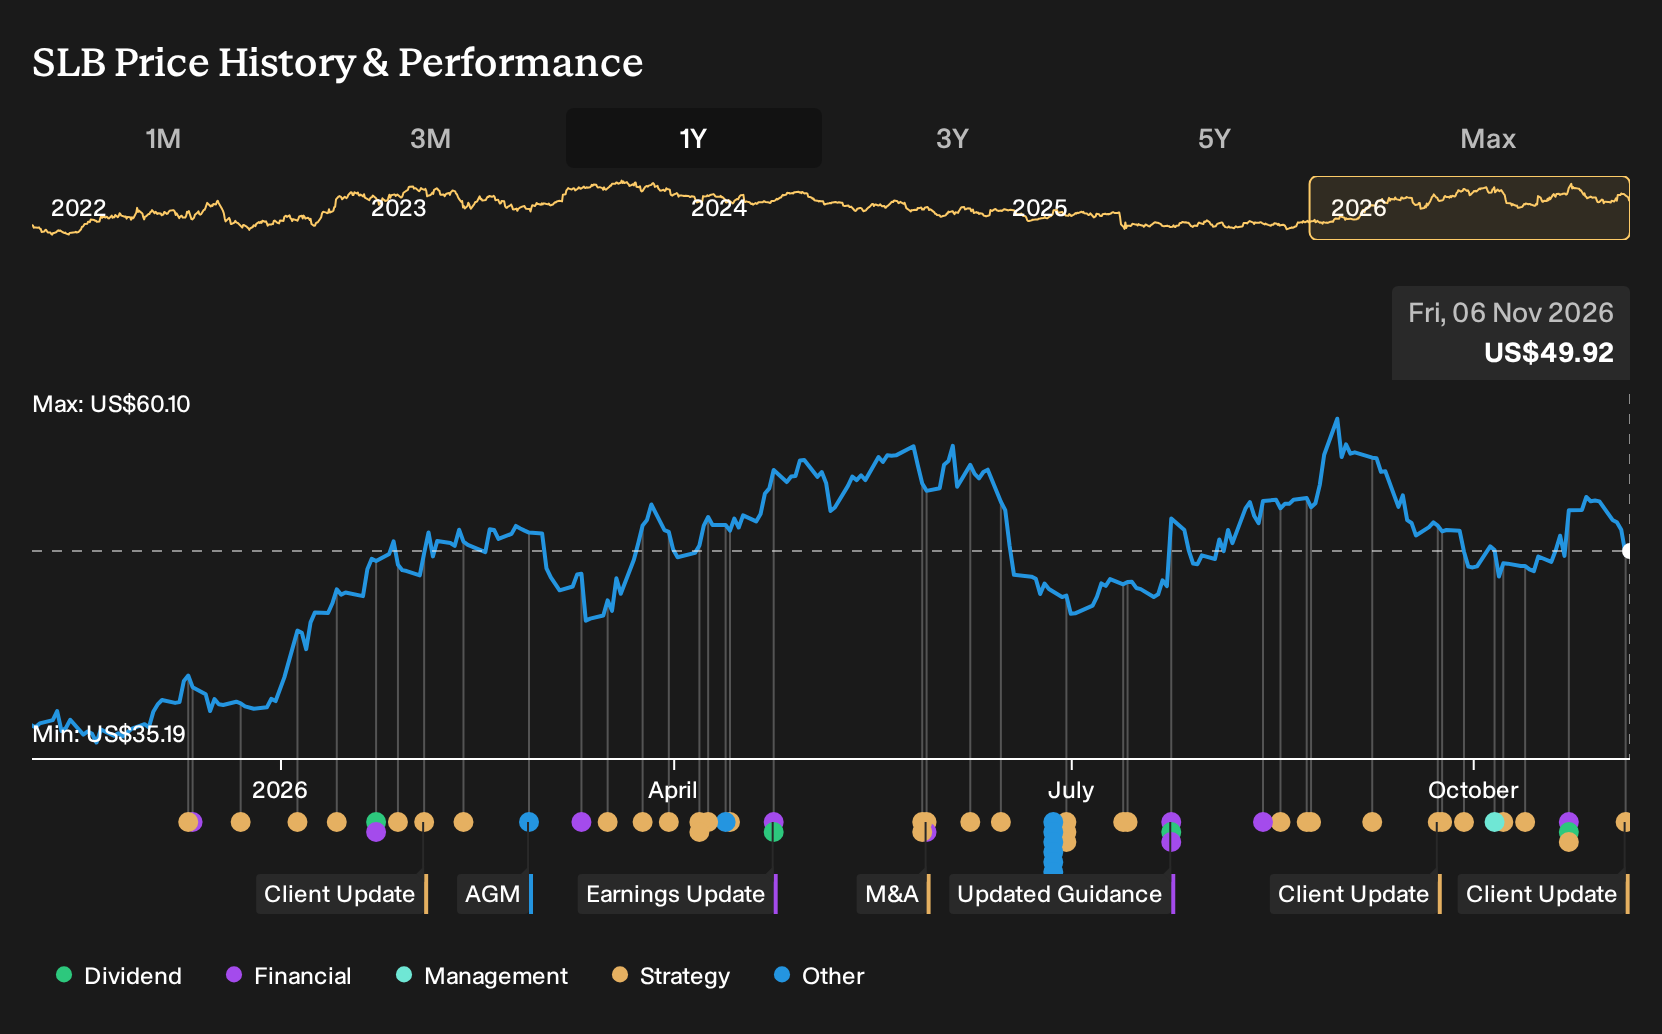
Discover how SLB's fair value indicates a 25% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame SLB around data center and subsea upside rather than Middle East risk. Before this Lyra contract, they were mapping out revenue of about US$51.2b and earnings of US$7.3b by 2029, far above consensus. You do not need to agree. Use those upper end assumptions as one lens and stress test your own view as fresh contracts like Lyra arrive.
Explore 5 other SLB fair value estimates, including one that suggests as much as 72% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SLB research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SLB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SLB's overall financial health at a glance.
Looking for more investment ideas beyond SLB?
Once you have a view on SLB, it often helps to compare it with a broader mix of opportunities that fit different roles in your portfolio. The Simply Wall St Screener can help you quickly surface companies with traits that match the kind of risk, income or quality profile you want.
- For investors hunting for stocks with stronger balance sheets and healthier fundamentals, start with this list of solid balance sheet and fundamentals (24 results) and see which businesses clear a higher financial bar.
- If capital protection matters more to you than chasing maximum upside, scan a set of 29 resilient stocks with low risk scores that aim to keep volatility and business risk in check.
- For those who like finding earlier stage opportunities before they are widely followed, filter for 19 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com