
What Marriott International (MAR)'s Earnings Report Means For Shareholders
- Marriott International reported third quarter revenue of US$7,005 million and net income of US$794 million, alongside continued network growth that includes a new Luxury Collection resort in Luang Prabang and fresh branded openings in Dallas.
- The mix of higher reported earnings, dividend affirmation at US$0.73 per share, and expansion into both luxury and lifestyle segments underlines how Marriott International is leaning on fee based growth across very different demand pools.
- Next, the focus will be on how Marriott International’s stronger reported quarterly earnings could influence the existing investment narrative around fee based expansion.
Scan how Marriott International’s latest dividend and hotel openings compare with peers by reviewing a curated 8 dividend fortresses built for income focused investors watching balance sheet strength and cash returns.
Marriott International Investment Narrative Recap
To own Marriott International, you need to be comfortable with a fee heavy, asset light model that leans on consistent travel demand, a large development pipeline, and a very scaled loyalty program. The latest quarter showed higher reported revenue of US$7,005 million and net income of US$794 million, which supports that narrative rather than changing it.
The near term swing factor is execution on global rooms growth while managing weaker travel in parts of the Middle East and keeping owners satisfied with Bonvoy economics. The key risk stays the same. If RevPAR softness lingers or owner level returns disappoint, fee growth and margins could come under pressure.
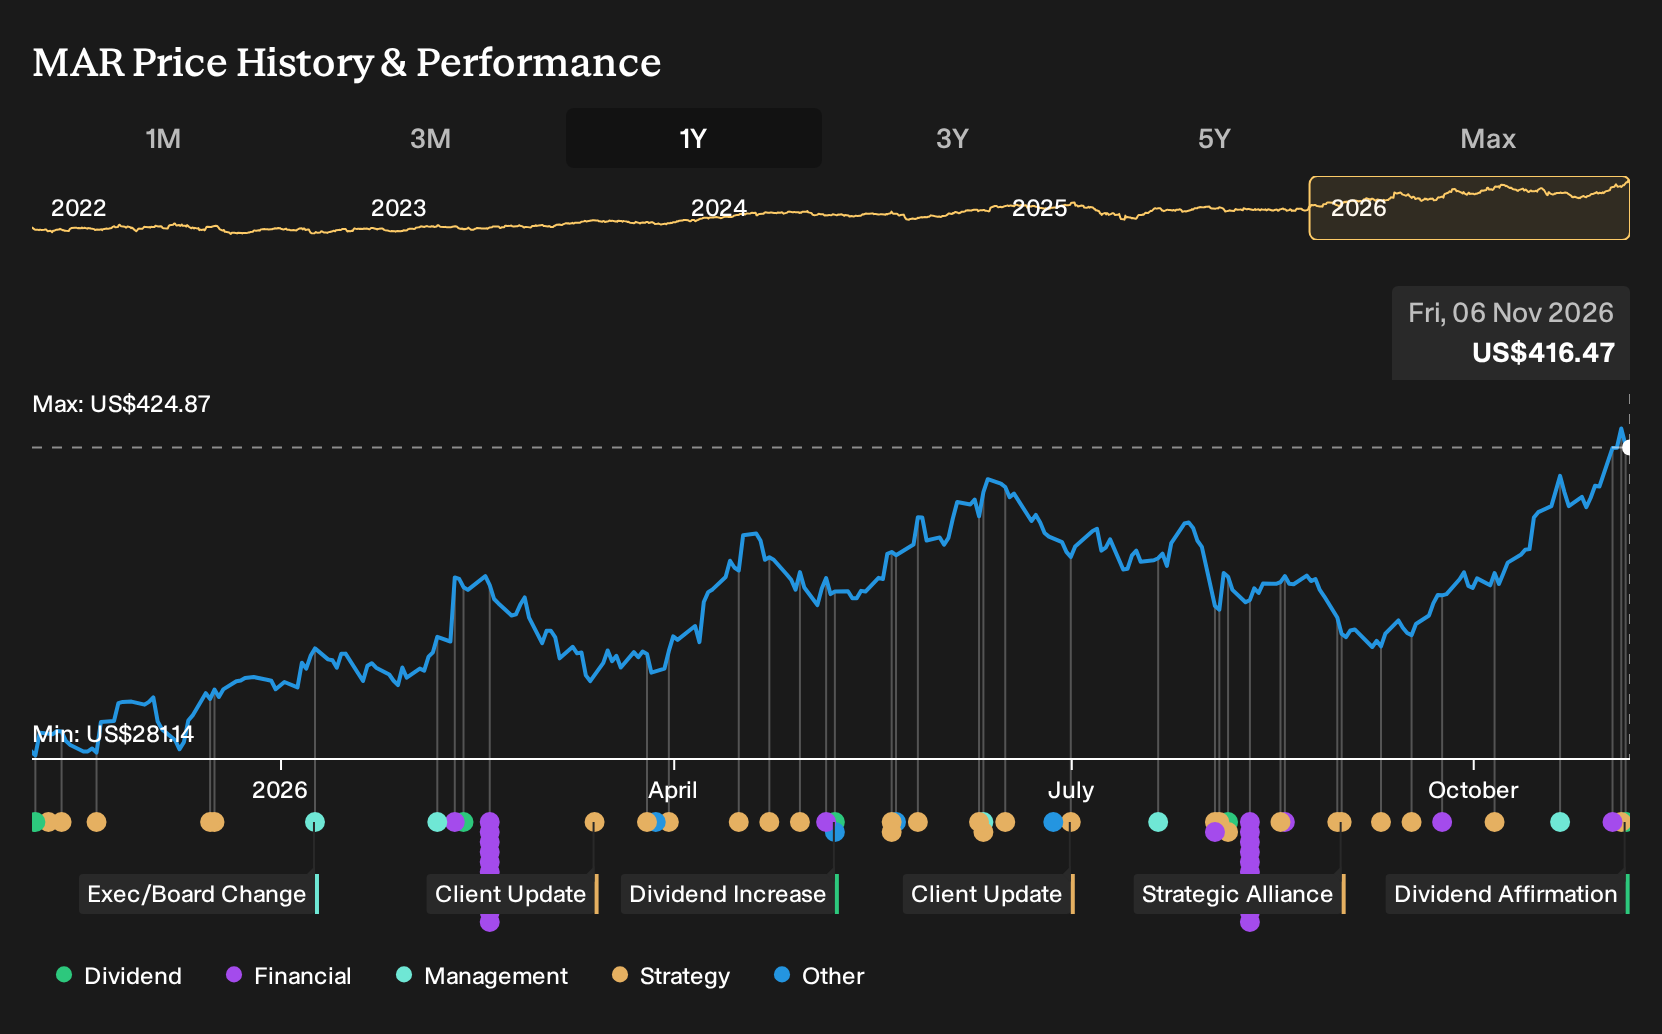
The fresh quarterly dividend affirmation at US$0.73 per share is the clearest operational signal in this set of announcements. It suggests Marriott International is operating with sufficient confidence in its fee streams and balance sheet to continue returning cash, even as it funds technology upgrades, loyalty investments, and growth incentives for owners.
For catalysts, that dividend sits alongside reported gains in revenue and earnings and continued unit expansion such as the Laos resort and new AC and Moxy hotels in Dallas. Together, these factors keep the focus on whether management can translate a record pipeline and a growing Bonvoy ecosystem into durable fee income while absorbing regional conflict risk and volatility in non fee lines.
Marriott International’s current analyst narrative points to forecast revenue of US$31.5b and expected earnings of US$3.8b by 2029, built on an assumed 62.2% yearly increase in revenue and an earnings step up of about US$1.2b from roughly US$2.6b today.
Uncover how Marriott International's fair value indicates a 6% potential downside to its current price, which may reflect a premium investors need to watch closely.
Exploring Other Perspectives
Some bullish analysts focus on Marriott International’s expansion story instead of Middle East risk. Before this dividend and Laos opening, the most optimistic forecasts were for revenue of about US$39.7b and earnings of US$4.4b by 2029. That is far above the US$31.5b and US$3.8b consensus, so treat it as one of several viewpoints to test.
Explore 3 other Marriott International fair value estimates, including one that suggests it could be worth as much as $407.58.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Marriott International research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marriott International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marriott International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Marriott International?
If Marriott International is just one position on your radar, it can help to scan a wider field of opportunities that match your style on income, quality, or risk control.
- If you want to prioritize resilience and capital preservation, start with a curated set of 29 resilient stocks with low risk scores that score well on stability while still offering equity upside.
- For investors hunting for quality at a reasonable tag, filter for candidates trading below their assessed worth using the 39 high quality undervalued stocks that combines balance sheet strength with solid fundamentals.
- Income oriented portfolios can lean on a 8 dividend fortresses that highlights companies offering higher yields with an emphasis on durability of payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com