
What i-80 Gold Doubters Missed
Investors who held i-80 Gold over the past year are up 51.5%, including dividends. That result sits against a backdrop where early 2025 research already split sharply, with one group of analysts arguing the business was worth 78% above the start price and another suggesting fair value sat 18% below. If you had been weighing those opposing views on 6 November 2025, which evidence would have mattered most to you?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
i-80 Gold is not the only name tied to this theme. Zero in on 33 elite gold producer stocks and compare how each one is priced.
The Two i-80 Gold Stories Investors Had To Hold In Their Head
Shares in i-80 Gold cost CA$1.28 at the start of the period, and anyone weighing up the stock had to choose between two very different but believable stories.
On the optimistic side, one narrative put fair value at CA$2.28, leaning on expectations that higher production from Nevada projects and progress toward using the Lone Tree autoclave would support stronger cash generation.
The more cautious view set fair value at CA$1.05 and focused on heavy funding needs for a multi phase expansion plan and the risk that Nevada specific regulation or environmental constraints could squeeze profitability.
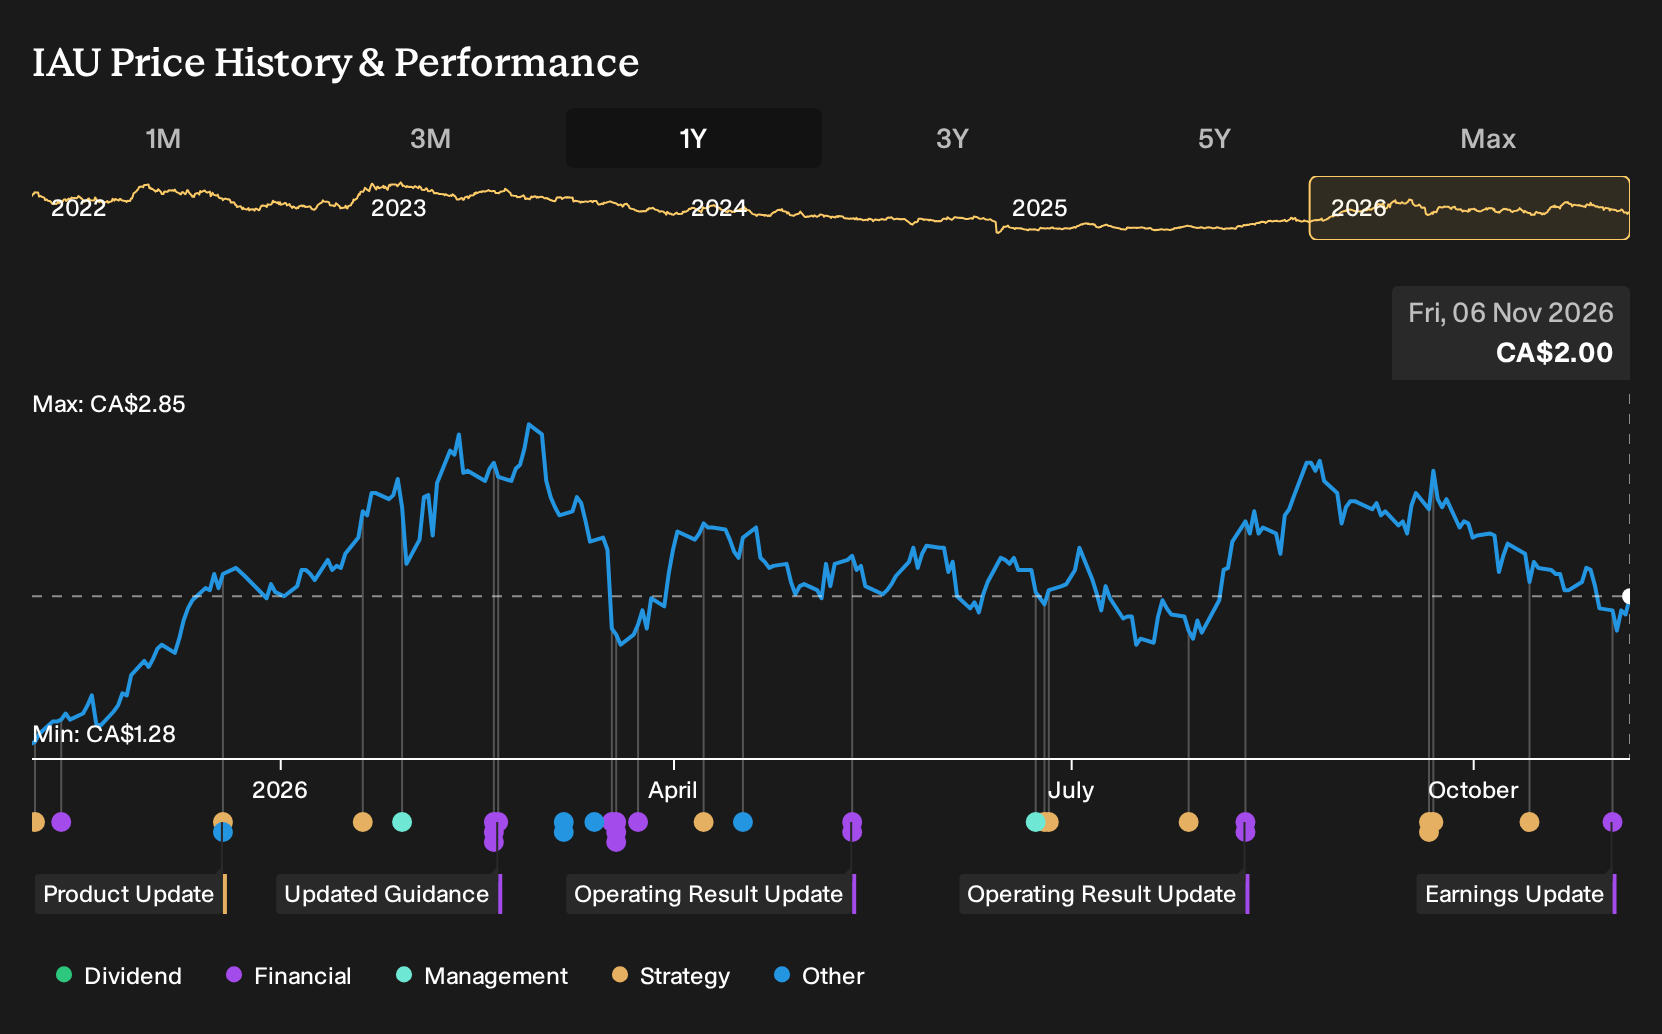
What The Evidence Did To The i-80 Gold Argument
The biggest new fact for i-80 Gold came from its Q3 2026 report. Revenue was US$32.7m compared with US$32.0m a year earlier, while the business still recorded a loss that widened from US$41.9m to US$48.4m as net margin moved further down to -147.7%. That mix of higher sales and weaker profitability cut both ways for the two stories.
The whole episode turned on one assumption investors made in 2025. Execution at Nevada projects was expected to translate quickly into better net margin. As a result, the figure to track at any similar miner is the direction of losses or earnings against each step up in revenue.
What You Are Paying For In i-80 Gold After A 51.5% Run
At CA$2, i-80 Gold trades well above where it started over the past year. The selected Narrative argues that Fair Value sits above the current price, anchored to what happens at the Lone Tree processing hub and the broader Nevada build out.
The storyline now leans on funding risk easing and the Nevada complex doing the heavy lifting on future economics. A buyer today would need to judge whether Lone Tree can move from plan to on-schedule, profitable processing that reshapes cash margins.
"The main factor that has to go right is execution of the Lone Tree hub and Nevada mine build out, including on-time refurbishment of the autoclave, delivery of feasibility studies, and conversion of drilled resources into long-lived, profitable production."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 29% below our estimate - target quick returns from boutiques while scaling digital and app channels.
- Company 2 - 36% below our estimate - expand AVL production and service capacity so orders fund support activity.
- Company 3 - 34% below our estimate - integrate design acquisitions and route project work through digital and AI centers.
That is three of the list. See all 6 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com