
Profit Return Might Change The Case For Investing In Precision Drilling (TSX:PD)
- Precision Drilling reported third quarter 2026 results with sales of C$531.65 million and net income of C$20.92 million, compared with a loss in the same period last year.
- The shift from a third quarter loss to earnings of C$1.65 per basic share highlights how recent operations supported a return to profitability.
- We will now look at how Precision Drilling's investment narrative may be affected by this return to profit in the quarter.
Precision Drilling Investment Narrative Recap
To own Precision Drilling, you need to believe the high spec rig upgrade story and digital automation push can translate into steadier utilization and healthier day rates, even with a cyclical backdrop. The third quarter swing to a C$20.92 million profit and C$1.65 in basic EPS supports that thesis in the short term but does not remove execution risk.
The key near term catalyst is still whether customer demand for upgraded rigs and automation holds up enough to justify planned 2026 capital spending of C$265 million. The biggest current risk sits in that same spending plus higher depreciation, which could squeeze free cash flow if returns on those upgrades lag expectations.
The latest third quarter earnings release is the relevant reference point. Precision Drilling reported C$531.65 million in quarterly revenue and moved from a C$6.76 million loss a year ago to C$20.92 million in profit, while nine month earnings of C$37.1 million remain below the prior C$44.02 million period. That mix of progress and strain is what you are really underwriting.
For catalysts, this print ties back directly to the upgrade and automation program. The quarter shows the business can produce earnings while still carrying heavier capital and depreciation loads, which matters if you are watching rig economics closely. At the same time, the tax reassessment exposure and logistics costs called out in the risk framework sit in the background as potential cash flow drags if operating momentum softens.
Precision Drilling Forward Assumptions And Valuation Anchors
Analysts frame the next phase of the Precision Drilling story around gradual revenue expansion and a sharp earnings reset. The projections call for revenue to rise by 4.2% a year over the coming three years, with profit margins moving from a loss position of 1.7% today to 12.0% in that same timeframe. On top of that, consensus expects earnings to climb from a loss of C$32.8 million today to C$260.7 million by 2029, an increase of roughly C$293 million, with forecasts ranging between C$188.6 million and C$305.1 million. On these numbers, the analysts are effectively underwriting a move to about C$2.2b of revenue and C$260.7 million of earnings in 2029, at a P/E of 8.8x versus a current implied multiple of 53.2x driven by loss making results.
Precision Drilling's narrative projects C$2.2b revenue and C$260.7 million earnings by 2029. This implies 4.2% yearly revenue growth and an earnings increase of roughly C$293 million from current earnings of a C$32.8 million loss.
For anyone tracking valuation closely, these inputs matter more than the headline price target. The consensus fair value work assumes that, by 2029, Precision Drilling is earning that C$260.7 million on C$2.2b of revenue and that the market is comfortable paying an 8.8x P/E multiple for those profits using a 7.4% discount rate. Analysts also bake in a 3.24% annual reduction in share count over the next three years, so a portion of the projected earnings uplift runs through earnings per share as much as through the income statement itself.
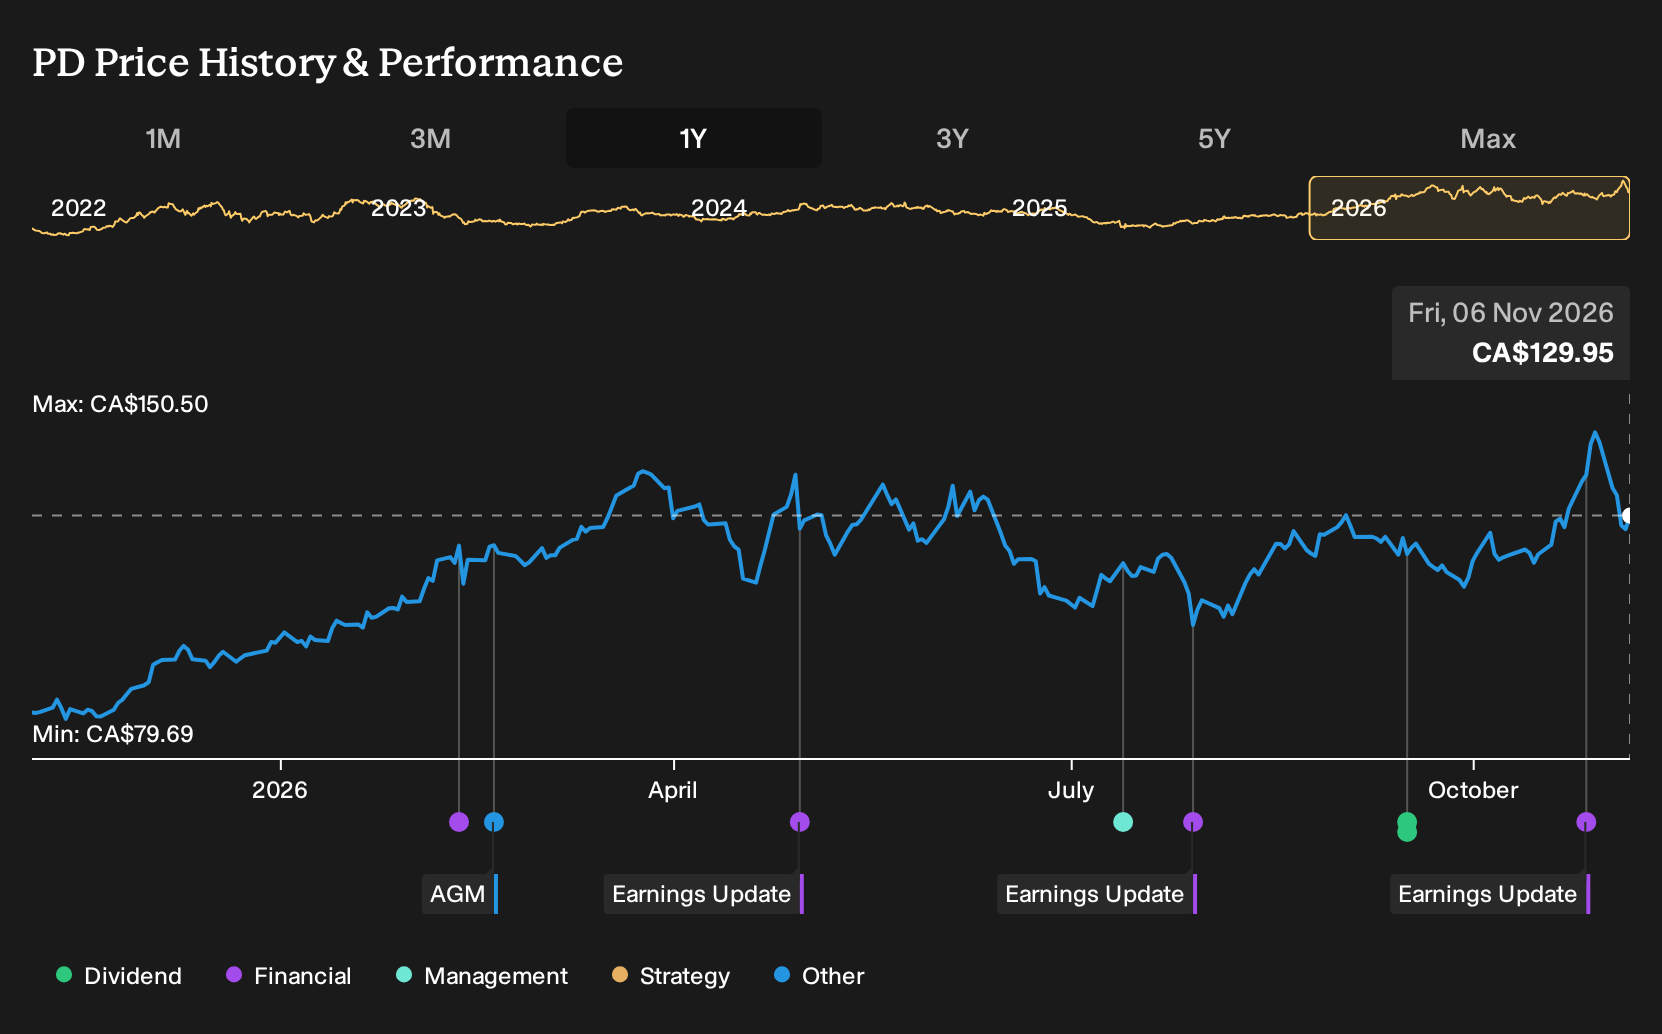
The current analyst price objective of C$161.25 sits 14.2% above the quoted C$138.39 share price as at October 2026. However, the more useful takeaway for you is how much has to go right to match the model. The story combines modest top line expansion, a swing from loss making margins to double digit profitability and continued capital returns via buybacks, all while funding a C$265 million 2026 capital program and managing C$320 million of depreciation. If you are stress testing the Precision Drilling thesis, the key question is whether that blend of revenue growth, margin repair and capital discipline feels achievable enough to justify the assumptions embedded in these 2029 forecasts.
Uncover why Precision Drilling's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into technology adoption as the real catalyst for Precision Drilling. Before this earnings release, the bullish camp was pencilling in about C$2.4b of 2029 revenue and C$305.3 million of earnings. Those expectations were set without seeing this profit return, so you should expect views to evolve as fresh results filter through the models.
Explore 3 other Precision Drilling fair value estimates, including one that suggests as much as 274% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Precision Drilling research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Precision Drilling. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Precision Drilling's overall financial health at a glance.
Looking For More Investment Ideas Beyond Precision Drilling?
If the Precision Drilling story has sharpened your thinking about risk, balance sheets and earnings power, it can be useful to test that framework on a wider set of opportunities using the Simply Wall St Screener.
- For investors who want income with staying power, start with businesses that aim to pair meaningful yields with financial resilience by checking out 3 dividend fortresses.
- If capital preservation matters just as much as upside, focus on companies with sturdier finances and lower assessed risk through our 9 resilient stocks with low risk scores.
- When you want to move beyond crowded trades, look for under-the-radar opportunities with solid fundamentals by scanning the 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com