
Is Constellation Energy (CEG) Undervalued With $5b Nuclear Expansion Backing Earnings?
Constellation Energy has seen its share price swing sharply, with a steep year to date pullback sitting alongside a very strong three year return, which puts fresh focus on what investors are currently paying for its earnings. With that kind of whiplash, the key issue is whether the recent price reset lines up with the profits the business is generating today and what those profits could support over time.
- Over the past three years Constellation Energy has delivered a 109.2% share price gain, which makes the current earnings based valuation question much more consequential for anyone who has held through that run or is thinking about entering now.
- The conditional US$5b loan commitment from the Department of Energy to upgrade existing nuclear plants may support earnings power over time by spreading hefty capital costs over a larger, contracted output base that includes major data center customers.
- Your read on Constellation Energy is one view; the desks covering it have another. See what analysts think Constellation Energy's shares could be worth.
The stock's next move may depend on whether Constellation Energy's current price can be squared with the level and quality of its earnings.
If you want to stress test this same earnings question beyond Constellation Energy, you can review a wider set of power grid plays using 42 power grid technology and infrastructure stocks.
Is Constellation Energy a Bargain on Earnings?
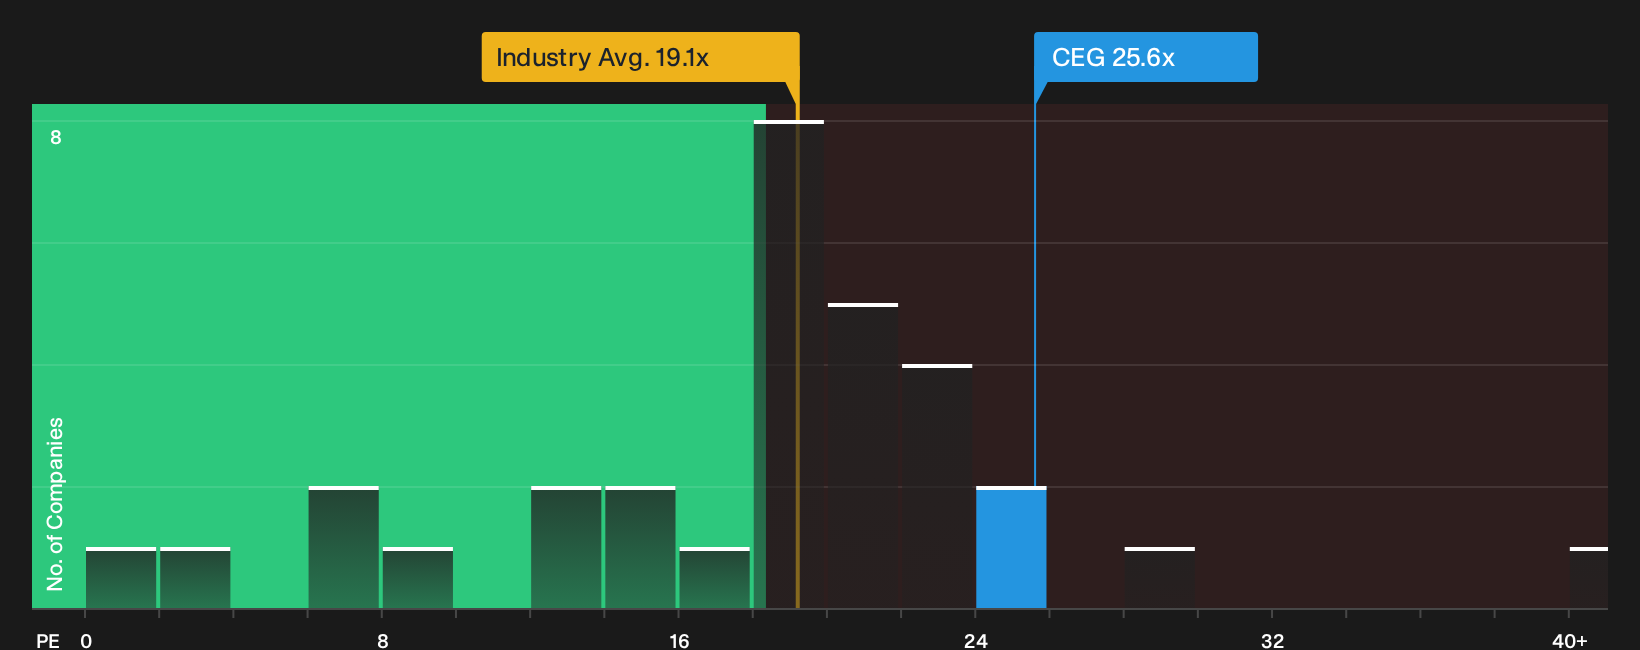
The P/E ratio is a useful starting point for Constellation Energy because earnings still anchor how investors think about a regulated utility and its contracted power sales. On this lens the stock trades on about 25.6x earnings, which is above both the Electric Utilities sector average of roughly 19.1x and the peer group on about 21.7x.
The valuation model that blends Constellation Energy’s growth profile, margins, industry, size and risk points to a higher tailored multiple than where the shares change hands. As a result, the current P/E screens undervalued against that yardstick even though it carries a premium to the broader group. Because the US$5b Department of Energy loan is tied to specific nuclear uprate projects and contracted data center demand, the earnings that support this multiple link partly to projects with clearer visibility than many investors might expect. Explore the numbers behind Constellation Energy's P/E valuation.
The Constellation Energy Narrative: What Would Justify Today's Price?
Constellation Energy's valuation puzzle sets up a natural question that Simply Wall St Narratives aim to answer: what specific paths for earnings, margins and growth would need to play out for the stock to be worth materially more or materially less than where it trades today. Narratives on the Community page turn that into a set of plain scenarios, each pinned to a clear view on how growth, profitability and risk could evolve, giving you a reference point you can test again as fresh information comes through.
One of the top community narratives on Constellation Energy: 27% undervalued
"Growing demand for carbon free, reliable power from large scale customers such as data centers and large corporates is now translating into roughly 920 MW of long duration nuclear power contracts…"
Discover why this Narrative puts Constellation Energy at 27% undervalued.
Constellation Energy's price is only one piece of the decision
Constellation Energy’s valuation story only goes so far without checking what the risk filters are quietly flagging in the background, and those red and amber signals can change how you weigh everything else. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com