
Cheesecake Factory (CAKE) Could Be 31% Undervalued As Q3 Results Lift 2027 Growth Hopes
Cheesecake Factory (CAKE) is back in focus after third quarter results, new guidance and a fresh expansion plan converged into one busy October 27 update for investors.
Cheesecake Factory’s shares closed at $106.76 after a single day share price return that declined 3.57%, while the 1-week move fell 5.22%. However, the year to date share price return of 102.16% and 1-year total shareholder return of 129.10% reflect strong momentum that has been reinforced by the better third quarter results, fresh guidance for 2027, and a busy restaurant opening pipeline.
Discover restaurants with momentum and expansion plans similar to Cheesecake Factory by exploring our hand-picked 19 high quality undiscovered gems for your next round of ideas.
After a 102.16% year to date run and a 1-year total shareholder return of 129.10%, Cheesecake Factory now trades almost exactly in line with analyst targets, while implying a meaningful premium to some intrinsic value estimates. Is the recent surge already pricing in the 2027 plan, or leaving room for upside in the fair value range that follows?
Most Popular Narrative: 31% Undervalued
At a last close of $106.76, the most followed narrative on Cheesecake Factory pegs fair value much higher at $154, implying a sizeable valuation gap that investors are actively debating.
CAKE is one of the most interesting stocks I own, and if you are not following it closely, you probably do not know the real reason why. On the surface it looks simple. The Cheesecake Factory prints cash day in and day out, pays a rock solid dividend, and gives money back to shareholders. That part is real. But the part that actually excites me is this: I think CAKE has a legitimate shot at becoming a true growth company, and almost nobody is pricing it that way.
See why 36 investors see Cheesecake Factory as 31% undervalued.
According to RedCandleRx, that fair value estimate of $154 is built from a blended Bull, Base, and Bear scenario that averages to a 31% discount to the current narrative fair value. The approach centres on projected earnings per share and applies different P/E multiples in each case, then combines those paths into a single fair value figure rather than relying on one forecast.
The same narrative anchors on Cheesecake Factory earning power over time, not just the current restaurant footprint. It points to a mix of steady cash generation from the flagship Cheesecake Factory brand, expansion of Flower Child and North Italia, and optionality from Fox Restaurant Concepts as key supports for that $154 figure.
Result: Fair Value of $154 (UNDERVALUED)
Still, the Cheesecake Factory narrative could be knocked off course if the expansion pipeline underperforms expectations or if consumer spending weakens and squeezes restaurant level returns.
Find out about the key risks to this Cheesecake Factory narrative.
Another View On Cheesecake Factory’s Valuation
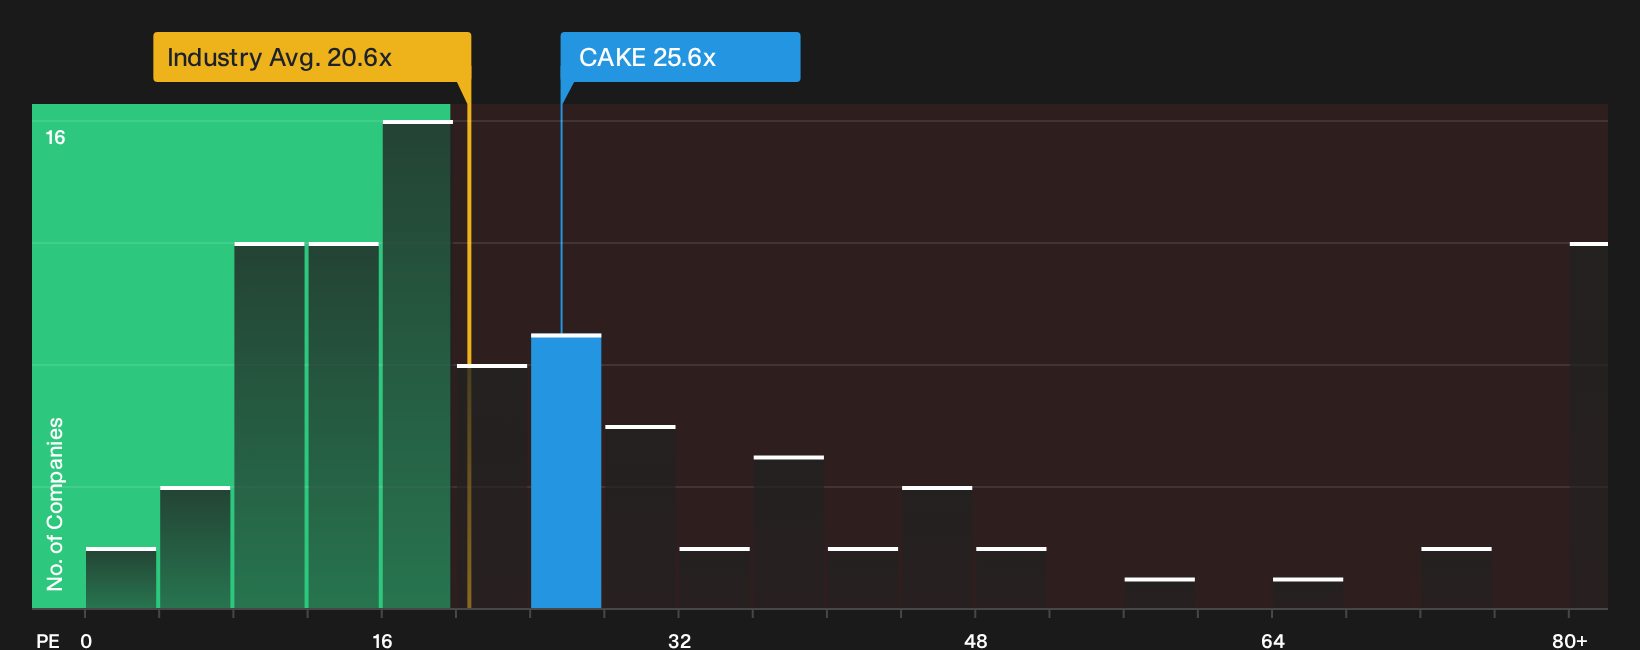
The community fair value of $154 for Cheesecake Factory presents a very different picture when compared with simple earnings multiples. At a P/E of 25.6x, the stock trades above both the US Hospitality industry on 20.8x and an estimated fair ratio of 19.2x. That kind of premium can either signal quality or leave far less margin for error if the expansion story slows.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed messages in Cheesecake Factory’s story today. If you want to move quickly and judge the balance of optimism and concern for yourself, start by weighing its 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cheesecake Factory?
If Cheesecake Factory has sharpened your focus, do not stop here. Broaden your watchlist now and let data rich ideas meet your own judgment.
- Target resilient balance sheets and consistent fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) tailored to financially sturdy businesses.
- Zero in on potential value opportunities by reviewing the 39 high quality undervalued stocks that combines quality metrics with discounted pricing.
- Prioritise stability and cash returns by checking the 8 dividend fortresses designed for investors who want income alongside potential capital gains.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com