
Learn Why The Bull Case For W. P. Carey Stock Could Change Following Third Quarter Earnings
- W. P. Carey reported third quarter 2026 results, with sales of US$422.5 million, revenue of US$468.3 million and net income of US$140.95 million. Earnings per share from continuing operations came in at US$0.61 on both a basic and diluted basis.
- Across the first nine months of 2026, W. P. Carey showed higher sales and revenue, along with materially higher earnings per share from continuing operations compared with the prior year period. This reflects how recent deployment and lease terms are feeding through the income statement.
- Attention now turns to how W. P. Carey’s investment narrative incorporates this combination of solid nine month earnings and flatter quarterly profit.
Scan how W. P. Carey’s earnings pattern compares with other income focused opportunities by reviewing the hand picked 8 dividend fortresses in this market.
W. P. Carey Investment Narrative Recap
To own W. P. Carey, you need to be comfortable with a large, long lease net lease portfolio where rent escalators and steady deployment drive the story more than rapid expansion. The latest quarter shows higher sales and revenue but flatter profit. That mix keeps the focus on execution of the investment pipeline and tenant quality rather than headline earnings.
The key short term swing factor is how efficiently W. P. Carey converts its prefunded balance sheet and deployment guidance into rent and AFFO, without taking on outsized tenant or financing risk. Debt coverage by operating cash flow and exposure to single tenant, sub investment grade leases remain the main pressure points, and this quarter does not materially change that risk profile.
The most relevant disclosure to frame this quarter is management’s 2026 deployment context. Year to date net lease investing of US$1.3b at a 7.4% initial cash cap rate, with investment yield guidance of US$1.7b to US$2.1b for the full year, helps explain why nine month earnings are materially higher even as third quarter profit is flat.
For you as a shareholder, that investment tempo links directly to near term catalysts and vulnerabilities. Contractual rent escalations, CPI linked leases and a largely prefunded balance sheet give W. P. Carey room to keep sourcing industrial, warehouse and retail assets, while any slowdown in capital markets or tenant credit stress could quickly test how resilient that acquisition led earnings profile really is.
W. P. Carey’s current analyst story points to revenues of US$2.3b and earnings of US$893.9 million by 2029, based on an assumed 6.6% yearly revenue growth rate and an earnings increase of roughly US$242.9 million from earnings today of US$651.0 million.
Uncover why W. P. Carey's fair value indicates a 14% potential upside to its current price that could narrow quickly.
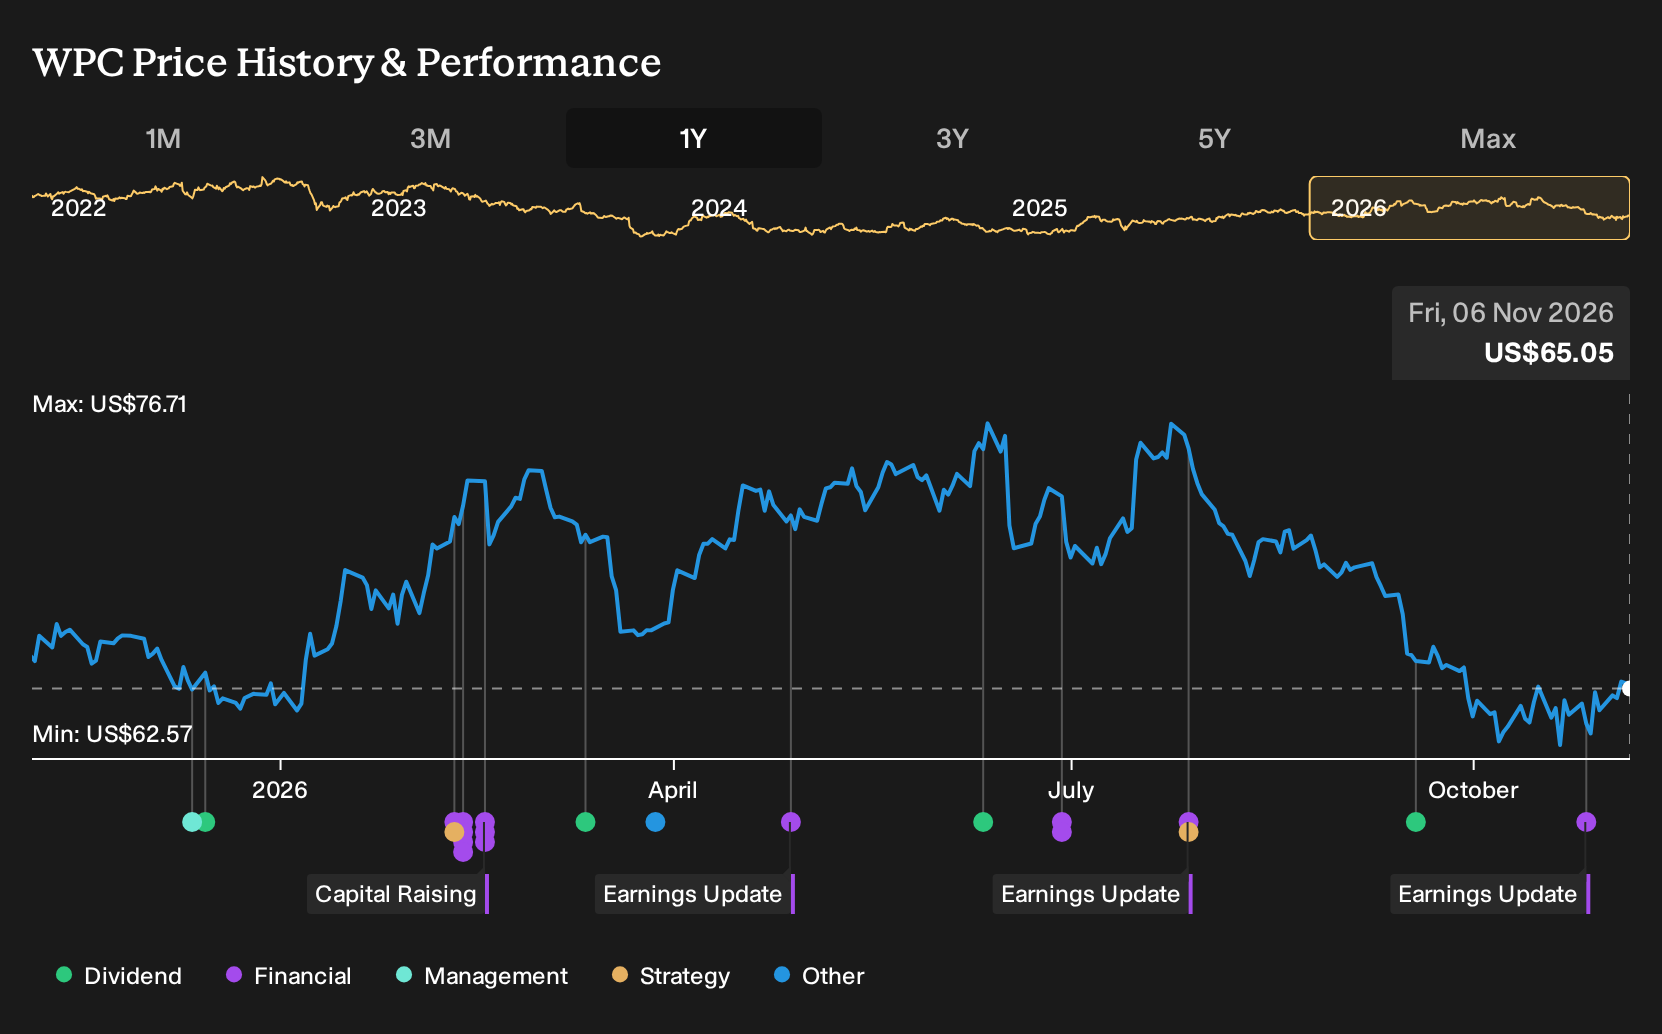
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly US$74 at the low end to about US$166 at the top, so you are looking at very different expectations for W. P. Carey. When you then consider tenant credit risk, funding costs and rent escalators, you can quickly see why opinions split. Explore those alternative viewpoints.
Explore 3 other W. P. Carey fair value estimates, including one that suggests as much as 156% potential increase from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your W. P. Carey research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for W. P. Carey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate W. P. Carey's overall financial health at a glance.
Looking for more investment ideas beyond W. P. Carey?
Once you have formed a view on W. P. Carey, it can help to scan a wider watchlist so your capital is not tied to a single story. The Simply Wall St Screener is built for exactly that kind of comparison, letting you line up different businesses against the same set of rules.
- If you want income without taking on every balance sheet surprise, start with a curated list of solid balance sheet and fundamentals (24 results) that already clears basic financial strength checks.
- For investors who prefer to pay less for each dollar of quality, review the hand picked 39 high quality undervalued stocks and see which stocks currently line up with that filter set.
- When you would rather keep risk in check and avoid the most volatile stories, scan a focused group of 29 resilient stocks with low risk scores that pass tighter stability criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com