
Southwest Airlines (LUV) Could Be 11% Undervalued On Its Cash Flow Reset
Southwest Airlines (LUV) has just tapped bond markets with new fixed rate notes, a funding move that puts fresh attention on how its balance sheet choices intersect with the stock’s recent performance.
The fresh debt arrives at a moment when momentum in Southwest Airlines’ stock has started to rebuild. The 7 day share price return of 4.76% and 30 day gain of 6.54% contrast with a 90 day share price return that is still down 5.53%. At the same time, the 1 year total shareholder return of 39.42% and 3 year total shareholder return a little above 2x both point to a much stronger longer term ride than the 1 day move suggests.
Scan how Southwest Airlines’ bond-funded overhaul compares with other carriers by running the same filter across list of solid balance sheet and fundamentals (24 results) in the wider market.
Southwest Airlines now has improving cash generation, new fixed rate notes and a recovering share price. The business looks stronger. The open question is whether the current valuation already reflects that reset.
Most Popular Narrative: 10% Undervalued
On Simply Wall St’s most followed narrative, Southwest Airlines is framed as undervalued, with a fair value of about $49.40 against a last close of $44.45. This comparison puts the bond raise and reshaped balance sheet in a different light for anyone focused on long term cash generation.
Ongoing cost reduction efforts, with hundreds of millions of dollars of identified savings and guided CASM X growth in the low single digits on flat capacity, point to continued efficiency gains that can support operating margin and earnings even when fuel costs are high.
Find out how 32 investors see Southwest Airlines as 10% undervalued.
Result: Fair Value of $49.40 (UNDERVALUED)
Still, elevated fuel costs and reputational flare ups like the Denver incident could pressure demand and margins, which is exactly what the bullish Southwest Airlines narrative depends on.
Find out about the key risks to this Southwest Airlines narrative.
Another View: What Multiples Say About Southwest Airlines
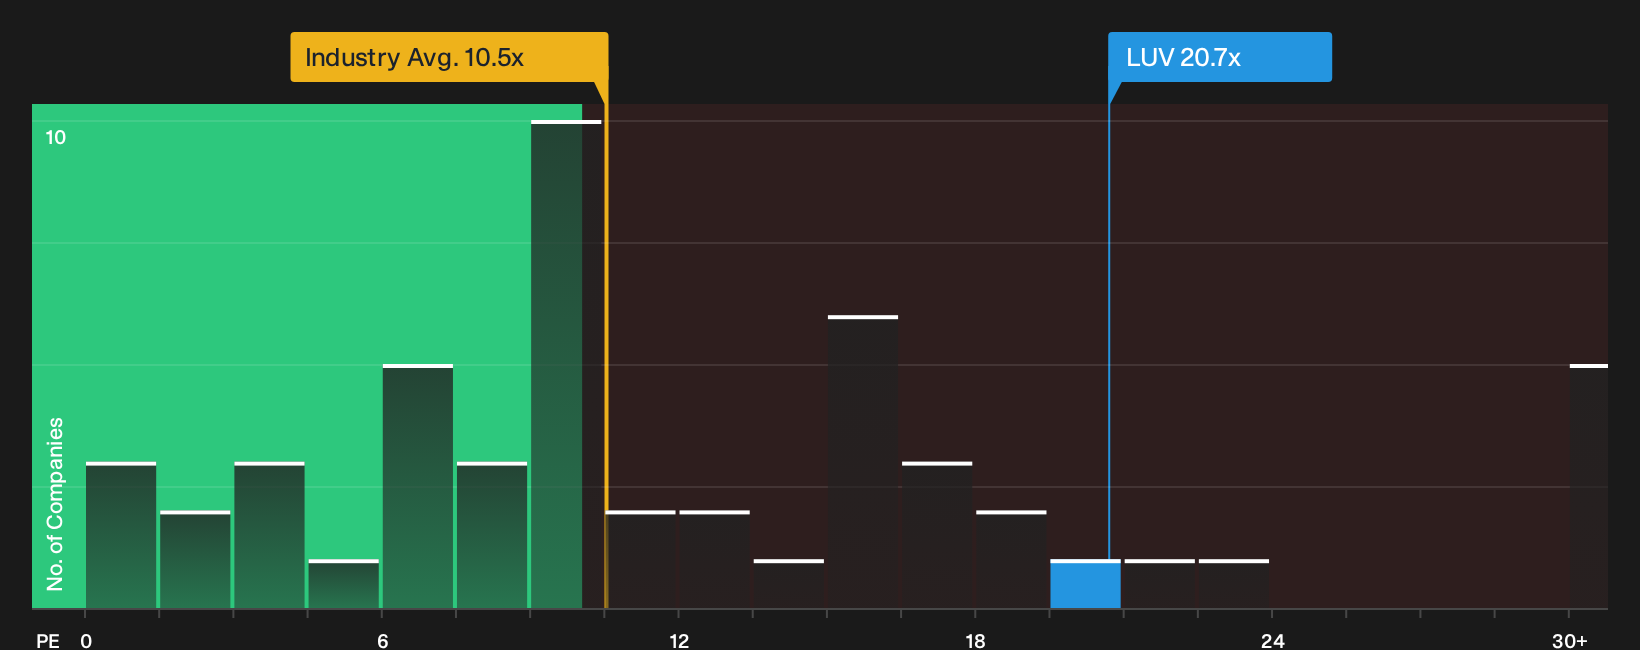
The cash flow story paints Southwest Airlines as attractive, yet the earnings multiple tells a different story. At a P/E of 20.7x, the stock trades at almost double the Global Airlines average of 10.5x and well above peer levels of 11.1x, even though the fair ratio sits at 23.3x. That gap suggests investors face a real question about whether they are paying up for quality or simply accepting valuation risk.
To see how this price tag stacks up against the underlying numbers, and what the earnings multiple implies for future upside or downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Southwest Airlines is mixed, with solid cash flow arguments on one side and valuation questions on the other. Move quickly and stress test the numbers yourself. To see both sides of that debate in one place, start with the 3 key rewards and 1 important warning sign
Ready For More Ideas Beyond Southwest Airlines?
If you stop with just Southwest Airlines, you risk missing other opportunities that fit your style, your risk tolerance, and your return goals.
- Target potential mispricing across quality companies and compare them against Southwest Airlines by scanning the 39 high quality undervalued stocks.
- Identify income candidates that might complement a holding in Southwest Airlines by filtering for reliable payers using the 8 dividend fortresses.
- Manage portfolio volatility and balance exposure alongside Southwest Airlines by focusing on companies highlighted in the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com