
Is Sherwin-Williams (SHW) Cheap Following Its Earnings Beat And Higher 2026 Guidance?
ETF interest after guidance shift
Sherwin-Williams (SHW) drew fresh attention after management lifted full-year 2026 earnings guidance and pointed to higher net sales, coinciding with net buying in the stock by several large ETFs.
Over the past month, Sherwin-Williams has seen its share price return gain 9.24%, and that short term strength contrasts with a 6.93% decline over the past 90 days, while the year to date share price return of 4.96% and 1 year total shareholder return of 2.12% suggest modest momentum building following the recent earnings beat, upgraded 2026 guidance, and fresh credit capacity.
Pace your exposure to Sherwin-Williams by comparing it with a curated pool of quality peers screened for fundamentals strength using our list of solid balance sheet and fundamentals (24 results).The recent 9% rebound in Sherwin-Williams after the guidance lift raises a simple tension. Is this just the opening leg of a repricing, or has most of the easy upside already been used up at US$344?
Most Popular Narrative: 9% Undervalued
The most followed valuation narrative for Sherwin-Williams pegs fair value at $378.33, which is modestly above the last close at $344.10 and presents the recent rebound as only part of the story rather than a full rerating.
The ongoing plan to open 80 to 100 net new Sherwin-Williams Paint Stores Group locations each year on a path toward roughly 6,000 stores, together with the pruning of underperforming sites, increases the reach of the controlled distribution network and can lift revenue and operating earnings as more professional and commercial customers are brought into the system.
See why 45 investors see Sherwin-Williams as 9% undervalued.
Result: Fair Value of $378.33 (UNDERVALUED)
Still, the Sherwin-Williams story can be knocked off course if housing and DIY demand stay weak, or if higher raw material costs squeeze margins for longer than expected.
Find out about the key risks to this Sherwin-Williams narrative.
Another View: Sherwin-Williams on Earnings Multiples
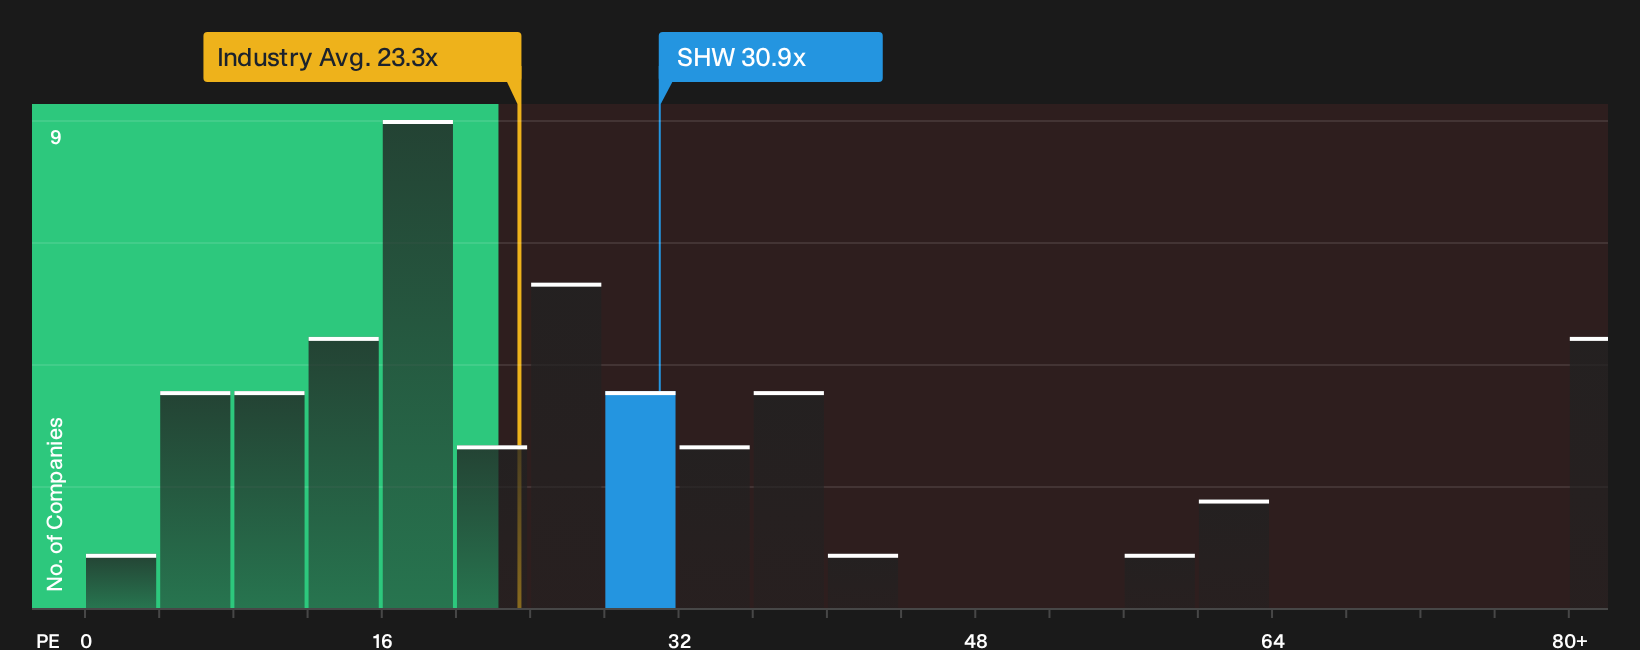
The Sherwin-Williams narrative that leans on a US$378.33 fair value meets a very different picture when you look at the P/E. The shares trade on 30.9x earnings compared with 23.3x for the US Chemicals industry and 26.2x for peers, while the fair ratio points to 20.6x instead.
That gap means you are paying a clear premium for Sherwin-Williams relative to both sector and peer averages, and also well above where the fair ratio suggests the multiple could drift toward if enthusiasm cools. The key question is whether you believe the quality of the business justifies living with that valuation risk.
See what the numbers say about this price with our valuation breakdown. Then compare your own expectations for Sherwin-Williams against the signal from See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed signals around Sherwin-Williams leave you on the fence, move quickly from headline impressions to the underlying detail. The simplest place to start is by weighing up its 2 key rewards and 2 important warning signs.
Looking for more Sherwin-Williams investment ideas?
Do not stop with Sherwin-Williams. Broaden your watchlist with targeted stock ideas that match your risk appetite, income needs, and balance sheet preferences.
- Consider potential mispricing by scanning a curated pool of companies flagged as quality and undervalued using the 39 high quality undervalued stocks.
- Strengthen your income stream by filtering for reliable payers in the 8 dividend fortresses.
- Dial back risk while staying invested by focusing on resilient businesses through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com