
Why Is G-III Apparel Group (GIII) Getting Attention Today?
Coty’s renewed long-term Marc Jacobs beauty license and its G-III Apparel Group (GIII) co-ownership, along with a new Greater China agreement with I.T Group, place the label’s fragrance and fashion reach squarely in focus for investors.
For context, G-III Apparel Group’s recent Marc Jacobs announcements have landed while the share price has risen 16.6% over the past month but declined 11.4% across the last quarter. The 1-year total shareholder return of 15.3% points to momentum that has been positive overall.
Scan G-III Apparel Group alongside other fashion and consumer brands that may be building similar licensing and international growth stories through our hand-picked 19 high quality undiscovered gems.
G-III Apparel Group has climbed 16.5% in a month, yet still trades below both analyst targets and some intrinsic value estimates. Is that a discount worth leaning into, or a sign that the market is correctly pricing caution?
Most Popular Narrative: 10% Undervalued
G-III Apparel Group last closed at $31.41, while the most followed narrative sets fair value at $34.75. This frames the recent share move against expectations for a slower, license light model.
Ongoing replacement of Calvin Klein and Tommy Hilfiger licenses with higher margin owned brands such as DKNY, Donna Karan, Karl Lagerfeld and Marc Jacobs, with roughly US$700 million of the anticipated US$1.2b revenue loss already offset, could continue to support revenue and gross margin mix.
See why 3 investors see G-III Apparel Group as 10% undervalued.
Result: Fair Value of $34.75 (UNDERVALUED)
Still, the loss of the remaining Calvin Klein and Tommy Hilfiger licenses, along with weaker European traffic, could challenge G-III Apparel Group if replacements lag.
Find out about the key risks to this G-III Apparel Group narrative.
Another View: G-III Apparel Group Through a Cash Flow Lens
There is a split story on G-III Apparel Group. While the popular narrative leans on fair value of $34.75 from earnings-based assumptions, the Simply Wall St DCF model points to a future cash flow value of $24.33, which makes the current $31.41 share price look expensive on that basis.
The cash flow view suggests less room for error if license roll offs and forecast earnings declines of 12.4% a year do not improve. It raises a simple question for investors: Which set of assumptions feels closer to how G-III Apparel Group will actually run its business?
Look into how the SWS DCF model arrives at its fair value.
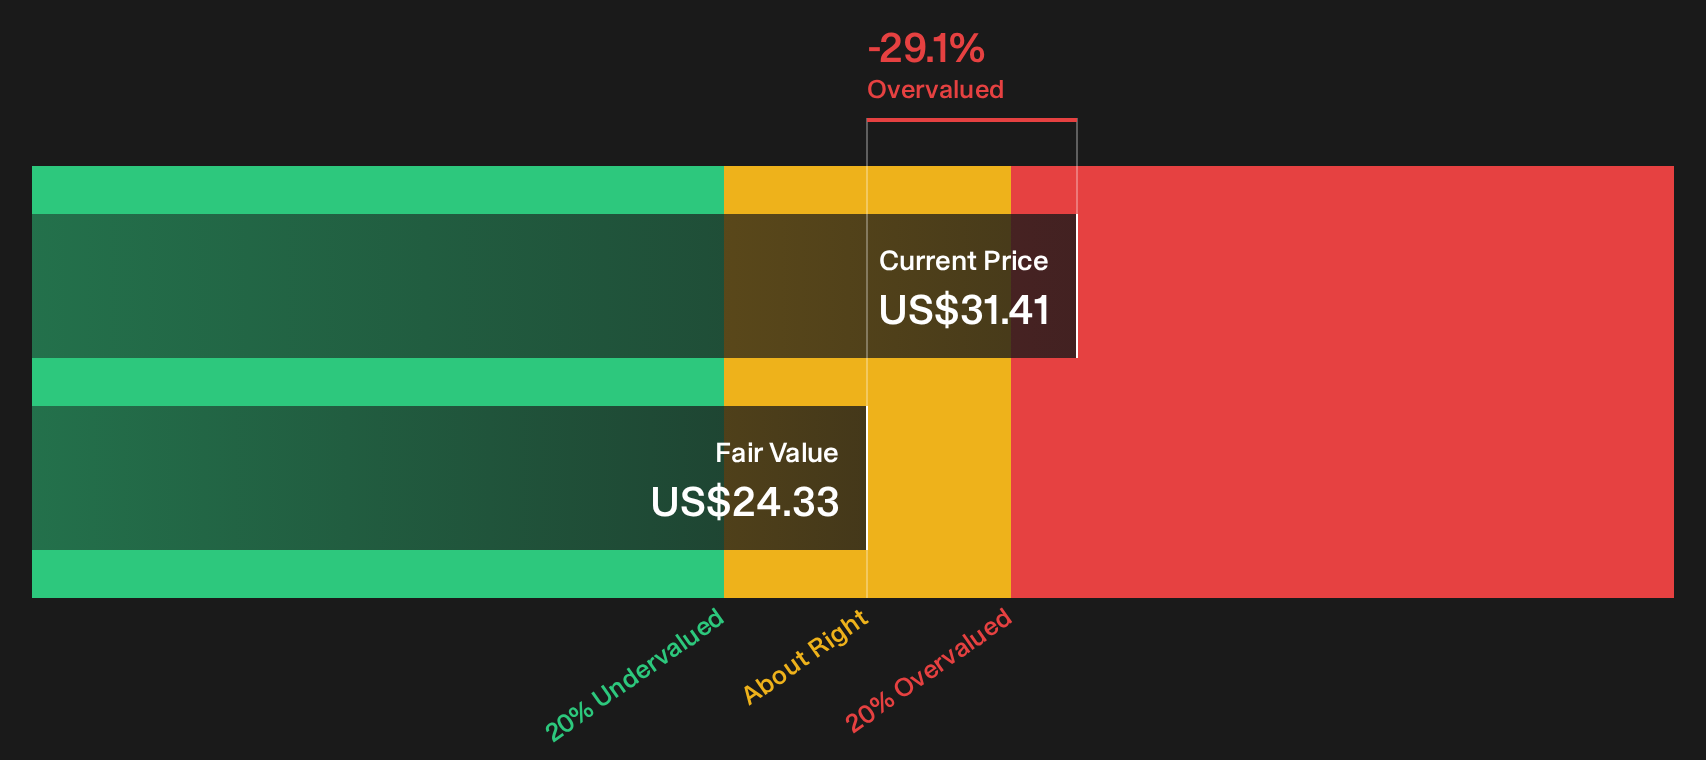
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out G-III Apparel Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around G-III Apparel Group can feel confusing, so use that tension as a prompt to move quickly, review the underlying data, and decide where you stand based on 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond G-III Apparel Group?
If G-III Apparel Group has your attention, do not stop here. The next strong idea could be sitting in plain sight on a different ticker.
- Target consistent income potential by scanning companies that appear in the 8 dividend fortresses and compare their payouts with your own cash flow needs.
- Hunt for potential value opportunities by working through the 39 high quality undervalued stocks where quality fundamentals and pricing sometimes fall out of sync.
- Prioritise resilience by filtering for businesses in the 29 resilient stocks with low risk scores that pair sturdier balance sheets with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com